
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Earnings Beat At Smucker (SJM) Has Changed Its Investment Story
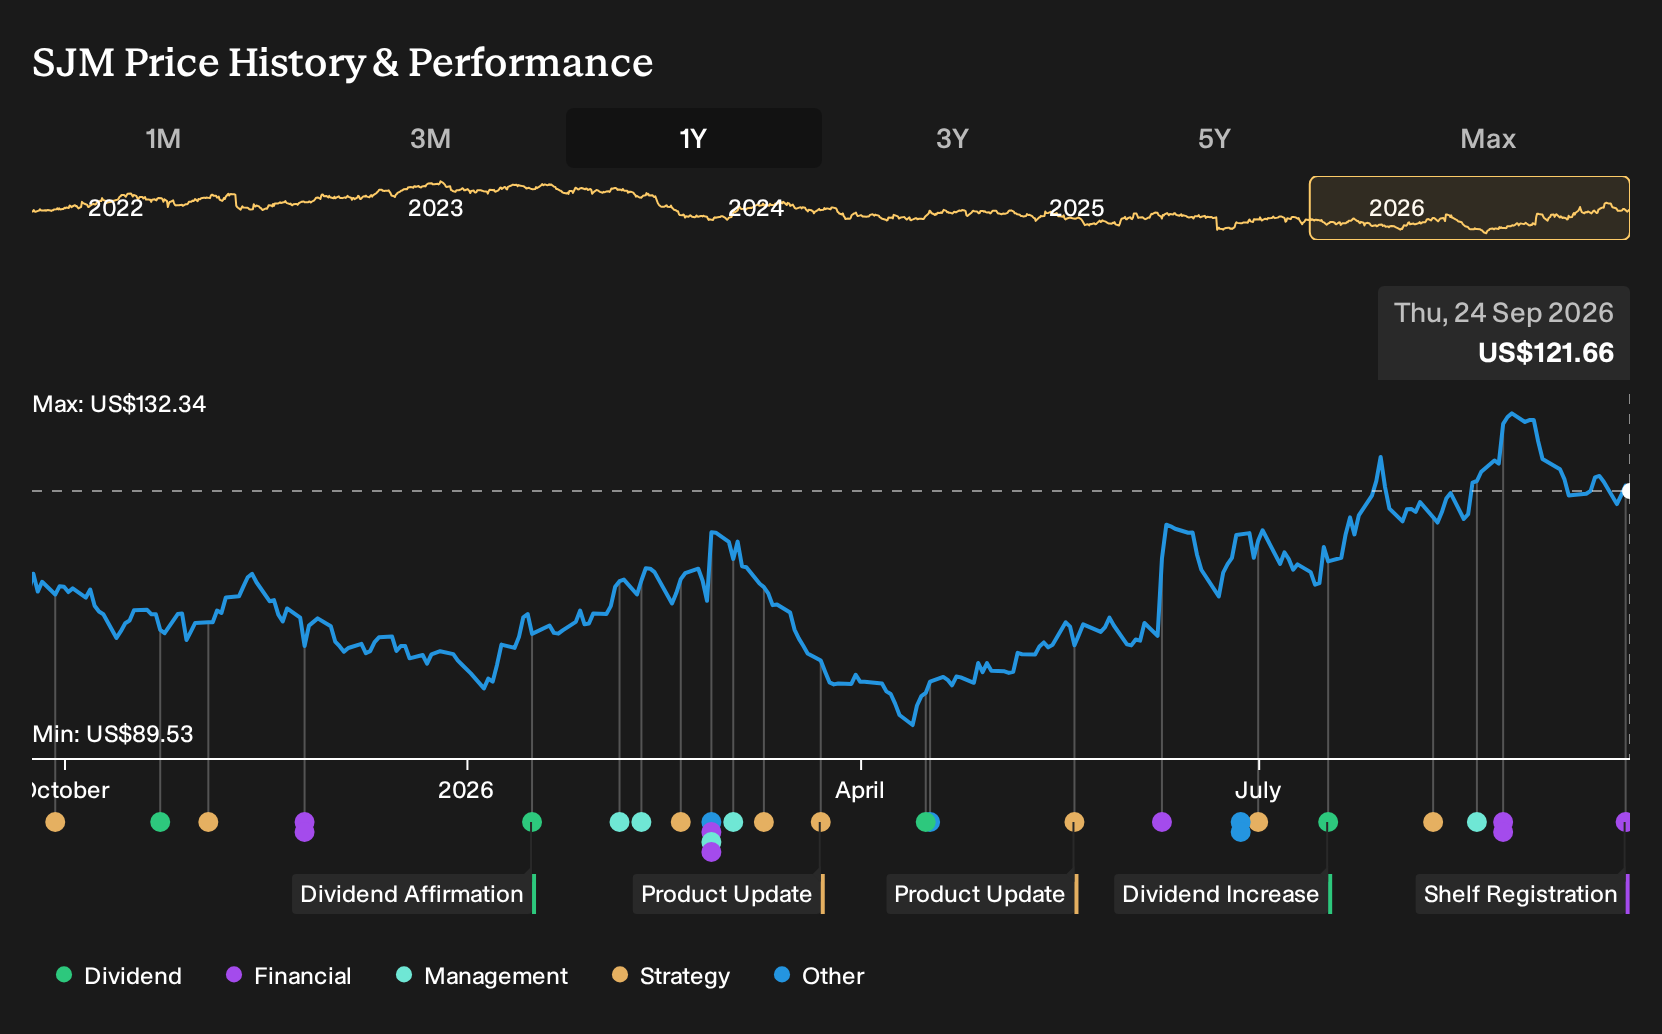
- J. M. Smucker recently filed an omnibus shelf registration covering debt securities, common and serial preferred shares, warrants, and units, following a quarter in which revenue and earnings per share were ahead of analyst expectations.
- The combination of fresh financing flexibility and stronger-than-expected operating results highlights how J. M. Smucker is balancing capital needs with ongoing brand and capability investments.
- We will now look at how J. M. Smucker's stronger-than-expected quarter might reshape the broader investment narrative around the business.
J. M. Smucker Investment Narrative Recap
To own J. M. Smucker, you need to be comfortable with a branded pantry business that leans on pricing power, marketing spend, and portfolio clean up rather than rapid revenue expansion. The recent beat on revenue and earnings suggests execution is holding up. The near term swing factor remains how well Smucker keeps volumes resilient while still protecting margins in coffee, pet, and snacks.
The biggest operational risk still comes from cost inflation, green coffee volatility, and tariff pressure colliding with already elevated shelf pricing. On that front, the strong quarter helps confidence but does not fundamentally change exposure. M&A integration, especially around Hostess and sweet baked snacks, also continues to carry execution risk.
The new omnibus shelf registration feels most relevant here. It gives J. M. Smucker the option to issue debt, equity, preferreds, warrants, or units without returning to regulators each time. That optionality can matter if the firm wants to refinance existing borrowings, fund further automation, or support brand spending in coffee, pet snacks, or Hostess.
Flexibility cuts both ways for you as a shareholder. Access to capital can support SKU rationalization, manufacturing consolidation, and e commerce initiatives that management has been leaning into. On the other side, new securities could dilute existing holders or add leverage to a balance sheet that already relies heavily on external borrowing, so execution and discipline around that shelf will be important to watch.
J. M. Smucker is currently modeled to reach about US$9.1b in revenue and US$1.0b in earnings by 2029, with analysts assuming revenue stays broadly flat and profit expands mainly through margin improvement. That earnings path implies an increase of roughly US$770.5m from current earnings of US$229.5m.
Uncover why J. M. Smucker's fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on the risk that J. M. Smucker’s fresh shelf registration could precede equity issuance. The lowest analysts were already assuming revenue would ease to about US$8.7b by 2029 and earnings would reach roughly US$989.6m. That more cautious camp may view dilution risk differently. Consider this one perspective among several possible narratives.
Explore 2 other J. M. Smucker fair value estimates, including one that suggests it could be worth just $141.44.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your J. M. Smucker research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for J. M. Smucker. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate J. M. Smucker's overall financial health at a glance.
Looking For More J. M. Smucker Investment Ideas?
If J. M. Smucker has you thinking about where to put fresh capital to work, it can help to scan a broader watchlist built around the traits you care about most.
- For investors who want yield front and center, consider income opportunities highlighted through 7 dividend fortresses that may align with a dividend-focused approach.
- If capital resilience is your priority, review companies screened for stronger financial footing using the list of solid balance sheet and fundamentals (24 results).
- For those hunting for underfollowed potential, you can widen your search with the 16 high quality undiscovered gems and see which stocks match your criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com