
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Bureau Veritas (ENXTPA:BVI) On Temu Training Tie Up And Whether Undervalued Claims Hold
Temu’s latest move to expand seller education with partners such as Bureau Veritas (ENXTPA:BVI) puts fresh attention on the group’s role in global product testing, certification, and regulatory compliance.
Bureau Veritas shares trade at €26.76 after a short-term pullback, with the share price down 3.7% over the past month and 3% over the past week. However, the 1-year total shareholder return of 7.5% and 3-year total shareholder return of 26.8% suggest momentum over longer periods has been more supportive as partnerships like the Temu training initiative keep attention on its role in product safety and compliance services.
Scan for other Bureau Veritas style plays that may benefit from regulation and quality trends by checking our hand picked 229 resilient stocks with low risk scores featuring resilient balance sheets and lower risk profiles.
Bureau Veritas now trades around €26.76 after a soft patch, while partnerships like Temu’s keep its testing and certification role in view. Does that recent dip still offer a constructive entry once the valuation is unpacked?
Most Popular Narrative: 17% Undervalued
Bureau Veritas is framed as undervalued in the most followed narrative, with a fair value of €32.23 against the latest close at €26.76, putting the focus squarely on whether the current discount reflects execution risk or an opportunity in testing and certification.
The company's rapid expansion into high-growth areas such as sustainability and cybersecurity services positions it to capture outsized revenue gains and potential margin uplift as client demand for ESG reporting, supply chain audits, renewable energy projects, and cyber assurance intensifies globally.
Digitalization initiatives, including AI-powered inspection tools and modernization of operational systems, are expected to improve operational leverage and drive significant cost efficiencies, likely supporting higher net margins over the medium term.
See why 5 investors see Bureau Veritas as 17% undervalued.
Result: Fair Value of €32.23 (UNDERVALUED)
Still, currency swings and any stumble in Bureau Veritas’ acquisition integration or digital overhaul could quickly challenge the current undervalued narrative that investors are leaning on.
Find out about the key risks to this Bureau Veritas narrative.
Another View: Bureau Veritas Through The P/E Lens
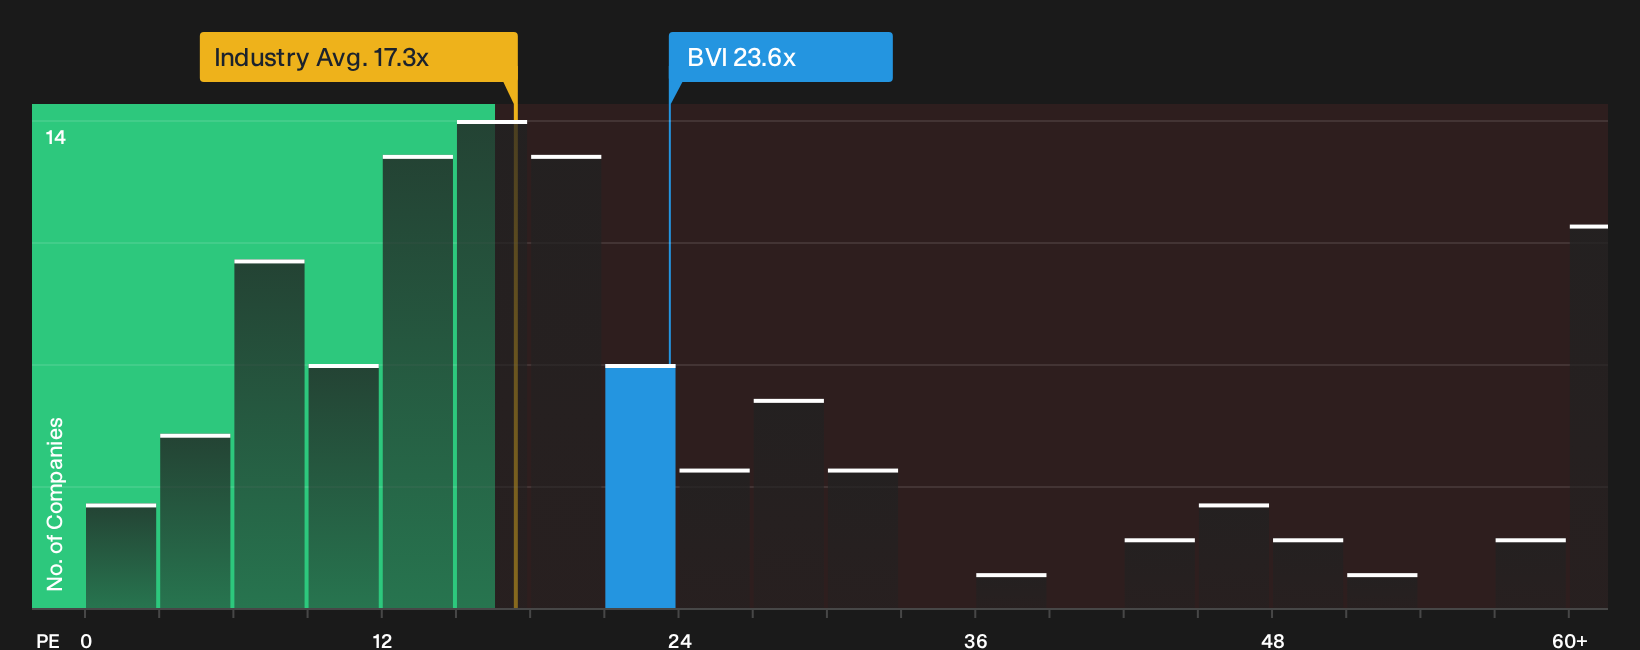
On a simple earnings multiple, Bureau Veritas looks less clear cut than the 17% discount to fair value suggests. The stock trades on a P/E of 23.6x, above the European Professional Services average of 17.6x and a fair ratio of 22.8x, which points to some valuation risk if sentiment cools.
To pressure test that, it helps to see what the numbers imply if the market leans toward that fair ratio rather than the current premium, and how much conviction you really have in Bureau Veritas’ earnings path relative to peers and sector norms See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Bureau Veritas so far in this piece. If you want to move quickly and decide where you stand, start with the 3 key rewards and 2 important warning signs.
Looking for more Bureau Veritas style investment ideas?
If you want to cast the net wider than Bureau Veritas and keep your watchlist working harder, the Simply Wall Street Screener can surface some focused ideas fast.
- Target potential mispricing by checking a curated set of quality companies trading below estimated worth through the 179 high quality undervalued stocks.
- Strengthen your income angle by reviewing the 159 dividend fortresses if you want yields that aim to balance payout with balance sheet resilience.
- Hunt for future leaders early by scanning the 619 high quality undiscovered gems before the market fully locks onto their fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com