
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Regional Bank Stocks Built For Higher For Longer Rates
Fed officials are again hinting that inflation is not cooling fast enough, which keeps the prospect of higher short term rates on the table for longer. That backdrop can quietly reshape which stocks benefit from cash-rich customers and repricing loans, and which ones feel the squeeze. This article walks through three regional banks from our screener that appear closely tied to this higher for longer story and explains why their exposure matters to you now.
The stocks covered below are only a small starter set from this higher for longer theme. The full screen surfaced 42 more regional and community banks with similarly compelling rate exposure stories that are not unpacked here. To go straight to the source, use the U.S. Regional and Community Banks Leveraging Higher-for-Longer Short-Term Rates screener to identify, filter, and analyze the banks that best match your own highest conviction thesis.
Metropolitan Bank Holding (MCB)
Metropolitan Bank Holding plugs directly into the higher for longer theme through its focus on commercial and real estate lending. Loan rates can reset more quickly than many deposit costs, which makes its funding mix and client base crucial to how rising short-term rates feed into earnings.
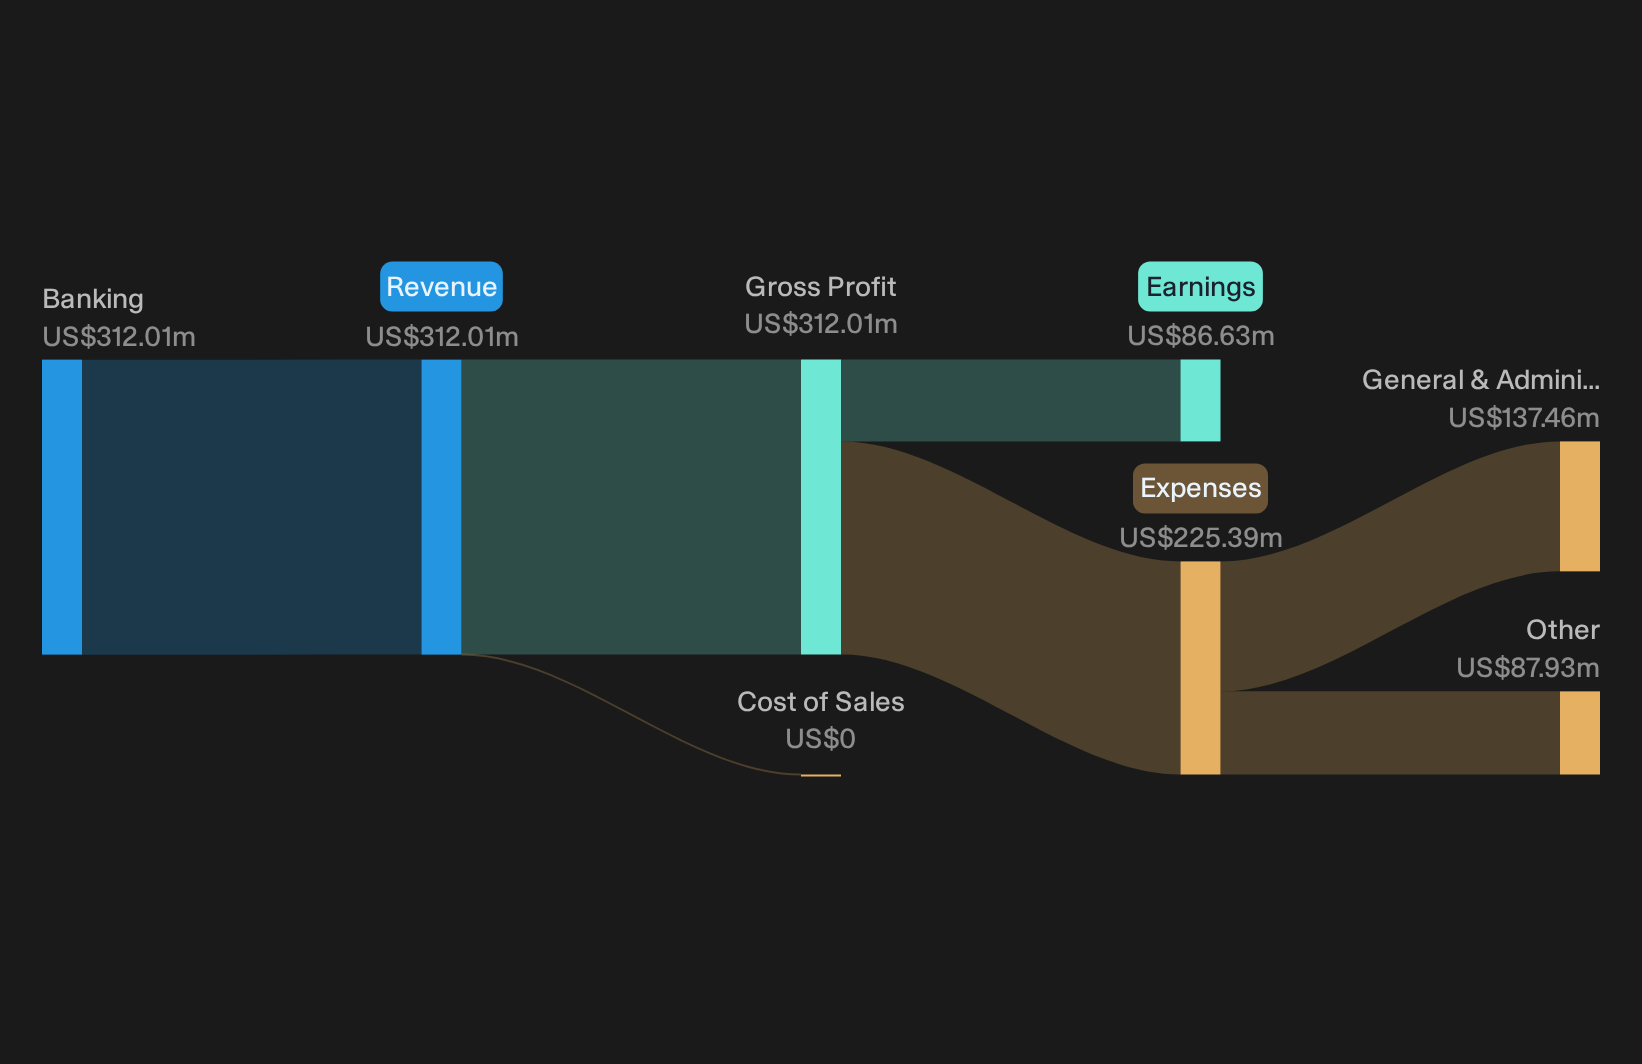
Metropolitan Bank Holding generates about $312 million from its banking operations in the United States, built around business, commercial, and retail clients, and currently carries a market value of roughly $1.1b.
"Continued core deposit growth across multiple specialized verticals, especially municipal, Title/1031, and EB-5, supports low-cost, stable funding and enables balance sheet expansion; this underpins further loan origination and net interest margin (NIM) growth, positively impacting earnings and profitability."
One key question is what happens if a quiet shift in that funding mix starts to change the balance between rising loan yields and the cost of deposits.
If that shift is what worries you, read the full narrative for Metropolitan Bank Holding to see how Metropolitan Bank Holding’s funding mix could be masking both risk and upside.
Southern First Bancshares (SFST)
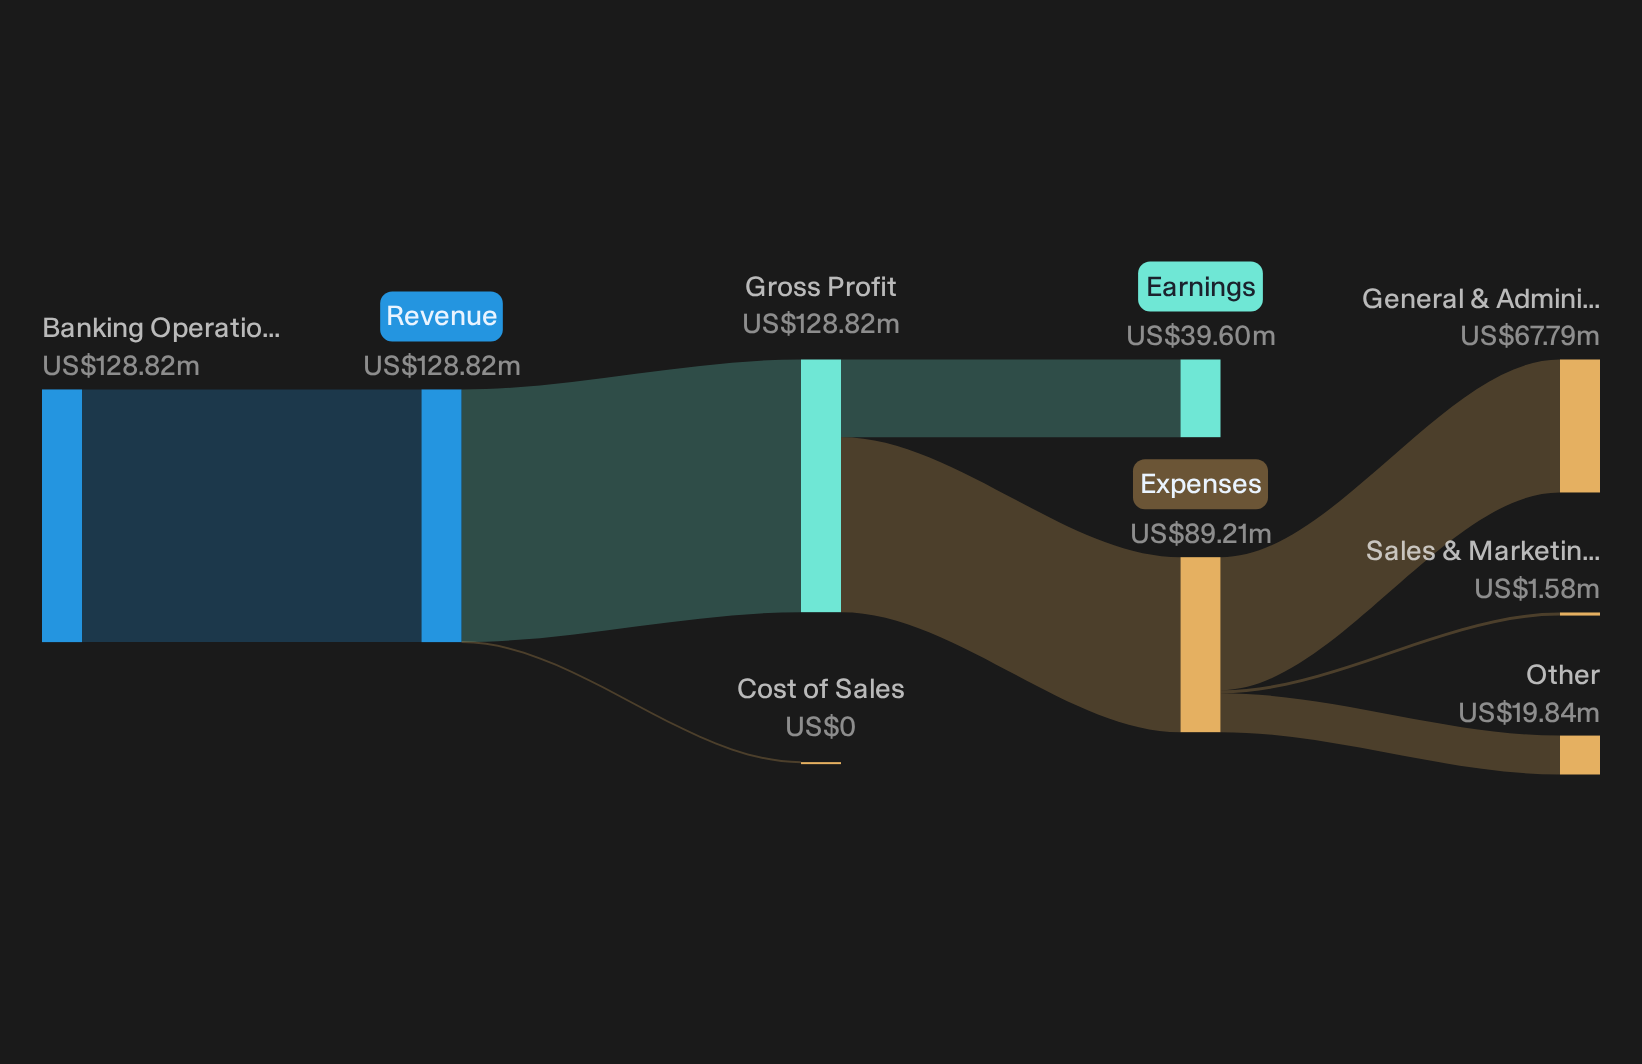
Southern First Bancshares runs a traditional local banking franchise across the Carolinas and Georgia, pairing community deposits with commercial, consumer, and mortgage lending that fits the higher for longer rate theme. It generates about $129 million from banking operations in the United States and carries a market value near $567 million.
Southern First Bancshares ties its earnings closely to short term rates through commercial and real estate lending funded by local deposits. This has supported rising net interest income and wider margins while credit losses remain light. The key question is what happens to that margin story if one unseen pressure on funding costs starts to build.
That unseen pressure is exactly what the 3 key rewards and 2 important warning signs is designed to highlight, showing how funding costs and margin potential really stack up for Southern First Bancshares.
Seacoast Banking Corporation of Florida (SBCF)
Seacoast Banking Corporation of Florida fits the higher for longer theme as a Florida lender built on local deposits and rate sensitive lending. This makes how it grows and funds that book central to your view on earnings power.
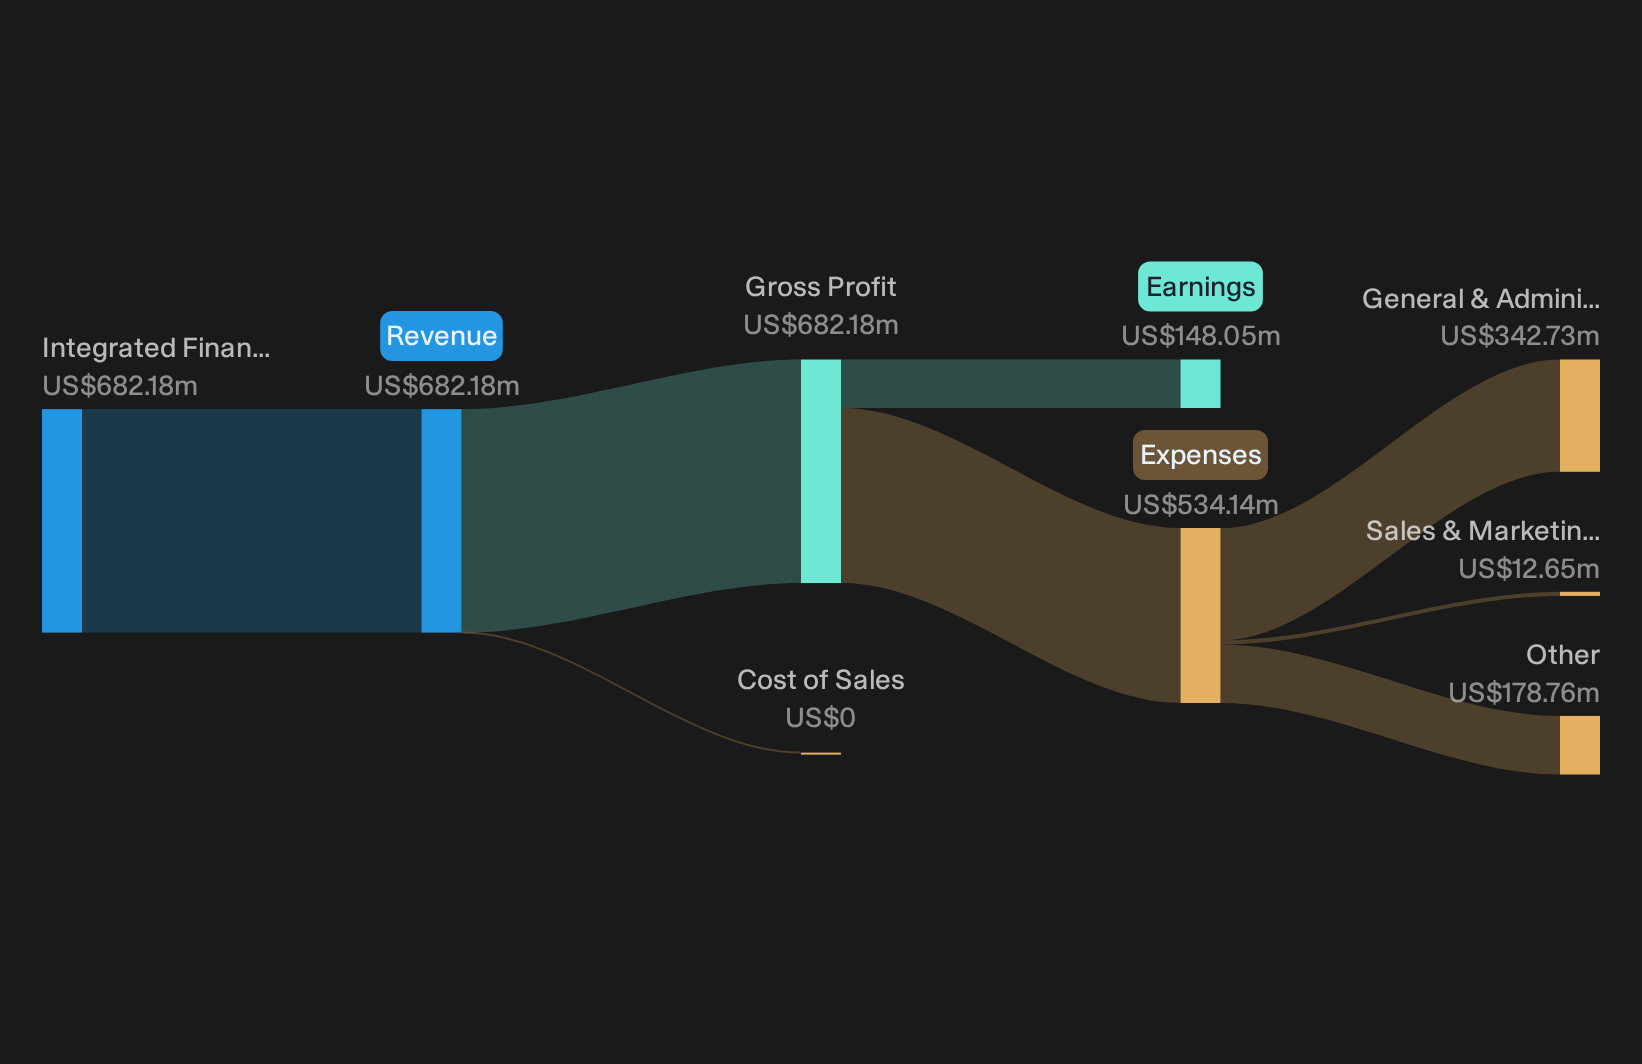
Seacoast Banking Corporation of Florida runs integrated financial services across Florida, generating about $682 million from a single banking segment in the United States and carrying a market value of roughly $3.1b.
"Seacoast is actively expanding its market share through disciplined, accretive acquisitions (Heartland Bancshares closed and Villages Bank Corporation pending), expected to provide high-quality, low-cost core deposits and complementary loan portfolios, significantly enhancing operational synergies, core net interest margin, and long-term earnings growth."
The real hinge for investors is what happens if one quiet shift in how those new deposits reprice starts to tug at future margins.
That quiet repricing risk is exactly why reading the full narrative for Seacoast Banking Corporation of Florida can help you see whether Seacoast Banking Corporation of Florida’s earnings story is accelerating or stalling.
Seeking Fresh Alternatives Before They Fly
New ideas move fast. Breakout stories build momentum while the best entry points quietly drop away. Scan curated stock shortlists before the crowd and act now.
- Target durable income streams by reviewing a curated group of higher yielding businesses through the 7 dividend fortresses before those payouts get fully priced in.
- Catch under the radar momentum by scanning the 16 high quality undiscovered gems that still trade off most investors’ screens while the story is fresh.
- Ride the next infrastructure wave by checking the 39 power grid technology and infrastructure stocks that connect directly to long term grid upgrades while this theme stays underbuilt into expectations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com