
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Test Data Software Tie Up At AeroVironment (AVAV) Has Changed Its Investment Story
- Nominal announced a collaboration with AeroVironment, bringing its test and operations data platform into AeroVironment's engineering and manufacturing workflows for uncrewed aircraft, loitering munitions, and counter-UAS systems.
- The move centralizes real-time test data, cross-team review, and traceability. This directly targets quality control and execution risk as AeroVironment scales hardware production.
- We will examine how AeroVironment's investment narrative intersects with Nominal's test data platform as production scale and complexity increase.
Scan beyond AeroVironment and find other hardware heavyweights solving the same scaling challenge by tracking 93 robotics and automation stocks now gaining traction with real-world robotics deployments.
AeroVironment Investment Narrative Recap
To own AeroVironment, you need to believe that demand for uncrewed systems, counter UAS and precision strike can support a complex mix of hardware, software and services while the company is still working toward consistent profitability. The big near term swing factor is execution on its production ramp and backlog without putting further pressure on already thin margins.
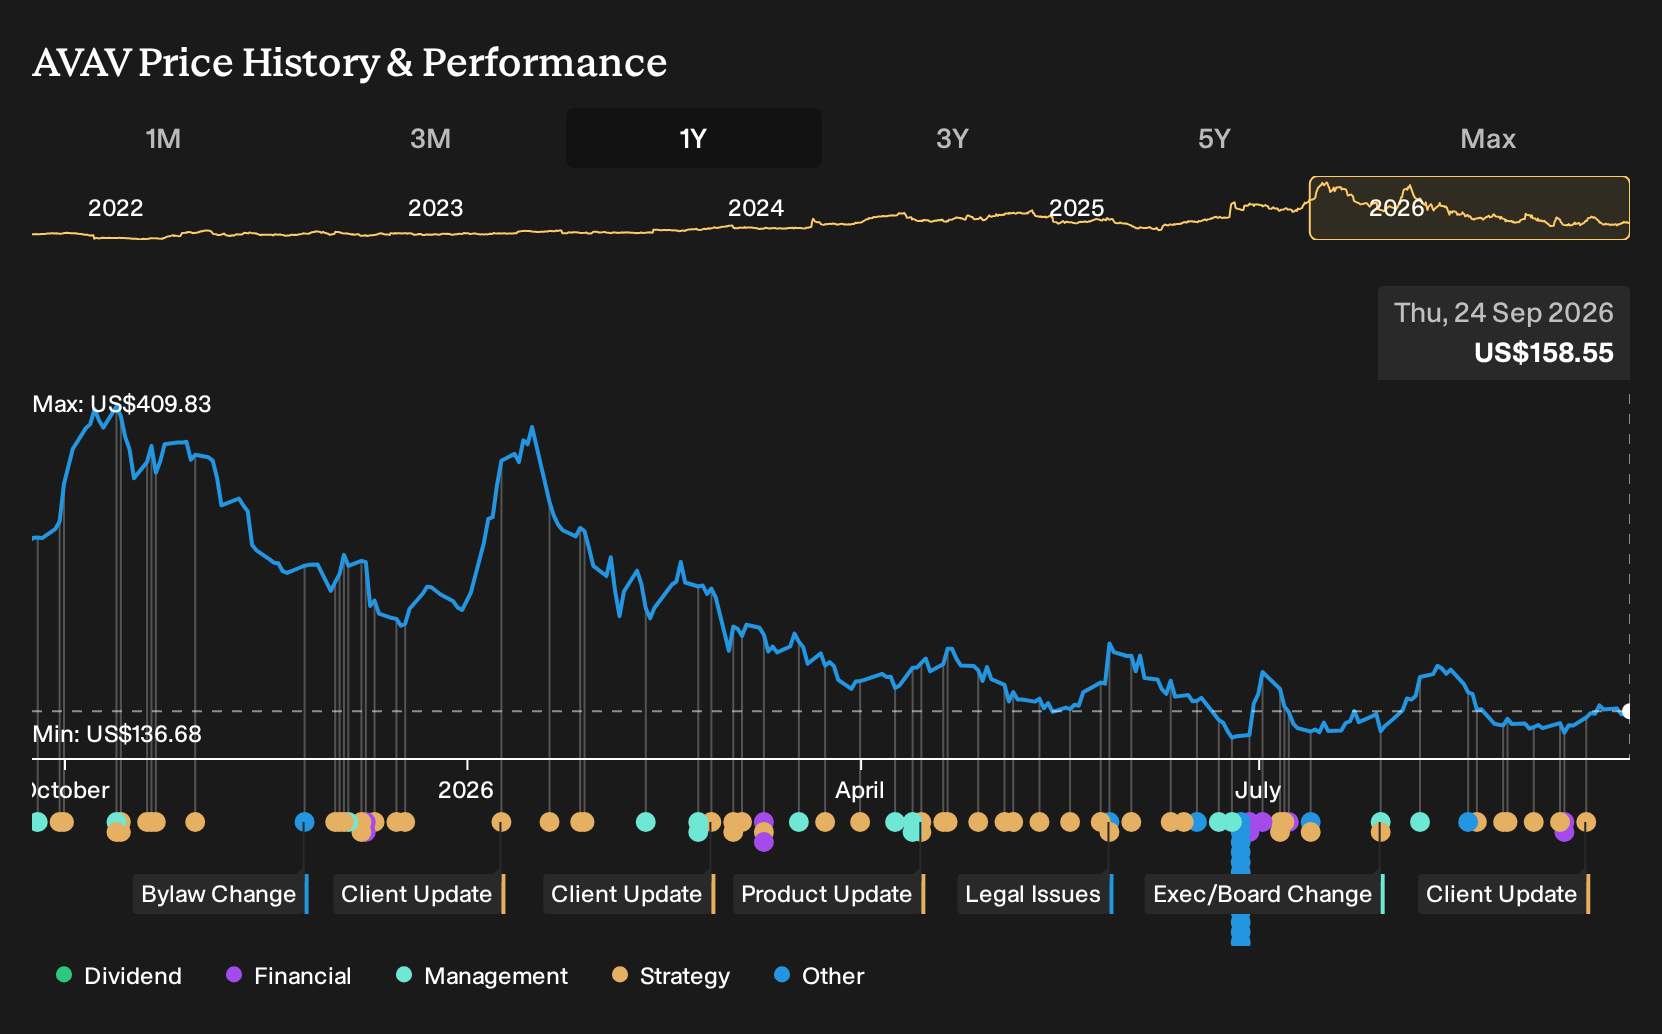
The largest risk right now sits in contract concentration and margin structure. Heavy U.S. government exposure, volatile recent share performance and a loss of US$202.8 million on US$2.0b of revenue leave little room for stumbles if budgets shift or integration and manufacturing costs stay elevated.
The Nominal partnership directly ties into AeroVironment's push to industrialize more hardware across uncrewed aircraft, loitering munitions and counter UAS programs. By tightening test data capture and traceability from R&D through end of line checks, the firm is trying to reduce quality escapes and execution risk as volumes and program count increase.
That matters because future catalysts, including larger multi year government contracts and the broader AV Halo software ecosystem, depend on reliable delivery at scale rather than just winning bids. If Nominal helps shorten feedback loops and supports smoother ramps across facilities, it may modestly support those operational goals, although on its own this announcement does not materially change the overall risk and reward profile.
AeroVironment Forecasts, Assumptions And Valuation Check
AeroVironment's story in the analyst models leans heavily on growth in both the top line and profitability over the next several years. The projections that sit behind those models set a clear hurdle that any production improvements from the Nominal partnership would need to support.
Analysts currently factor in revenue expanding at 14.3% per year over the next 3 years. Profitability is modeled to swing from a loss of US$265.1 million today to earnings of US$160.6 million by 2029, which implies an earnings shift of roughly US$425.7 million. Those same forecasts assume margins move from a loss of 13.4% to a positive 5.4% as the business matures and scales.
On the revenue side, the consensus view points to AeroVironment generating about US$3.0b of sales in 2029. That figure, paired with the US$160.6 million earnings line, underpins a projected P/E of 93.5x in that year if the stock tracks analyst expectations. Share count is also expected to rise, with estimates calling for 1.43% annual growth in the number of shares over the next 3 years, which slightly dilutes each investor's slice of those future earnings.
These valuation inputs matter because they set a high bar for what has to go right operationally. For an investor reading these numbers today, the question is less whether AeroVironment can grow, and more whether the production system, contract mix and cost structure, including data centric tools like Nominal's platform, can realistically support a shift to US$3.0b in revenue and triple digit P/E pricing on 2029 earnings.
AeroVironment's narrative projects US$3.0b revenue and US$160.6 million earnings by 2029. This requires 14.3% yearly revenue growth and an earnings increase of about US$425.7 million from a loss of US$265.1 million today.
Uncover why AeroVironment's fair value indicates a 42% potential upside to its current price before the discount closes.
Exploring Other Perspectives
One optimistic twist in the alternate AeroVironment story is international demand. The most upbeat analysts were already penciling in revenue of US$3.3b and earnings of US$283.6 million by 2029, well above the baseline. Those forecasts came before this Nominal collaboration, so you might see some opinions shift as you explore both narratives.
Explore 9 other AeroVironment fair value estimates, including one that suggests as much as 86% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AeroVironment research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AeroVironment. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AeroVironment's overall financial health at a glance.
Looking For More Investment Ideas Beyond AeroVironment?
If the AeroVironment story has you thinking about position sizing, risk and balance sheets, it can help to compare this stock with others that share similar qualities or offer a different profile altogether. The Simply Wall St Screener lets you filter the market using fundamentals so you can build a watchlist that actually fits your own approach.
- If capital protection sits high on your priority list, start with a group of 30 resilient stocks with low risk scores that score well on stability so you can focus on businesses with fewer red flags.
- For investors hunting for quality at a sensible entry point, look through a curated set of 30 high quality undervalued stocks that combine stronger fundamentals with more modest pricing.
- If you prefer durable income over potential share price swings, check out a focused pool of 7 dividend fortresses that pair higher yields with more resilient payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com