
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
YETI Holdings (YETI) Following 2026 Outlook Reaffirmation Still Trades Below Fair Value
YETI Holdings (YETI) reaffirmed its 2026 outlook, projecting sales growth of 7% to 8% for the fiscal year. That confirmation is drawing fresh attention to how the stock reflects the company’s current performance profile.
Recent trading has been choppy for YETI Holdings, with the share price slipping 18% over the past 90 days and 6.36% year to date, even as the 1 year total shareholder return of 23.21% suggests that longer term holders have still seen meaningful gains.
Compare YETI Holdings with a curated group of consumer brands that combine solid fundamentals with potential mispricing by scanning the 30 high quality undervalued stocks for your next idea.
YETI Holdings now trades well below both analyst targets and an estimated fair value, even after reaffirming its 2026 sales outlook. Is this a cautious market correctly pricing risk, or a discount worth unpacking next?
Most Popular Narrative: 22% Undervalued
YETI Holdings closed at $41.99 against a narrative fair value of $53.73. This frames the recent pullback as a valuation gap rather than a settled verdict on the business.
The company's accelerated international expansion, particularly robust growth and brand engagement in Europe and the rapid ramp-up in Japan and Asia, is unlocking a large revenue opportunity in underpenetrated markets, this is expected to drive sustained double-digit growth internationally and diversify global revenue streams.
See why 11 investors see YETI Holdings as 22% undervalued.
Result: Fair Value of $53.73 (UNDERVALUED)
Still, the narrative around YETI Holdings can crack if U.S. Drinkware weakness lingers or if competition forces heavier discounting that pressures margins and growth expectations.
Find out about the key risks to this YETI Holdings narrative.
Another View On YETI Holdings’ Valuation
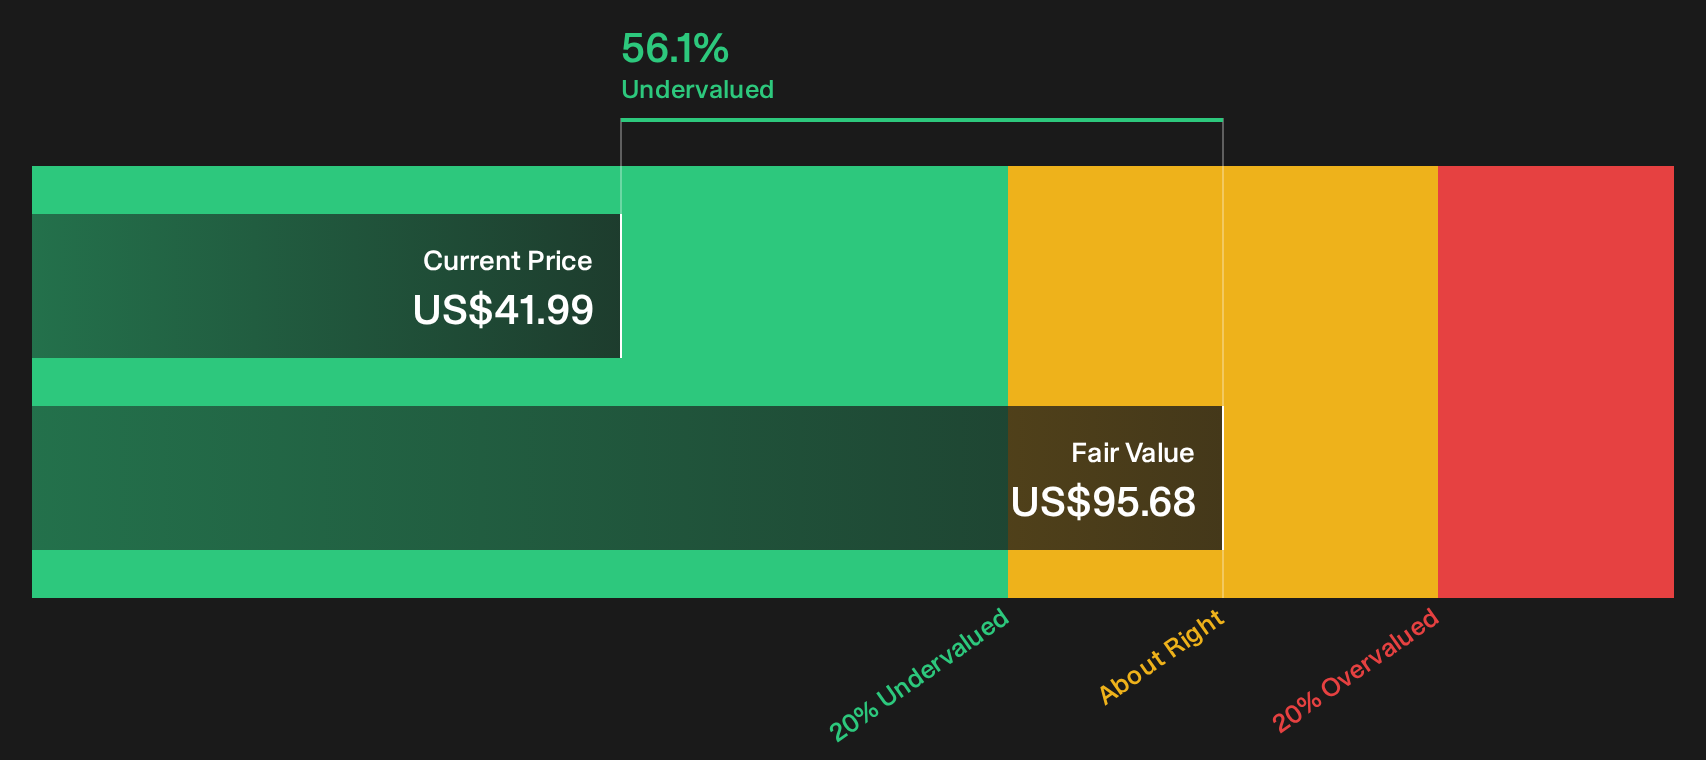
The DCF work presents YETI Holdings as deeply undervalued, with the SWS DCF model putting fair value at $95.68 versus a share price of $41.99. That is a 56.1% gap in favor of the model, which raises a simple question: Is the market missing something, or is the model assuming too much?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed sentiment around YETI Holdings is clear, so move quickly, look through the numbers yourself, and decide whether the rewards stack up in your view with 3 key rewards
Looking for more investment ideas beyond YETI Holdings?
If YETI Holdings has you rethinking where the next opportunity might come from, consider widening the lens with a few focused stock idea shortlists that spotlight different angles of the market.
- Target future potential by scanning 16 high quality undiscovered gems that many investors may not be watching yet.
- Prioritise stability and positions that may help you sleep better at night using a 30 resilient stocks with low risk scores that filters for resilience first.
- Hunt for financial strength by reviewing a list of solid balance sheet and fundamentals (24 results) that highlights companies with balance sheets built to handle stress.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com