
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Nebius Group (NBIS) Stock Looks Overvalued As Its 206% Run Draws Scrutiny
Nebius Group has been one of the more eye catching AI infrastructure stocks this year, with sharp swings following a powerful multi year climb. With the share price now reflecting big expectations, the open question for investors is whether that valuation is supported by Nebius Group’s sales.
- Over the past 5 years, Nebius Group has delivered a total return of 205.5%, which puts real weight on whether current revenue can justify such a strong performance.
- Management’s plan to deploy 5 GW of AI infrastructure capacity by 2030, alongside an estimated US$250b capex bill with about US$200b still to fund, can heavily influence how much of today’s market value is backed by existing sales versus future growth hopes.
- There is a second opinion on Nebius Group worth weighing. See what analysts think Nebius Group's shares could be worth.
The issue now is whether Nebius Group’s current share price is adequately explained by its sales when set against this ambitious investment plan and the recent return profile.
If you are weighing whether Nebius Group’s recent 5 year return of 205.5% is well supported by its sales, it can help to compare it with other AI infrastructure themes through 84 AI infrastructure stocks.
Does Nebius Group Look Pricey on Sales?
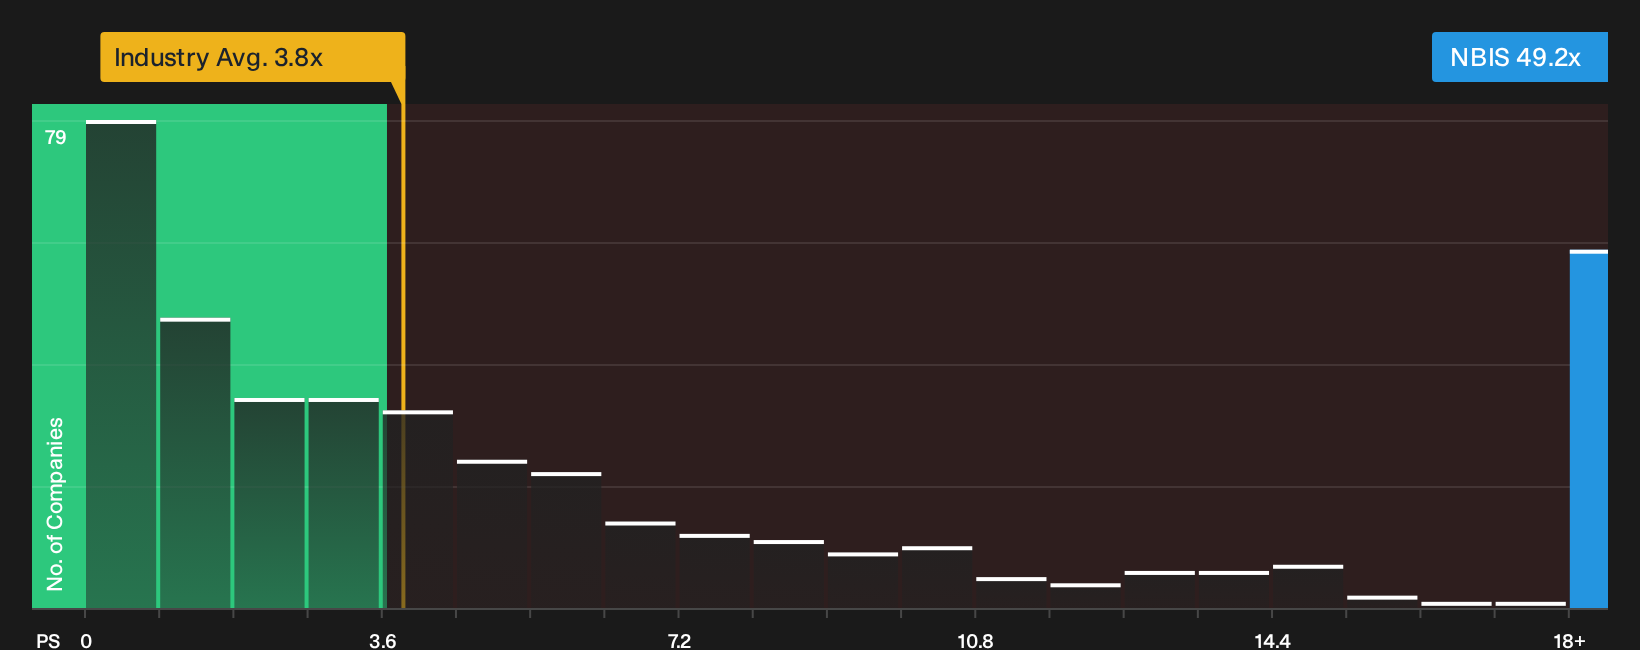
P/S is often the cleaner yardstick for Nebius Group because the business is leaning heavily on revenue growth while reporting very thin earnings. On this measure, the stock trades on a P/S of 49.2x, against a Software industry average of 3.8x and a peer group closer to 10.1x. That is a steep premium even by high growth software standards and it means each dollar of Nebius Group sales is being valued at many times the sector norm.
The Fair Ratio model, which tries to adjust for Nebius Group’s growth profile, margins, size and risk, still points to the current 49.2x sitting above what would typically be implied. Because the shares already carry such a rich sales multiple, the recent price slide of more than 20% from the peak and Michael Burry’s disclosed short position both land against a backdrop where expectations in the valuation remain very demanding. Explore the numbers behind Nebius Group's P/S valuation.
The Nebius Group Narrative: What Would Justify Today's Price?
Nebius Group’s Simply Wall St Narratives take the valuation puzzle above and turn it into specific future paths by spelling out what kind of growth, margins and earnings would need to show up for the stock to be worth materially more or less than today’s price on the Community page. Each scenario ties a fair value to a particular mix of potential catalysts and drawbacks so you can track over time which version of Nebius Group’s story is taking shape.
Community views on Nebius Group are split between an aggressive upside story and a more cautious read on how much risk is already priced in.
Bull case: 22% undervalued
"Nebius leverages rapid AI demand, global expansion, strategic partnerships, advanced technology, and strong funding to drive recurring revenue, margin growth, and long-term profitability…"
Discover why this Narrative puts Nebius Group at 22% undervalued.
Bear case: 66% overvalued
"Surging capital expenditures, as evidenced by the company's commitment to $2 billion in 2025 alone and a massive multi year plan to secure 1 gigawatt of power by 2026, will likely drive down free cash flow and pressure net margins for years…"
Explore why this Narrative puts Nebius Group at 66% overvalued.
One last Nebius Group check that belongs beside the headline valuation story
Price multiples only tell part of the story. Nebius Group also carries specific risk checks that could matter just as much as the sales premium you have been weighing. Take a closer look at 4 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com