
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Lincoln Electric Holdings (LECO) Draws Growth Interest, Is It Still A Bargain?
Lincoln Electric Holdings (LECO) is back in focus after research firm Zacks highlighted the welding specialist as a growth stock, citing its earnings outlook, efficiency metrics, and recent positive revisions to profit estimates.
Recent trading paints a mixed picture for Lincoln Electric Holdings. The share price has eased over the past month with a 30-day share price return of 4.91% in the red. However, the year-to-date share price return of 9.29% and a 1-year total shareholder return of 14.17% point to underlying momentum that aligns with growing interest in its earnings story.
Spot 16 high quality undiscovered gems that share Lincoln Electric Holdings' earnings momentum and efficiency profile before they move onto more investors' radars.Bulls point to Lincoln Electric Holdings’ earnings revisions and asset efficiency. Bears flag the recent share pullback and question how much is already reflected in the price. Which side does the current valuation support?
Most Popular Narrative: 13% Undervalued
Lincoln Electric Holdings closed at $266.40, while the most followed narrative anchors fair value at $304.91 using an 8.52% discount rate. This frames the recent pullback as a debate about how much of its automation and industrial story is already in the price.
Rising automation, reshoring trends, and infrastructure spending are set to boost demand for advanced welding solutions and drive sustained revenue and margin growth.
Focus on premium products, operational efficiency, and digital solutions supports long-term earnings expansion and strengthens stable, recurring revenue streams.
See why 5 investors see Lincoln Electric Holdings as 13% undervalued.
Result: Fair Value of $304.91 (UNDERVALUED)
Still, the bullish narrative for Lincoln Electric Holdings could be tested if pricing remains the main growth driver while automation demand or cyclical end markets stay sluggish.
Find out about the key risks to this Lincoln Electric Holdings narrative.
Another View on Lincoln Electric Holdings' Valuation
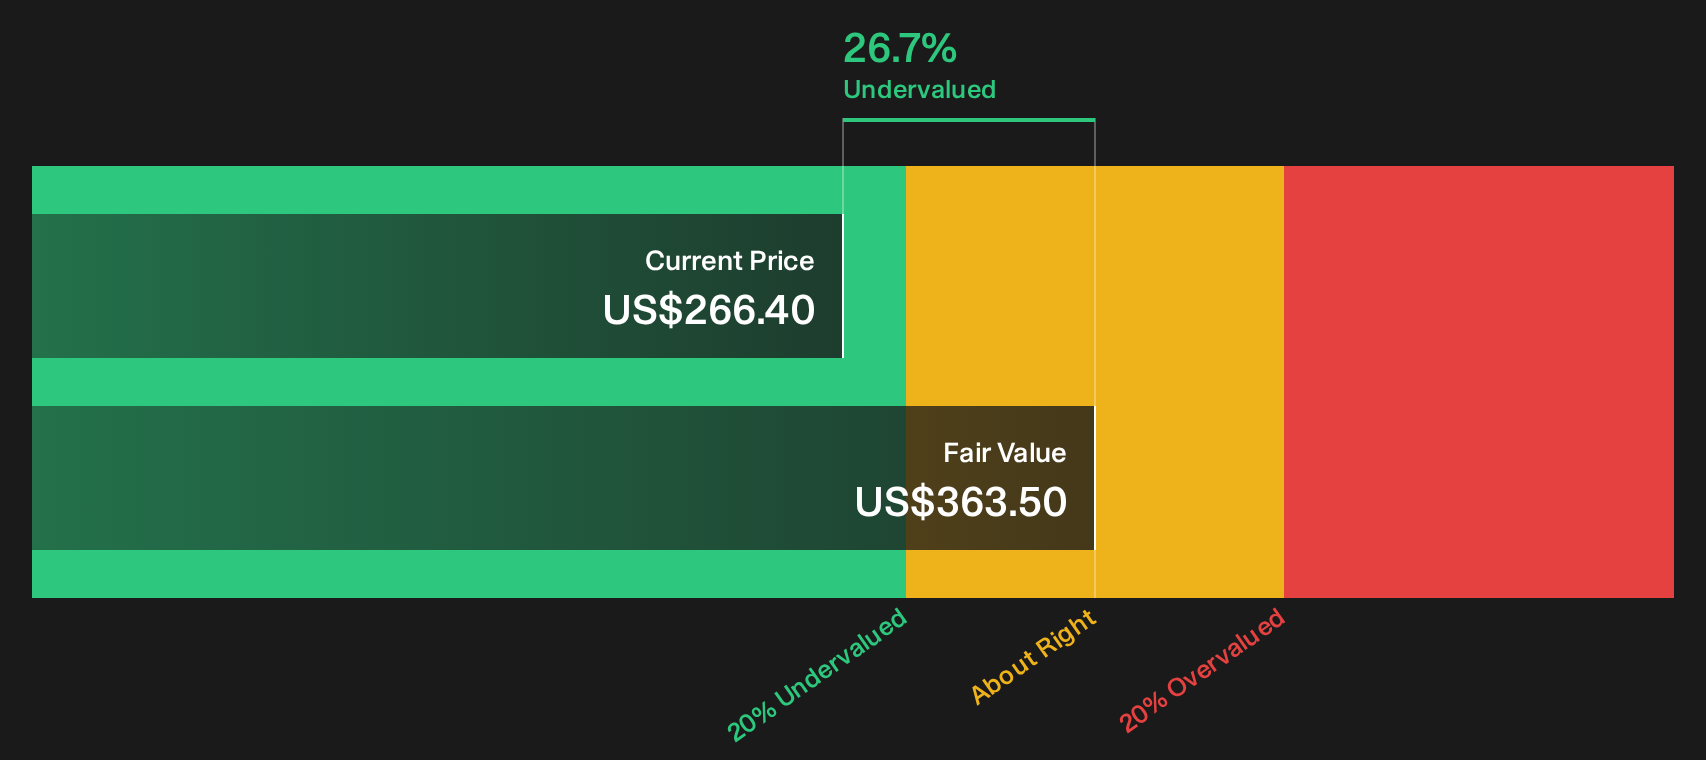
On earnings power, Lincoln Electric Holdings screens cheaply against the SWS DCF model, which estimates future cash flow value at $363.50 versus the current $266.40 share price. That implies an undervalued setup using cash flows even though analysts use a higher P/E than the fair ratio. Which lens do you trust more for your own assessment?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals or early opportunity: either way, the next move belongs to you. Move quickly, dig into the data, and weigh Lincoln Electric Holdings’ trade off between risks and potential upsides using the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Lincoln Electric Holdings?
If Lincoln Electric Holdings has you thinking harder about quality and price, do not stop here. Use the Simply Wall Street Screener to surface other focused opportunities before they move away from attractive levels.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (24 results) that filters for companies with financial strength at the core of their story.
- Hunt for mispriced quality through a 30 high quality undervalued stocks that highlights businesses where fundamentals and market expectations are out of sync.
- Prioritise sleep-at-night positions by using a 30 resilient stocks with low risk scores that focuses on companies with steadier risk profiles and fewer potential surprises.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com