
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
St. Joe (JOE) Expands Latitude Margaritaville, Is The Premium Valuation Still Justified?
St. Joe (JOE) has expanded its joint venture with Minto Communities USA, proceeding with a second phase at Latitude Margaritaville Watersound that targets roughly 3,500 additional homes and more resort-style amenities.
On the market side, St. Joe’s recent news comes after a mixed few months, with the share price down about 6.7% over 30 days but still up 8.5% year to date. The 1-year total shareholder return of 35% and 5-year total shareholder return of 61.6% indicate that momentum over longer periods has been stronger than the short-term pullback suggests.
Spot opportunities beyond St. Joe by scanning a curated 16 high quality undiscovered gems that highlights similar fundamentals and potential catalysts related to real estate and asset-backed growth stories.St. Joe now couples a long run of solid shareholder returns with a fresh capital commitment at Latitude Margaritaville Watersound. After the recent pullback, does that mix still tilt the risk reward toward buyers or toward patience, as valuation comes into focus?
Price-to-Earnings of 30x: Is St. Joe’s premium warranted?
St. Joe trades on a P/E of 30x, which is a clear premium to both the US Real Estate industry average and its closest peer group, so the recent pullback still leaves buyers paying up for each dollar of current earnings.
The P/E ratio compares the share price with earnings per share. For a real estate development and operating business like St. Joe, a higher multiple often reflects the market paying for quality of profits, perceived durability of cash flows, or expectations for future projects such as Latitude Margaritaville Watersound to contribute meaningfully over time.
Current fundamentals give that premium some context. JOE has high quality earnings and has grown profits by 48.7% over the past year, ahead of its 10.2% per year rate over the past 5 years, while net profit margins are reported at 22.5% compared with 19.4% a year earlier. Management and the board are described as seasoned and experienced, and the stock has outpaced both the US market and the broader US Real Estate sector over the past year.
The valuation gap to peers is still wide. JOE’s P/E of 30x is described as expensive versus the US Real Estate industry average of 15.5x and also high compared with the peer average of 25.9x. This means investors are paying materially more than sector and peer benchmarks for the company’s earnings stream.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 30x (OVERVALUED).
Still, St. Joe’s premium P/E leaves little room for disappointment if project timelines slip or if demand for new homes and hospitality assets cools.
Find out about the key risks to this St. Joe narrative.
Another View: SWS DCF model points in the opposite direction
The market treats St. Joe as a premium real estate stock on a 30x P/E. The SWS DCF model tells a very different story. At a share price of $64.88 versus an estimated future cash flow value of $158.27, the framework suggests the stock is deeply undervalued.
If the market eventually leans more on cash flow potential than current earnings multiples, this gap could close in a way that surprises both bulls and skeptics.
Look into how the SWS DCF model arrives at its fair value.
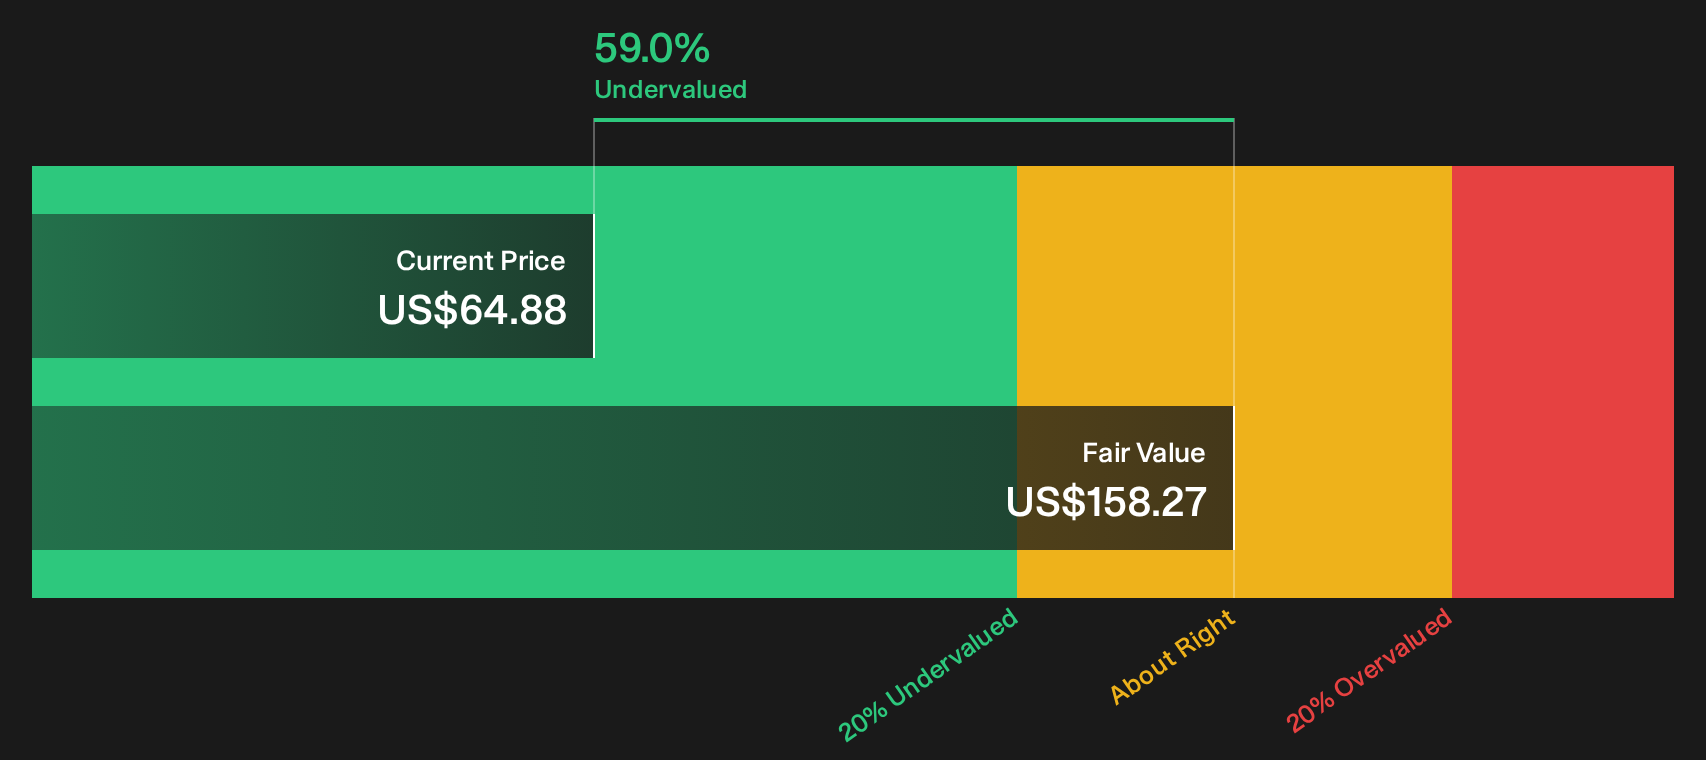
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out St. Joe for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around St. Joe looks split right now, so consider reviewing the data while it is current and pressure test both sides for yourself by checking the balance of 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond St. Joe?
You have already done the hard work by digging into St. Joe, so do not leave potential opportunities on the table when a broader set of filters is just as accessible.
- Target steady compounding by scanning a focused 30 resilient stocks with low risk scores that emphasizes resilience when markets shift.
- Hunt for value gaps by reviewing the 30 high quality undervalued stocks that pulls together quality businesses trading below their implied worth.
- Build a cash flow focused portfolio by tapping into a 7 dividend fortresses that highlights higher yielding payouts with support from underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com