
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hang Lung Properties (SEHK:101) Stock May Be Overvalued On Current Earnings
Hang Lung Properties has seen its share price under pressure in recent years, and the latest stretch has not reversed that story. With the stock now around HK$6.53, the key issue for investors is whether that price still matches what the company is earning.
- Over the past 5 years, Hang Lung Properties has delivered a share price decline of about 48.2%, which puts the focus squarely on whether its current earnings profile justifies where the stock trades today.
- The business relies heavily on recurring property income and rent collection, so any shift in occupancy, lease terms or operating costs can reshape how much of its revenue ultimately turns into sustainable profit.
- Your read on Hang Lung Properties is one view; the desks covering it have another. See what analysts think Hang Lung Properties's shares could be worth.
The issue now is whether Hang Lung Properties' current earnings support the valuation the market is placing on the stock.
If Hang Lung Properties' recent share price weakness has you reassessing your exposure, it can help to compare this situation with a focused list of other 179 high quality undervalued stocks.
Is Hang Lung Properties Getting Expensive on Earnings?
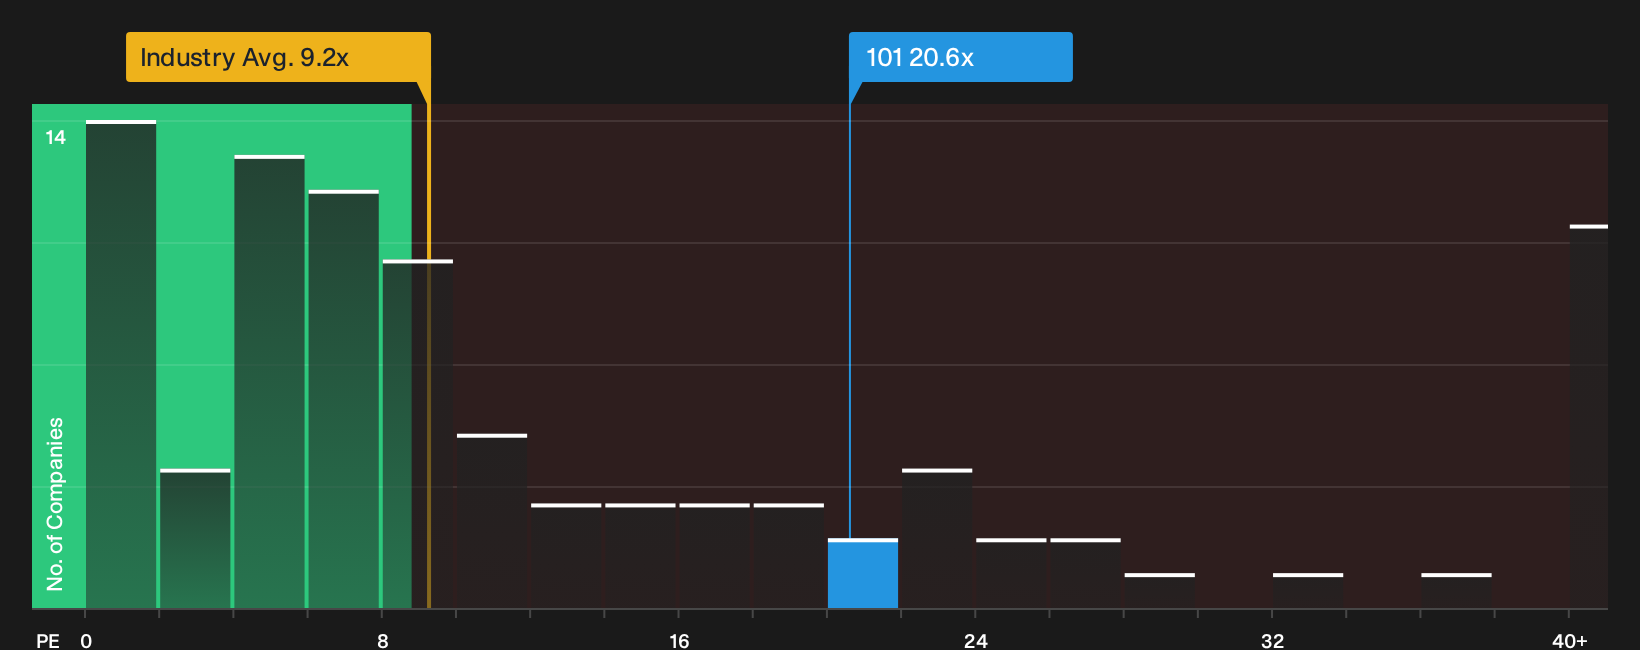
The P/E ratio is a useful way to think about Hang Lung Properties because earnings are central to how investors usually value property income streams. On this measure, the stock trades on a P/E of about 20.6x, which is more than double the broader real estate industry average of roughly 9.2x and also below a peer group average closer to 29.0x. That mix suggests the market is willing to pay a higher price than the typical property company for each Hong Kong dollar of Hang Lung Properties' recent earnings, while still not assigning it the highest multiple in its peer set.
A tailored valuation framework that takes account of Hang Lung Properties' size, profitability profile and risk points to a lower P/E than where the shares currently change hands. The current 20.6x level sits above that reference point, so on this earnings measure the stock screens as overvalued, even though it trades at a discount to the peer group average. Explore the numbers behind Hang Lung Properties's P/E valuation.
The Hang Lung Properties Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Hang Lung Properties are designed to turn that P/E puzzle into a set of clear earnings paths that would need to occur for the current share price to make sense as either too demanding or too cautious. Instead of stopping at a single output from a ratio or model, they set out the potential mix of growth, margins and profitability that the figure reflects, so you can follow how closely actual results align with those conditions over time on the Community page.
One of the top community narratives on Hang Lung Properties: 34% undervalued
"Portfolio repositioning and focus on experiential, lifestyle retail align with urban China's evolving consumer trends, driving margin improvement and rental growth..."
Discover why this Narrative puts Hang Lung Properties at 34% undervalued.
One more piece of the Hang Lung Properties puzzle
Before drawing your own line under Hang Lung Properties, it is worth knowing that our broader checks have flagged some specific concerns that many investors weigh carefully alongside valuation. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com