
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Greenfire Resources (GFR) Raised CA$775 Million, Is The Stock Still Undervalued?
Greenfire Resources (NYSE:GFR) has just raised about CA$775 million through a rights offering that added 114,985,163 common shares at CA$6.74, with proceeds aimed at paying down acquisition related bridge financing.
The rights issue comes after a strong run in Greenfire Resources' share price this year, with a year to date share price return of 28.48% and a 1 year total shareholder return of 27.69%. However, the 7 day share price return of 7.21% suggests some momentum has cooled as investors weigh dilution and financing risks against the long term integration of the Connacher assets.
Contrast Greenfire Resources' funding move with other producers by scanning a curated set of 36 elite gold producer stocks that are also reshaping their balance sheets and capital structures.
Greenfire Resources now appears to be a larger, better funded producer following the Connacher deal and rights issue. The open question is whether the current share price already reflects that stronger platform.
Preferred Price-to-Sales Multiple of 3.6x for Greenfire Resources: Is it justified?
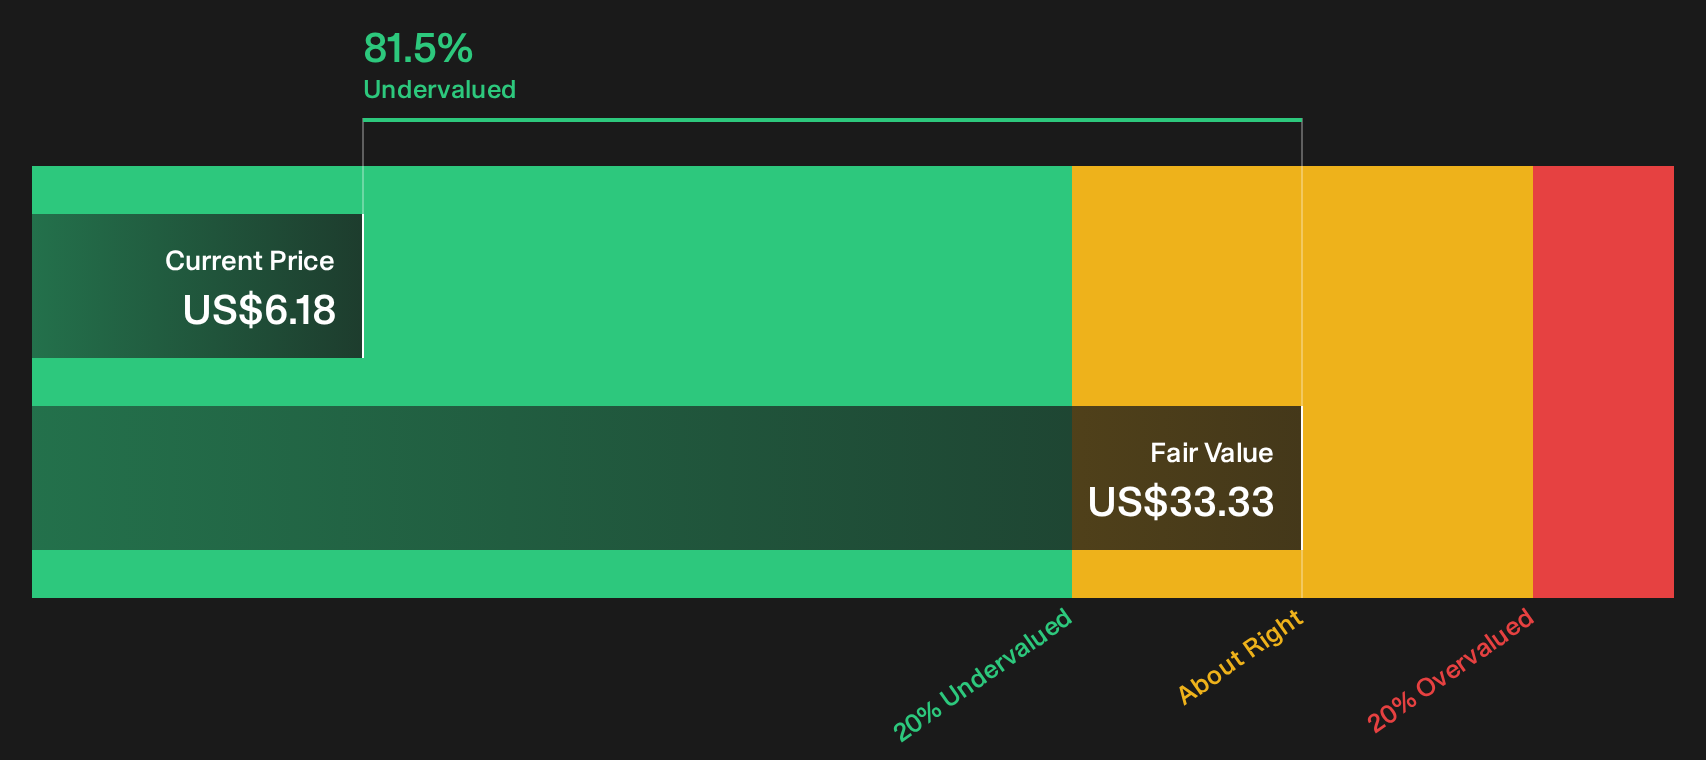
Greenfire Resources last closed at $6.18, while the SWS DCF model estimates a future cash flow value of $33.33 per share, which implies a large gap between the current market price and that modeled value.
The DCF framework projects Greenfire Resources' expected cash inflows over time and then discounts those future streams back to today using a required rate of return. That approach focuses on the cash the assets could generate rather than near term accounting metrics, which can be noisy for a business that is still loss making.
This kind of cash flow model is particularly relevant here because Greenfire Resources is currently unprofitable, reporting a loss of $36.93m on revenue of $581.47m. Revenue is forecast to grow 32.1% per year and earnings are expected to move into positive territory within three years. For an oil sands producer investing around acquired assets and handling higher risk funding through external borrowing, a DCF lens helps frame whether the rights issue and expansion are laying the groundwork for stronger long term cash generation that the share price has not yet fully absorbed.
Look into how the SWS DCF model arrives at its fair value.
Result: DCF Fair value of $33.33 (UNDERVALUED)
Still, Greenfire Resources faces real pressure points if oil sands prices weaken or if integration of the Connacher and Hangingstone assets proves more complex and costly than expected.
Find out about the key risks to this Greenfire Resources narrative.
Another View on Greenfire Resources’ Valuation
The SWS DCF model points to a fair value of $33.33 per share for Greenfire Resources, while the stock trades at $6.18. That is a very wide gap, yet it rests on long range cash flow forecasts and discount rate choices that can move a lot when oil sands economics or funding costs shift.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Greenfire Resources for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Greenfire Resources' valuation and recent funding moves can feel like noise. Move quickly and weigh the underlying data for yourself by reviewing the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Greenfire Resources?
Do not stop with Greenfire Resources. Use the Simply Wall Street screener to uncover fresh ideas that fit your risk level, income needs, and return goals.
- Target companies with strong financial footing by scanning a list of solid balance sheet and fundamentals (24 results) that can help you stress test your portfolio against tougher conditions.
- Hunt for quality at a reasonable price through the 30 high quality undervalued stocks and see which businesses trade at levels that may not fully reflect their fundamentals.
- Build a watchlist of potential future winners by reviewing a 16 high quality undiscovered gems that many investors might not be paying attention to yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com