
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
BlackBerry (TSX:BB) Wins Coretura Deal As Its Valuation Story Heats Up
Why BlackBerry Stock Is Back In Focus After The Coretura Win
BlackBerry (TSX:BB) is back on radar after Coretura, founded by Daimler Truck and Volvo Group, chose its Alloy Kore platform for next generation commercial vehicles, described as the largest design win in QNX history.
BlackBerry’s share price has moved sharply this year, with a 135.06% year to date share price return and a 1-year total shareholder return of 89.64%. This comes even after a 90-day share price return that is down 23.93%, suggesting that recent Alloy Kore and QNX headlines, together with stronger reported earnings in September 2026, are refreshing momentum after a pullback.
Scan beyond BlackBerry and see how other software driven, high-compute plays are setting up in our curated list of 84 AI infrastructure stocks.
So is BlackBerry’s sharp run mainly a catch up to improving QNX earnings and the Alloy Kore pipeline, or is sentiment running ahead of what the current numbers justify?
Most Popular Narrative: 24% Undervalued
On the most followed valuation narrative, BlackBerry is assessed with a fair value of CA$16.22 against the last close of CA$12.27. This frames the recent share price jump as only a partial catch up to that estimate.
The market is pricing BlackBerry as a maturing automotive software company. What it actually has is the safety infrastructure layer that physical AI cannot be commercially deployed without. The automotive royalty backlog took fifteen years to reach $950M. The physical AI backlog is starting from zero right now, in a faster-growing market, with the same royalty model and the same impossibility of removal once embedded.
See why 21 investors see BlackBerry as 24% undervalued.
Result: Fair Value of CA$16.22 (UNDERVALUED)
Still, the BlackBerry story can break if QNX design wins slow down or if physical AI royalties arrive later or smaller than this narrative assumes.
Find out about the key risks to this BlackBerry narrative.
Another View On BlackBerry’s Valuation
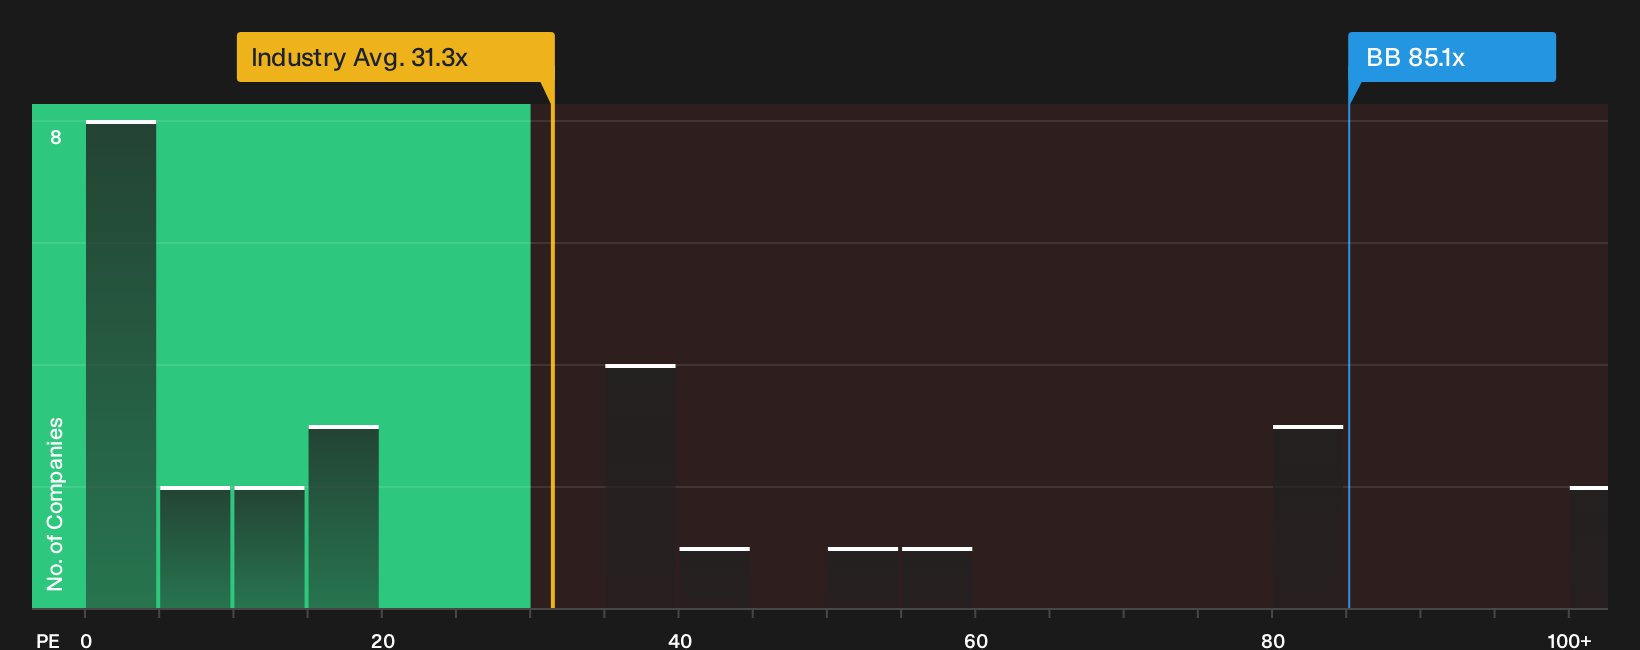
That fair value narrative paints BlackBerry as 24% undervalued at CA$16.22, yet the market is already paying a rich P/E. At roughly 85.1x earnings compared with 31.4x for the North American software group and a fair ratio of 31.8x, the stock carries clear multiple risk. So is this a mispriced opportunity or just expensive optimism?
For a closer look at what the current P/E gap could mean if the market drifts back toward that fair ratio and industry levels, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does the BlackBerry story feel more glass half full or half empty to you right now? Act quickly, check the data, and weigh both sides of the argument with the help of 2 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond BlackBerry?
Do not stop your research with BlackBerry. Broader context matters, and the right watchlist today can shape how you respond when the next setup appears.
- Target quality at a discount by scouting companies that look mispriced on fundamentals through the 5 high quality undervalued stocks.
- Prioritise resilience under pressure by reviewing a 8 resilient stocks with low risk scores that may offer more stable return profiles when sentiment swings.
- Hunt for future leaders early by scanning a 9 high quality undiscovered gems that combines strong financial traits with low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com