
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Protector Forsikring (OB:PROT) Could Be 26% Undervalued On OBX Index Removal
Protector Forsikring (OB:PROT) has been removed from the Oslo OBX Total Return Index, an adjustment that can shift demand as index-tracking funds rebalance and active investors reassess the stock’s role in portfolios.
Recent trading has been choppy for Protector Forsikring, with the share price down 11.4% over the past month and 17.1% year to date, while the one year total shareholder return has declined 6.8% but remains very strong over three and five years. Short term price weakness, including the 3.4% seven day share price decline ahead of removal from the Oslo OBX Total Return Index, points to fading momentum as some investors reassess risk and position sizes after several years of very large compounded gains for long term holders.
Spot under pressure like Protector Forsikring and scan for other insurers that combine solid fundamentals with potential valuation gaps using the 179 high quality undervalued stocks.Protector Forsikring has just been pushed out of a major index after a sharp pullback. Do you treat this as an early entry point, or wait for a deeper reset before committing fresh capital?
Most Popular Narrative: 26% Undervalued
Against a last close of NOK432, the most followed narrative for Protector Forsikring points to a fair value of NOK581.25, which frames recent price weakness as a valuation gap rather than a change in the long term story.
Protector Forsikring has a strategic focus on data and technology with specific targets for 2025, including the development and implementation of an AI tool to enhance employee productivity. This investment in technology is expected to improve operational efficiency and potentially reduce costs in the long term, positively impacting net margins.
See why 15 investors see Protector Forsikring as 26% undervalued.
Result: Fair Value of NOK581.25 (UNDERVALUED)
Still, Protector Forsikring’s story can change quickly if irrational pricing in Swedish motor lines persists or if higher reinsurance costs start to bite into margins.
Find out about the key risks to this Protector Forsikring narrative.
Another View On Protector Forsikring’s Valuation
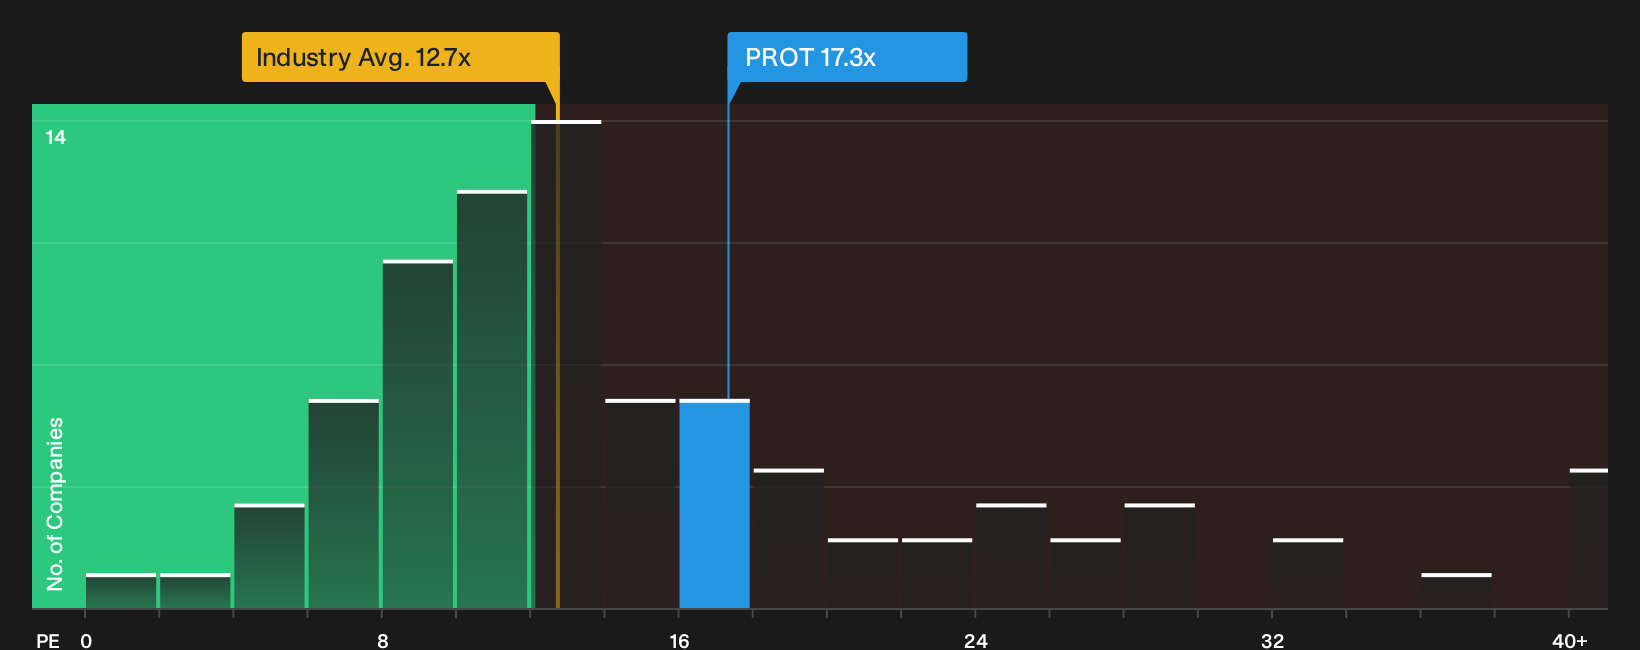
The earlier narrative leans on future earnings and a target fair value around NOK581.25. The current market price of NOK432 implies a P/E of 17.3x, which is higher than both the European insurance peer group at 16.9x and the broader industry at 12.8x, yet still below a fair ratio of 19.6x. That mix of premium pricing versus peers but discount versus the fair ratio leaves you asking whether the real risk sits in overpaying for quality or underestimating how long the market takes to close that gap.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Protector Forsikring is split, so move quickly from headlines to hard numbers and decide what feels justified for your own risk tolerance using the 3 key rewards.
Looking For More Investment Ideas Beyond Protector Forsikring?
If Protector Forsikring has you thinking harder about pricing, do not stop there. Use curated screeners to uncover other stocks that better fit your goals.
- Pinpoint potential mispriced opportunities by scanning a focused universe of high quality companies through the 179 high quality undervalued stocks.
- Strengthen your portfolio’s cash flow profile by targeting robust payers screened as 158 dividend fortresses.
- Dial down portfolio risk by prioritizing resilient businesses filtered via the 229 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com