
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Defensive Dividend Stocks With Strong Balance Sheets for Higher Rates
Bond yields near 5.18%, mortgage rates around 7%, and stubborn inflation worries have pushed many investors toward the sidelines, yet this same backdrop can quietly reset the playing field for dividend value stocks with solid balance sheets. If you care about getting paid while you wait and prefer businesses that do not rely heavily on cheap debt, this screener matters. This article walks through three stocks exposed to these rate and inflation shocks, and explains how their quality signals may appeal to patient dividend seekers.
The three stocks covered below are just a starting sample from this idea. The full screen surfaced 19 more companies with equally detailed dividend and balance sheet stories not covered here. To see the wider field, head straight into the High-Quality Dividend Value Stocks screener to identify, analyze, and prioritize your own highest conviction dividend value candidates.
Conagra Brands (CAG)
Overview: Conagra Brands is a US-based packaged foods group that sells branded frozen, refrigerated, and shelf-stable products to retail and foodservice customers.
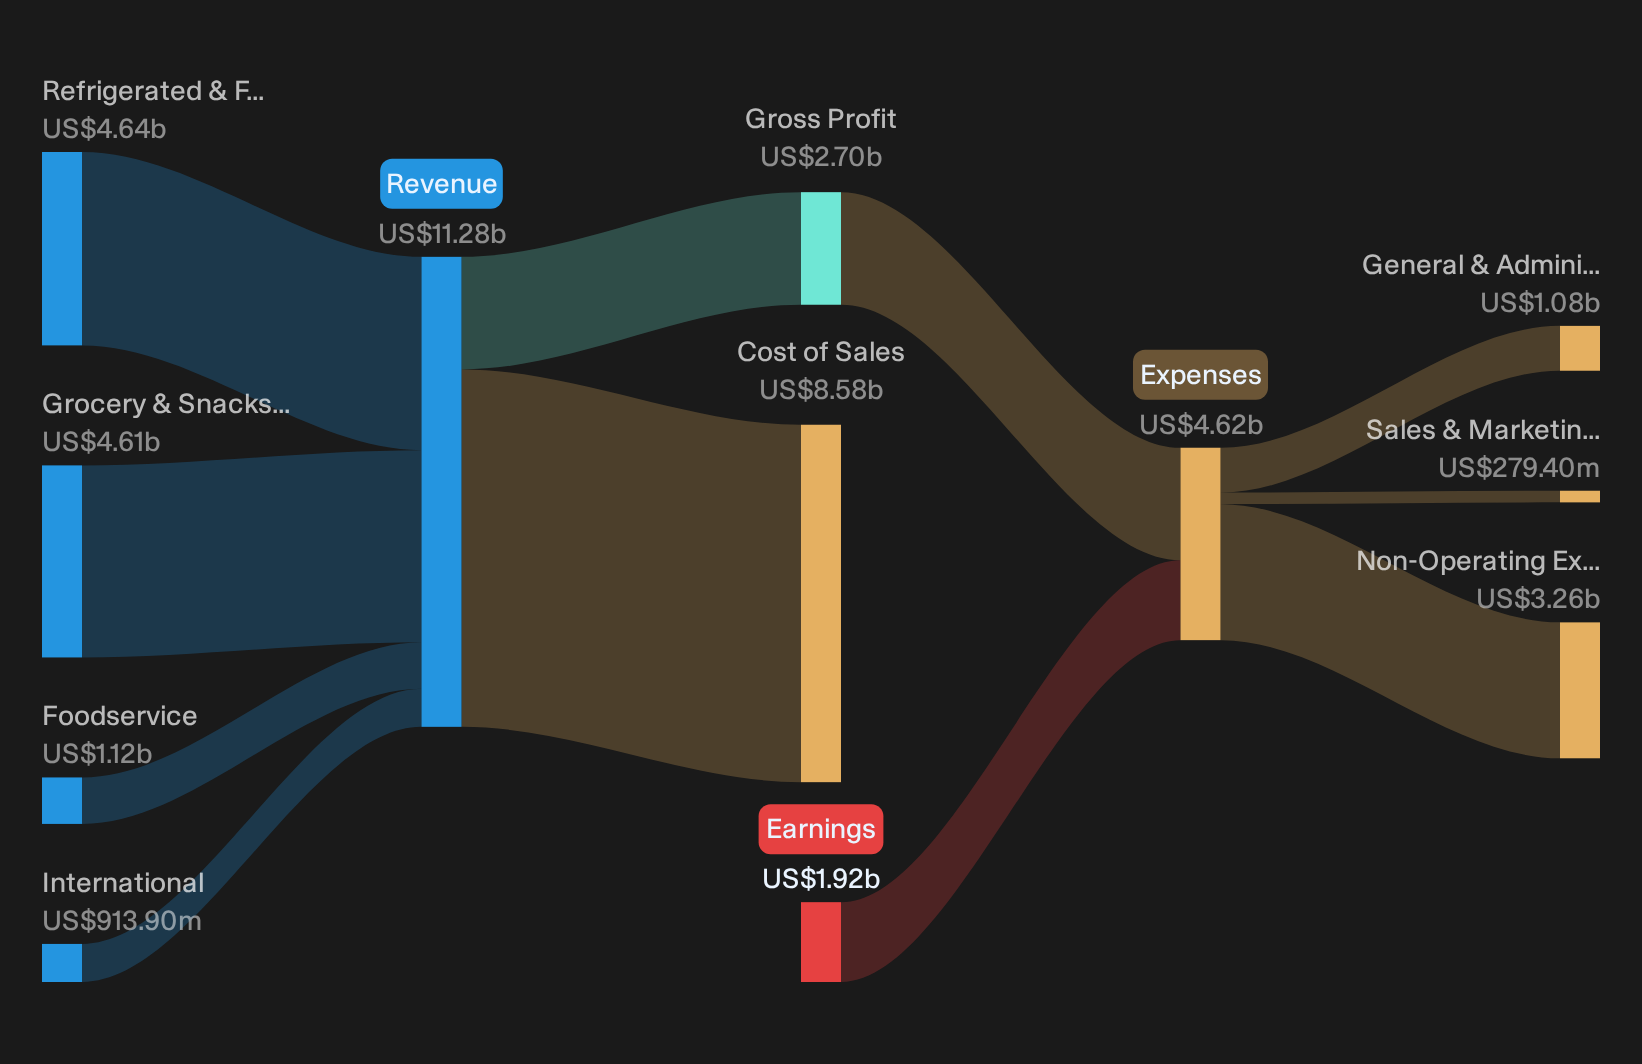
Operations: Conagra generates about US$4.6b from Refrigerated & Frozen and US$4.6b from Grocery & Snacks, with most of its roughly US$11.3b sales in the United States.
Market Cap: US$7.1b
Conagra Brands fits this high-quality dividend value screen because it combines a large packaged foods footprint with a clear income profile and a plan to keep shoring up its balance sheet as rates stay higher for longer.
"Project Catalyst, which applies new process and technology including AI to simplify work and reduce working capital, is being funded today with most financial benefits expected from fiscal 2028 onward."
What happens to Conagra Brands’ margin rebuild and dividend headroom depends on how one unresolved cost and pricing pressure ultimately plays out.
That hinge point on costs and pricing is exactly what the full narrative for Conagra Brands unpacks in detail, showing where Conagra Brands could be accelerating or stalling from this point forward.
Ameren (AEE)
Overview: Ameren is a large US utility that supplies regulated electricity and natural gas to homes, businesses, and data centers, fitting the screener's focus on dividend payers in lower risk industries.
Operations: Ameren Missouri generates US$4.6b of revenue, Ameren Illinois Electric Distribution US$2.5b, and Ameren Illinois Natural Gas US$1.0b, almost entirely in the United States.
Market Cap: US$27.6b
Ameren matters here because it offers regulated cash flows, a visible dividend record, and a balance sheet built for higher rates. This sets up the context for how its newest growth engine could affect long term income potential.
"Rapid growth in large data center and hyperscaler demand in Ameren Missouri's territory, reflected in 2.8 gigawatts of signed electric service agreements, 3.4 gigawatts of construction agreements and a further 4 gigawatts of projects with completed interconnection studies, is expected to translate into higher electricity sales and a larger regulated revenue base as contracted load ramps through 2029 and beyond, supporting earnings."
What this ultimately means for Ameren's dividend headroom and valuation appeal will turn on how one key financing pressure is resolved.
That funding question is exactly what the full narrative for Ameren tackles. It maps how Ameren’s data center load, capital plan, and dividend ambitions could be decoupling from headline rate worries.

NiSource (NI)
Overview: NiSource is a regulated US utility that supplies natural gas and electricity to customers across multiple Midwest and Mid-Atlantic states.
Operations: NiSource generates about US$3.5b from NIPSCO Operations and US$3.4b from Columbia Operations, with total US revenue of roughly US$6.9b.
Market Cap: US$18.8b
NiSource fits this high-quality dividend value screen because it combines large regulated gas and power networks with a visible income profile that does not rely on fast growth to matter in a higher for longer rate world.
"Accelerating demand for electricity from data centers, industrial expansions, and urbanization in NiSource's service territories is now paired with about 4 gigawatts of signed data center capacity and a pipeline of roughly 5 additional gigawatts under discussion, which can expand long term electric revenue and earnings as these loads energize."
What investors ultimately get from NiSource’s dividend and earnings story hinges on how one long term regulatory and funding pressure resolves.
That hinge on regulation and funding is exactly where the full narrative for NiSource pulls you in, highlighting how accelerating data center load could reshape NiSource’s risk reward profile.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities rarely stay under the radar for long. Once momentum builds, ideal entry points get caught and start dropping away. Scan these curated ideas now and get in early.
- Target reliable income potential by touring a curated mix of high-yield payers in the 7 dividend fortresses before the best ex dividend setups are gone.
- Chase structural growth by reviewing hand picked infrastructure players in the 84 AI infrastructure stocks while the build out story still sits under the radar for now.
- Hunt resilient compounding potential through a curated 31 resilient stocks with low risk scores before crowd attention drives more investors into the same low volatility corner.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com