
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Multi Cloud Threat Hunting Altering The Investment Case For SentinelOne (S)?
- SentinelOne recently expanded its Wayfinder Threat Hunting service to cover AWS, Azure, and Google Cloud, combining Singularity Platform telemetry with expert-led hunting across endpoints, identities, and cloud control planes for existing Wayfinder customers.
- The move ties SentinelOne’s AI-powered detection with Google Threat Intelligence in a single workflow, with the goal of reducing operational overhead by centralising continuous threat hunting on multi-cloud infrastructure and identity systems.
- We will now see how SentinelOne's broader multi cloud threat hunting capability could influence its investment narrative and platform appeal.
Scan how SentinelOne’s cloud security push fits into a wider AI security trend by reviewing a curated set of 84 AI infrastructure stocks.
SentinelOne Investment Narrative Recap
To be comfortable owning SentinelOne, you need to believe that its AI driven Singularity platform can keep winning budget as security buyers consolidate tools and lean into automation, even while the business remains loss making. The cloud Wayfinder expansion supports that broader platform story, but on its own it does not change the near term path to profitability or cash discipline.
The most important short term catalyst still sits in execution on multi product adoption, Flex licensing uptake, and converting partnerships with hyperscalers into predictable, larger contracts. The biggest risk remains margin pressure from heavy R&D and services investment, especially if deal timing stays choppy or competitors lean harder on pricing.
The Wayfinder Threat Hunting expansion matters most when viewed alongside SentinelOne Flex licensing, which is designed to encourage customers to standardise on more of the platform. Cloud wide hunting across AWS, Azure and GCP can make it easier for large clients to justify broader adoption under a flexible contract that already rewards bundling.
For you as an investor, the interesting question is whether these types of offerings meaningfully lift average contract value fast enough to offset the cost of expert led services and ongoing AI development. That balance between platform breadth, partner reliance and the effort to reach profitability still defines the risk reward profile from here.
SentinelOne's narrative projects US$1.8b revenue and US$213.5 million earnings by 2029. This projection is based on an assumed 18.3% yearly revenue increase and an earnings change of about US$553.6 million, moving from the current earnings of a US$340.1 million loss to the forecast US$213.5 million profit.
Uncover why SentinelOne's fair value is essentially aligned with its current price.
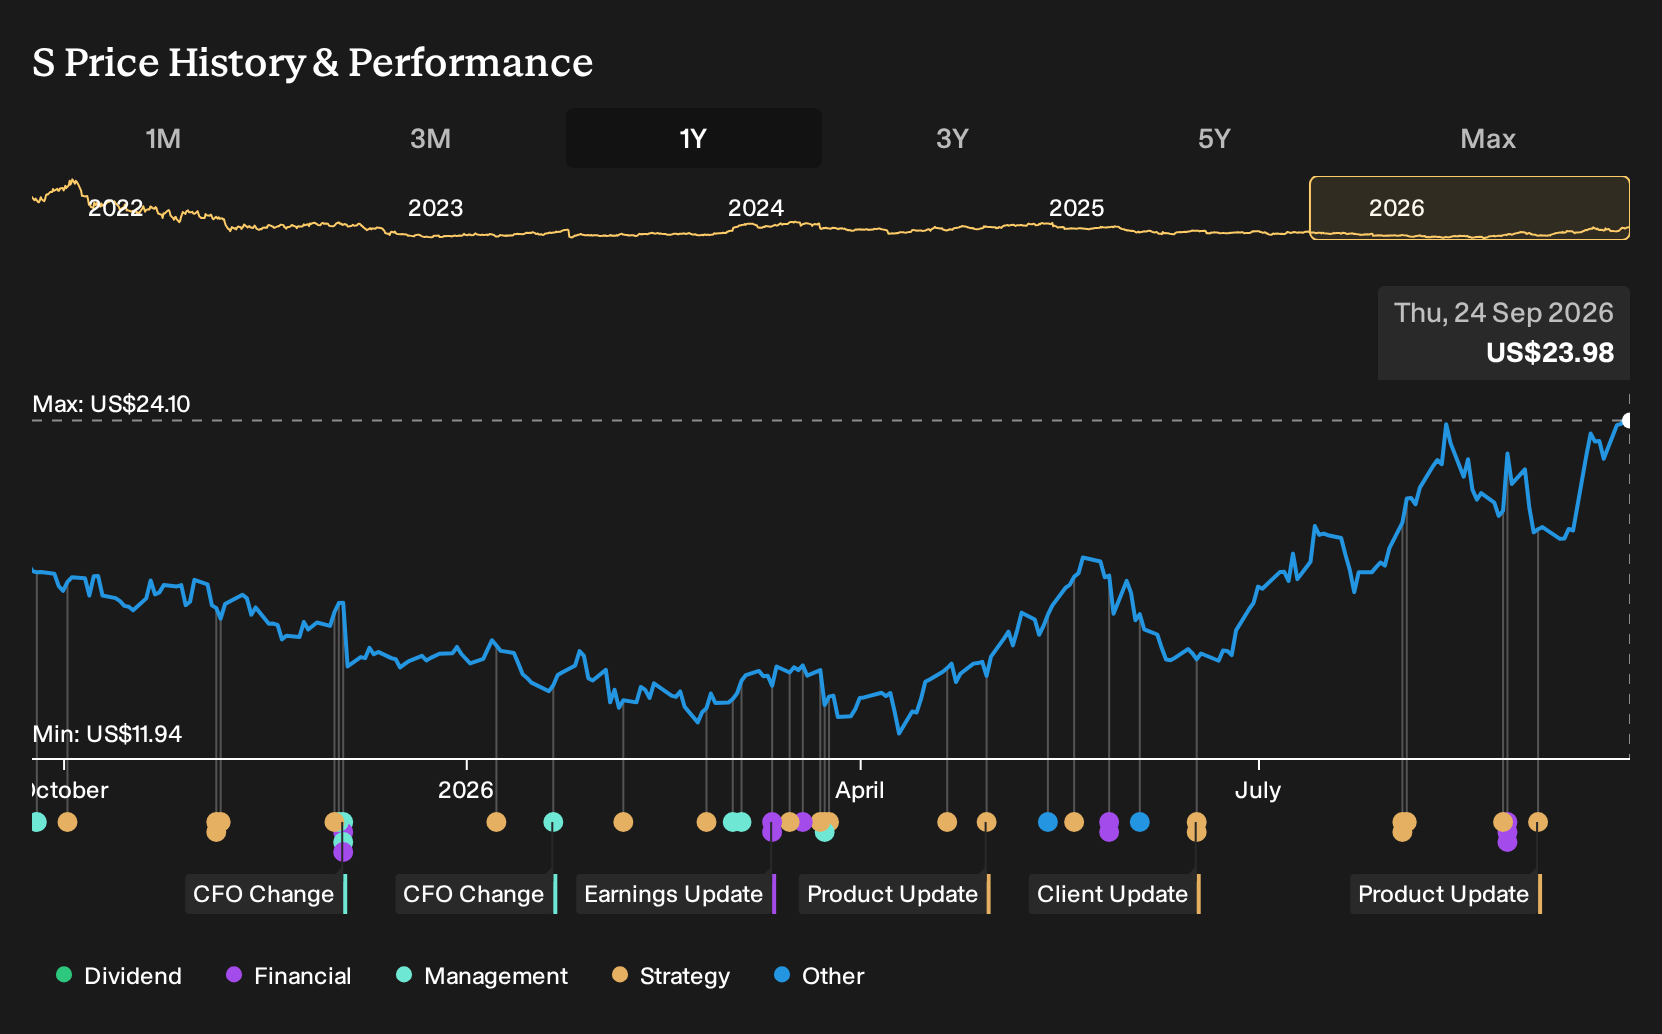
Exploring Other Perspectives
One bullish twist on the SentinelOne story focuses on how fast unified AI security could re-rate the business if it gains real traction. The most optimistic analysts were already modeling revenue reaching about US$1.8b and earnings of roughly US$215.0 million by 2029. Fresh multi cloud hunting news like this could change those expectations, so it makes sense for you to compare several viewpoints before deciding what feels reasonable.
Explore 3 other SentinelOne fair value estimates, including one that suggests up to 14% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SentinelOne research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for SentinelOne. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SentinelOne's overall financial health at a glance.
Looking For More Ideas Beyond SentinelOne?
Once you have a view on SentinelOne, it can help to widen the lens and compare it with other opportunities that match your preferences for risk, quality, and income. The Simply Wall St Screener lets you filter the market in a targeted way so you can build a watchlist that fits how you like to invest.
- If you want potential mispricing with quality in mind, check out a curated set of 30 high quality undervalued stocks that may merit a closer look.
- For investors who care more about resilience and capital preservation, scan a focused group of 31 resilient stocks with low risk scores that score well on stability metrics.
- If you are hunting for future leaders before they break into the spotlight, review a hand picked collection of 16 high quality undiscovered gems with strong underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com