
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Bright Horizons Family Solutions (BFAM) Faces A Valuation Test After Morgan Stanley Flags Child Care Strains
Morgan Stanley’s recent work on the child care sector puts Bright Horizons Family Solutions (BFAM) in focus, highlighting how affordability pressures and limited slot availability are constraining enrollment growth despite strong demand from families.
For investors watching Bright Horizons Family Solutions, the recent Morgan Stanley commentary comes after a tough run for the stock. The share price is down 10.22% over the past month, and the year-to-date share price return has declined 33.19% to US$66.34.
Scan beyond Bright Horizons Family Solutions to see how other childcare and consumer services operators are priced and growing in our hand picked list of 30 high quality undervalued stocks.
Bears point to the long slide in Bright Horizons Family Solutions’ share price. Bulls lean on solid revenue and earnings growth. Which story does the current valuation actually support next?
Most Popular Narrative: 26% Undervalued
On the most followed view of Bright Horizons Family Solutions, the narrative fair value of $89.44 sits well above the last close of $66.34. This puts the current share price squarely against a story that leans on back up care strength, portfolio cleanup and richer free cash flow.
The expansion of employer-sponsored childcare and growing demand from large corporate clients is now supported by multi-year evidence of companies adding back-up care and educational advisory on top of full-service childcare. This can deepen Bright Horizons Family Solutions client relationships and support higher recurring revenue and earnings over time.
See why 1 investors see Bright Horizons Family Solutions as 26% undervalued.
Result: Fair Value of $89.44 (UNDERVALUED)
Still, the story around Bright Horizons Family Solutions can fray if full-service enrollment stays sluggish or if Australian losses near US$20 million to US$25 million persist longer than expected.
Find out about the key risks to this Bright Horizons Family Solutions narrative.
Another View: Bright Horizons Family Solutions On P/E
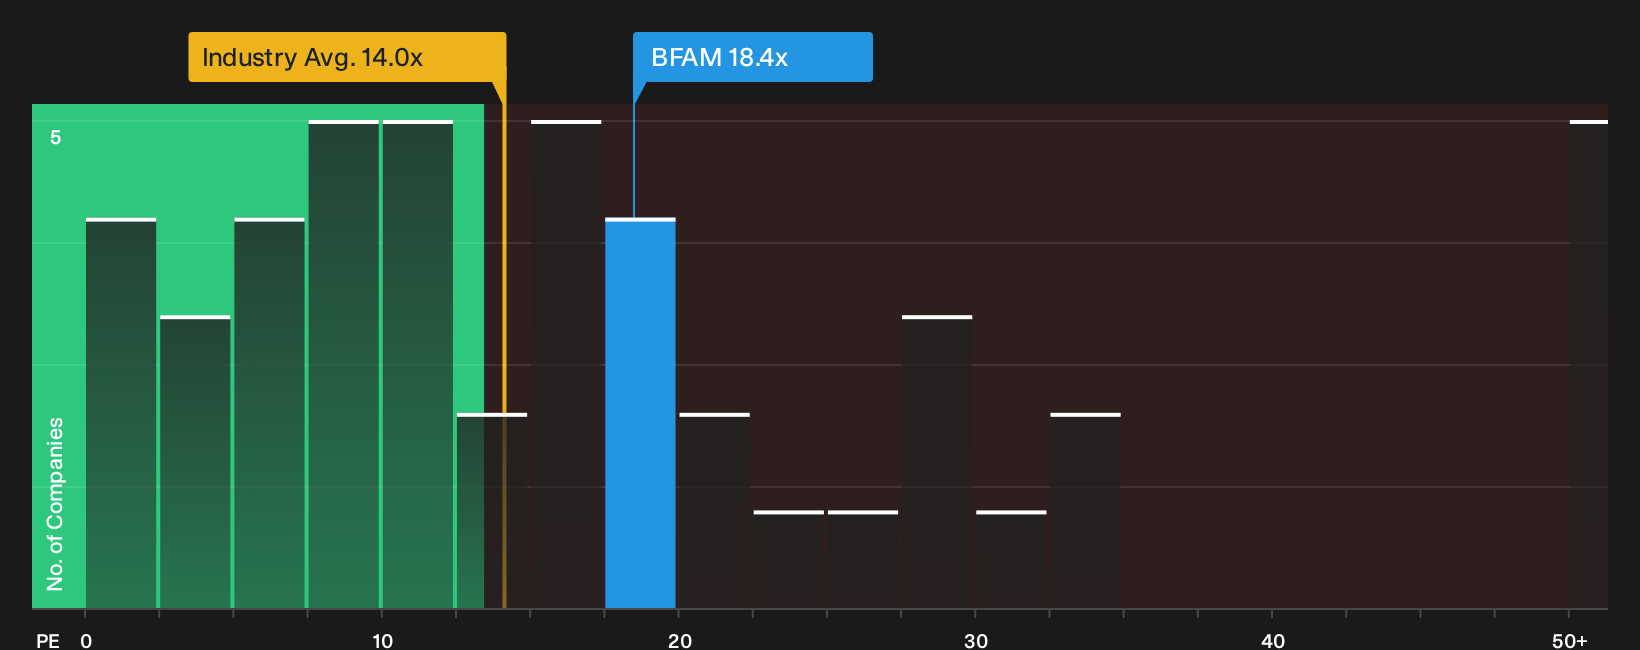
The SWS DCF model points to Bright Horizons Family Solutions trading well below an estimated future cash flow value, yet the P/E ratio of 18.4x still sits above both US Consumer Services peers at 17.8x and the industry at 14x. The fair ratio of 23x suggests the market could shift closer to that level. This raises the question of whether the current gap is a valuation cushion or a sign that expectations are already rich.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Bright Horizons Family Solutions can be confusing. Move quickly, review the data on risks and upsides, then decide where you stand with 3 key rewards and 3 important warning signs.
Looking for more Bright Horizons Family Solutions investment ideas?
If Bright Horizons Family Solutions has your attention, do not stop here. The right watchlist can shape your next move, so put the Simply Wall St screener to work and keep your opportunity set fresh.
- Target resilient income by scanning for companies that combine high yields with staying power using the 7 dividend fortresses.
- Hunt for quality at a discount and see which businesses could offer better value profiles through the 30 high quality undervalued stocks.
- Stack your watchlist with financially sturdy operators by filtering for robust balance sheets using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com