
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Carnival (CCL) Stock Still Looks Like A Bargain On Earnings
Carnival has seen its share price move around sharply in recent years, and with the stock last closing at US$21.79 the key issue now is whether that level is supported by the earnings the group produces. For anyone eyeing the cruise operator today, the central puzzle is how the recent share price path lines up with what the underlying profit stream can reasonably justify.
- Over the past 3 years the stock has gained 53.3%, which puts the focus firmly on whether that rebound is matched by the earnings power backing the current valuation.
- The business relies on turning capital intensive ships into consistent cash flow, so occupancy, pricing and cost control all feed directly into how much profit each US$ of the share price is asking you to pay for.
- The analysts covering Carnival have run their own numbers. See what analysts think Carnival's shares could be worth.
For investors, the debate is whether Carnival's current share price fairly reflects the earnings the company is generating today and is expected to sustain.
If you are weighing Carnival against other earnings focused opportunities, it can help to compare it with companies screened for 30 high quality undervalued stocks.
Is Carnival Still Cheap on Earnings?
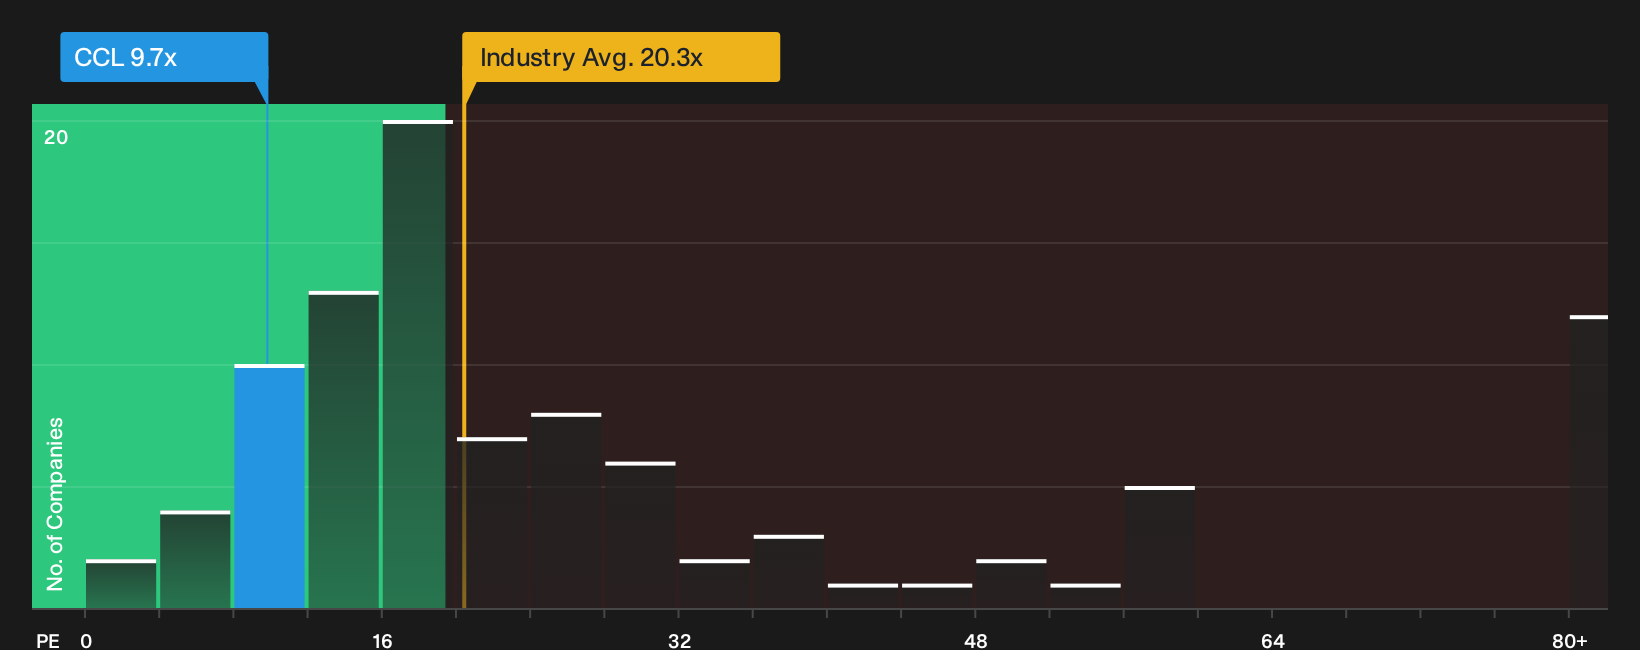
The P/E ratio is a useful shorthand for Carnival because earnings are now a key anchor for judging what you are paying for each unit of profit. On this measure, Carnival trades at about 9.7x earnings, which is well below the broader hospitality sector on roughly 20.3x and also under the peer group at about 15.8x.
The tailored fair multiple that blends Carnival’s growth outlook, margins, scale and risk profile implies a higher P/E than where the shares are currently priced. That gap means the stock screens as undervalued on this earnings yardstick. However, you still need to weigh how cyclical demand, balance sheet strength and ship investment needs could influence the future earnings that this P/E is built on. Explore the numbers behind Carnival's P/E valuation.
The Carnival Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle leaves off for Carnival by spelling out which earnings, margin and growth assumptions would need to hold for the stock to be worth materially more or less than today’s price on the Community page. Each scenario ties a fair value to a particular mix of potential catalysts and pressure points so you can track over time which version of Carnival's story appears to be gaining traction.
One of the top community narratives on Carnival: 37% undervalued
"Ongoing modernization of the fleet through programs such as AIDA Evolution and the addition of new, fuel efficient Excel class and next generation ships is improving guest experience, reducing operating costs, and enabling premium pricing…"
Discover why this Narrative puts Carnival at 37% undervalued.
One more Carnival check that belongs beside the earnings math
Before you get too comfortable with where Carnival trades on profit, it helps to look at who is steering the ships and how their rewards line up with your interests. See who runs Carnival and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com