
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
British Undervalued Stocks For September 2026
With global government bond yields hovering near 4% for the first time since 2007, the price of money has become far more demanding. Investors who once leaned on cheap borrowing and momentum now care a lot more about what actually comes through the cash register. That is where a basket of United Kingdom companies priced below what their future cash flows suggest can look interesting. This article highlights three such stocks from our cash flow valuation screen and explains why disciplined buyers may want to keep them on a watchlist.
The three stocks that follow are just a sample, and the full screen surfaced nine more companies with equally interesting cash flow stories that are not covered here.
If you want to move beyond this shortlist and identify your own high-conviction ideas, head straight to the Undervalued Stocks Based On Cash Flows screener.
LSL Property Services (LSE:LSL)
LSL Property Services runs a capital light platform across mortgage advice, property surveying and franchised estate agencies in the UK. Its £110.7 million Surveying & Valuation arm provides the fee based cash flows central to this screener theme, alongside £48.2 million from Financial Services and £26.7 million from Estate Agency, and a market value of about £252 million.
For investors focused on dependable cash generation, LSL Property Services offers a property services platform where fee based valuations and advisory work matter more than short term housing headlines. This is exactly the kind of setup this cash flow screen is built to surface.
"Rising mortgage refinancing activity, with large volumes of two year and five year products maturing, should sustain higher new lending flows through LSL’s adviser network and underpin continued growth in Financial Services revenue and earnings."
The real swing factor is how one pressure on profitability unfolds if cost discipline and pricing power diverge from what current forecasts assume.
If that profitability pressure is what really matters to you, the full narrative for LSL Property Services shows how LSL Property Services could still harness refinancing tailwinds and cost discipline.

AltynGold (LSE:ALTN)
AltynGold is a London headquartered miner that owns and operates the Sekisovskoye gold operation and nearby Teren Sai projects in northeast Kazakhstan. The company produces gold and silver that drive the cash flows at the heart of this screen, with $175 million from Sekisovskoye and a market value around £284 million.
For a cash flow focused investor, AltynGold aligns with the criteria used in this screen. The Sekisovskoye mine is the single operating engine. A P/E of 5.9x sits below industry averages near 12x, and a DCF value almost double the current share price highlights the potential valuation impact if one unseen funding pressure stays contained.
That unseen funding pressure is exactly what you should stress test with the DCF valuation analysis for AltynGold to see how sensitive AltynGold’s valuation might be to the next move.
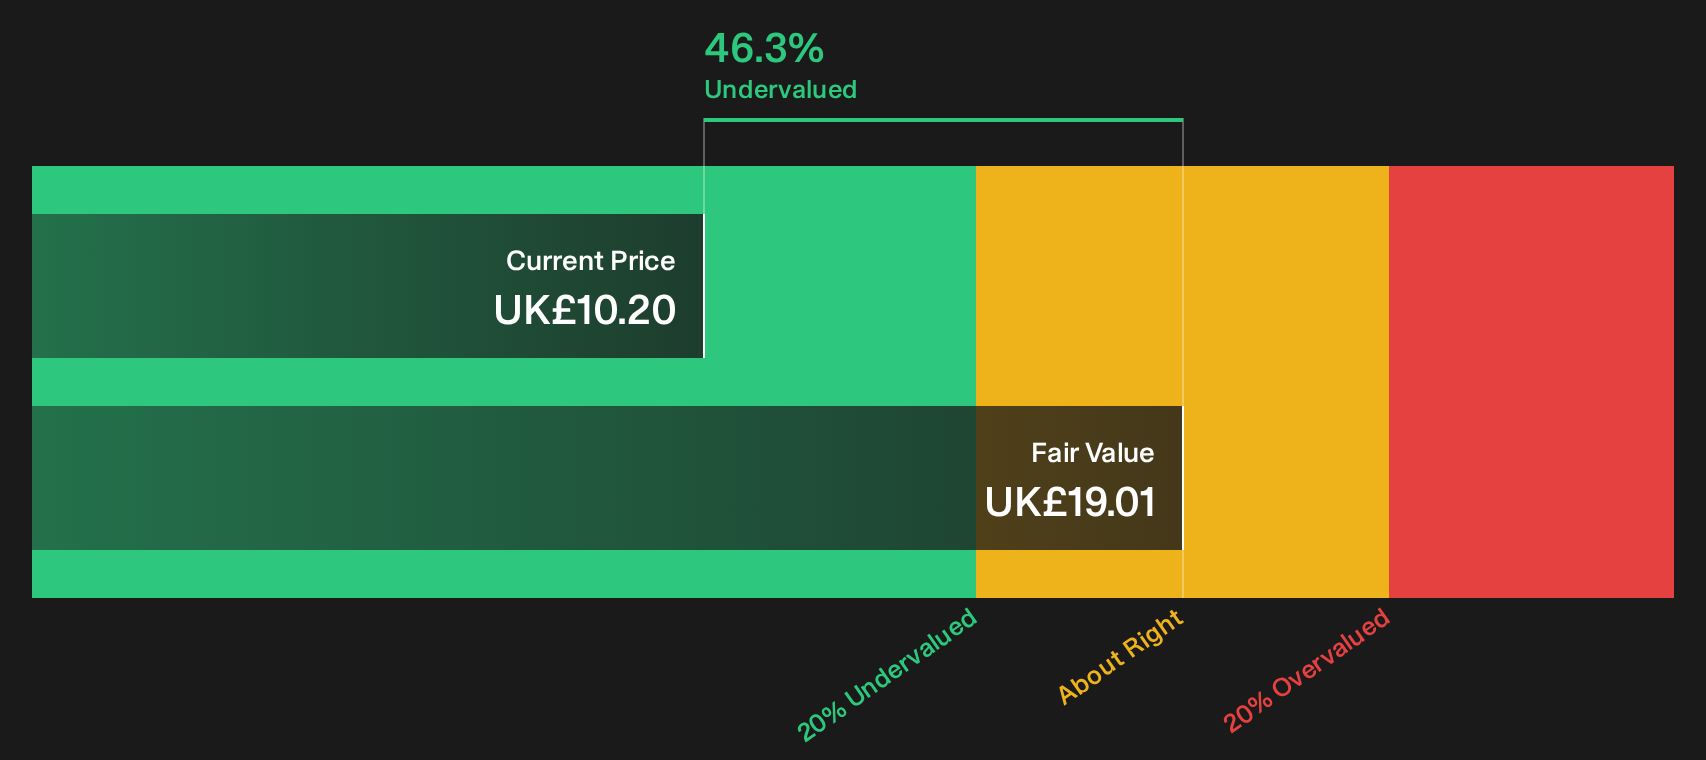
Foresight Group Holdings (LSE:FSG)
Foresight Group Holdings is an asset manager that channels investor capital into infrastructure and private equity, with a large Real Assets arm focused on renewable energy projects that generate fee based cash flows. Real Assets contribute about £115 million of revenue, Private Equity adds roughly £50 million, and the stock is valued at around £471 million.
For investors hunting for undervalued cash flow stories, Foresight Group Holdings offers a cleaner link to real world assets where fee income is tied to long term renewable projects rather than short bursts of trading activity, which is exactly what makes the next detail so important.
"While consensus anticipates margin expansion from operational efficiencies and higher-margin platforms, management's explicit guidance to overshoot fundraising targets (already running 30 to 40% ahead in Q1 versus last year) and accelerate the business mix into higher-fee, scalable retail and institutional products signals faster than forecast margin recovery and EBITDA/EPS outperformance by 2029."
What could really shift the story for Foresight Group Holdings is how one underappreciated pressure on those future fee streams shapes investor confidence in its cash flow profile.
That underappreciated pressure is exactly what makes the full narrative for Foresight Group Holdings worth reading, as it lays out how fee streams could accelerate or stall from here.

Seeking Fresh Alternatives Before They Fly
Markets move fast and the best breakout stories are often caught quietly, under the radar for now, before momentum really builds. Scan fresh ideas while it matters and look for opportunities early.
- Track income engines that could keep paying out even when headlines turn rough by scanning a curated set of payout heavy opportunities with the 1 dividend fortresses.
- Spot potential early leaders in AI infrastructure before attention fully lands on them by reviewing the hand picked group inside the 84 AI infrastructure stocks.
- Explore the gold sector by checking a focused list of producers filtered for financial strength and scale via the 36 elite gold producer stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com