
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What UPS's Amazon Volume Cut Means For Shareholders
- United Parcel Service has been cutting around 2 million low quality Amazon packages per day and concentrating on higher revenue per piece, while its dividend payout ratio sits close to 100% and free cash flow yield remains high relative to its market value.
- The business is intentionally running a smaller network and shrinking low margin e commerce volume so it can test whether tighter operations can still support its sizable dividend and cash generation profile.
- Now the focus turns to how this intentional volume reduction at United Parcel Service could reshape the existing investment narrative.
Compare United Parcel Service's high-yield, high-payout profile with other income ideas by scanning our curated list of 7 dividend fortresses that prioritize cash returns to shareholders.
United Parcel Service Investment Narrative Recap
To own United Parcel Service, you need to believe the leaner network can still support its heavy dividend commitments and high free cash flow yield. Management is cutting low quality Amazon parcels and running a smaller operation that aims for stronger revenue per piece. The short term swing factor is whether cost cuts and pricing hold up as volumes reset.
The biggest risk right now is that this high payout ratio meets a bump in cash generation if trade flows soften or the network reconfiguration proves more disruptive than planned. If those pressures stay contained, the recent Amazon volume cuts look more like noise than a break in the core income story.
The key announcement tied to this story is UPS accelerating its exit from lower margin Amazon deliveries, targeting more than a 50% reduction by June 2026. That decision fits tightly with the current earnings mix, where the business is prioritizing higher revenue per package and testing how far it can push a smaller, denser system.
This same plan overlaps with the Network of the Future program and the push toward US$3.5b in annual cost savings in 2025. Execution on those efficiencies is the real catalyst for shoring up dividend coverage and supporting free cash flow, while any misstep in the restructuring or competitive response sits squarely on the risk side of the ledger.
United Parcel Service's narrative projects US$100.1b revenue and US$7.2b earnings by 2029. This implies 3.6% yearly revenue growth and an earnings increase of about US$2.6b from US$4.6b today.
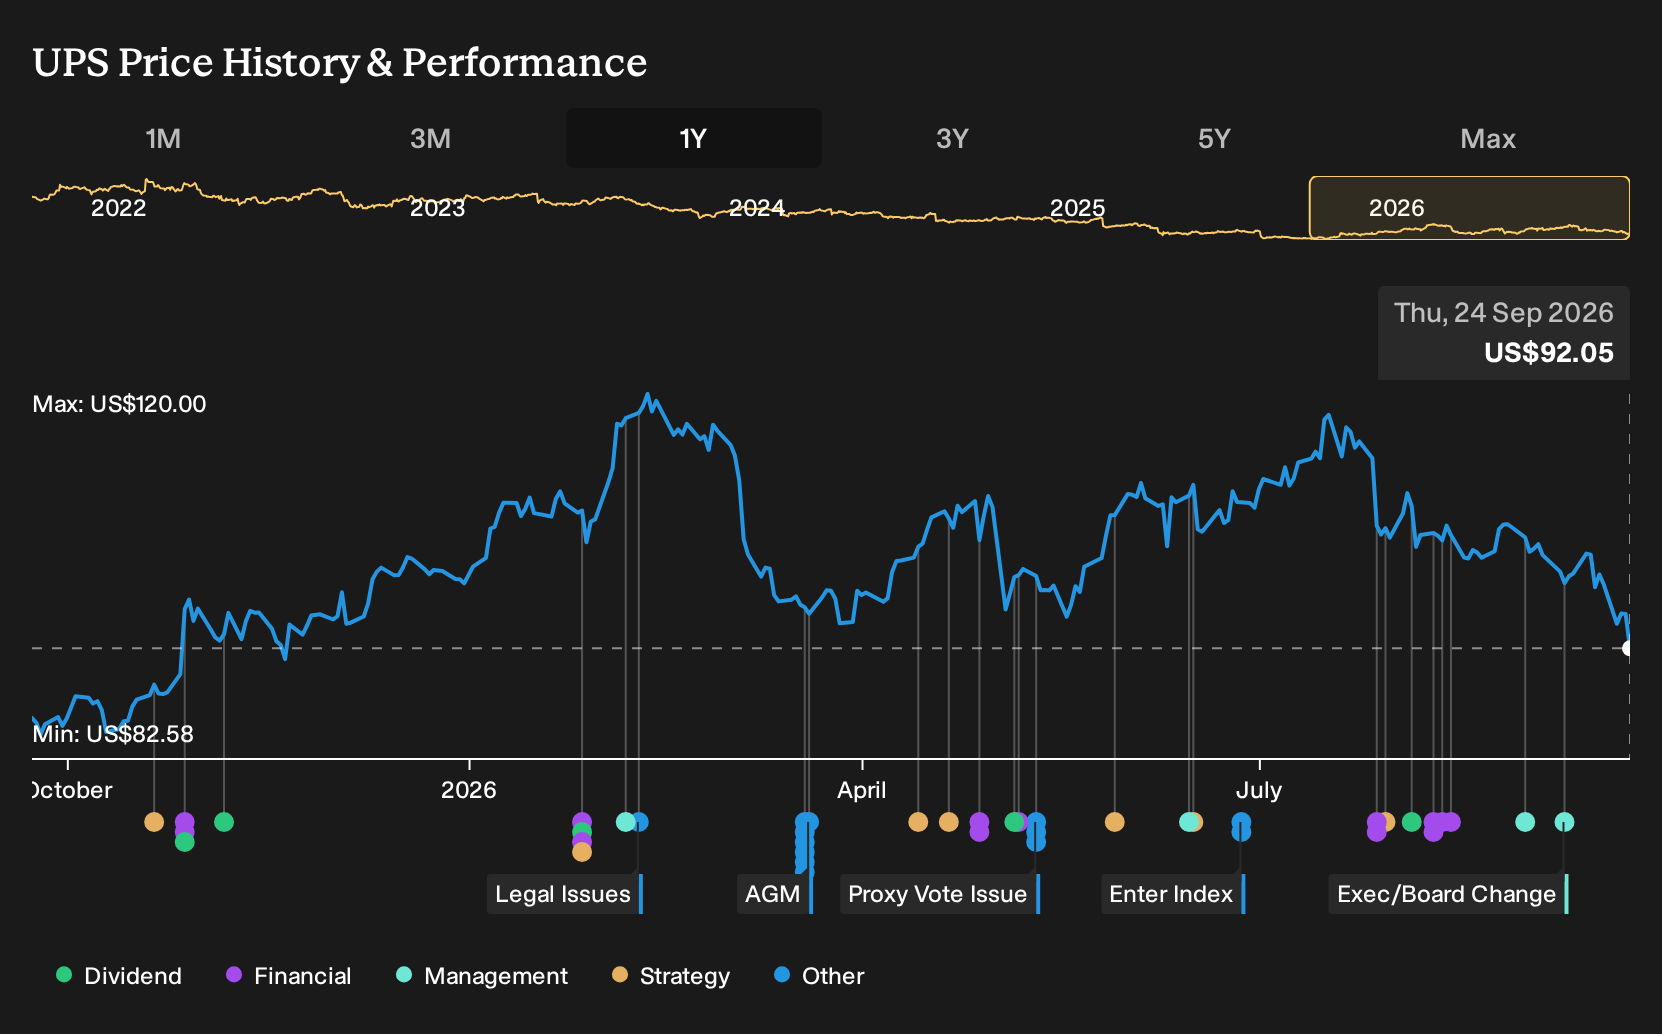
Uncover why United Parcel Service's fair value indicates a 26% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the lowest analysts on United Parcel Service put much more weight on trade friction. They were only penciling in about US$93.4b of revenue and US$6.0b of earnings by 2029 before this Amazon shift hit the headlines. Their story is more cautious. Yours does not have to be, but it should be informed.
Explore 9 other United Parcel Service fair value estimates, including one that indicates up to 8% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your United Parcel Service research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for United Parcel Service. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Parcel Service's overall financial health at a glance.
Looking for more investment ideas beyond United Parcel Service?
Once you have a handle on United Parcel Service, it often helps to widen the lens and compare it with other companies that match different income, quality, and risk profiles using the Simply Wall St Screener.
- If you want to balance yield with resilience, consider starting with a list of solid balance sheet and fundamentals (23 results) that can help you focus on companies prioritizing financial strength.
- For investors hunting for potential value opportunities, scan a 30 high quality undervalued stocks to find companies that combine quality fundamentals with prices that may not fully reflect them yet.
- If stability is your priority, filter for a 31 resilient stocks with low risk scores to identify businesses with lower risk scores based on a broad set of financial checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com