
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
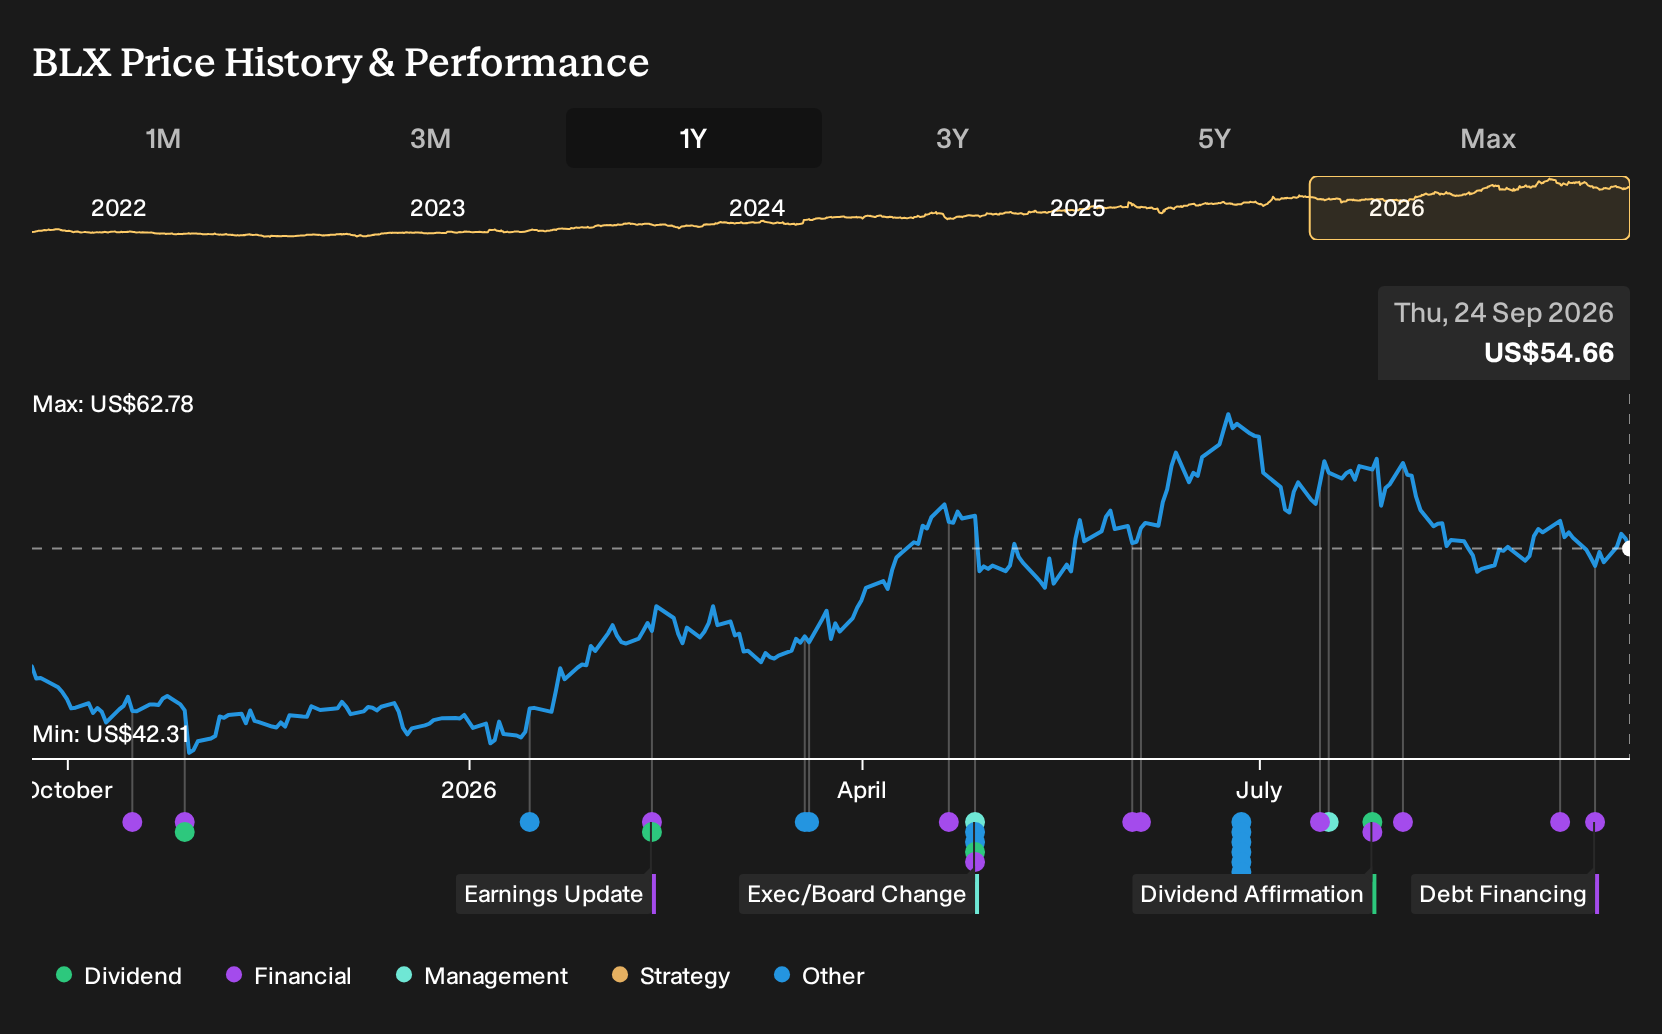
Panama Loan Could Be A Big Moment For Bladex Stock (BLX)
- Bladex announced that it structured a senior loan facility of up to US$1.0b for the Republic of Panama's Ministry of Economy and Finance, with proceeds allocated to general budgetary purposes.
- The transaction is the largest ever structured by Bladex, signaling meaningful execution capacity in large sovereign deals and reinforcing its role in complex regional financing.
- This development also shapes how investors may view Bladex's investment narrative, particularly in relation to the record Panama sovereign loan and its structured finance focus.
Extend your search beyond Bladex and scan a curated 31 resilient stocks with low risk scores that may appeal if this record Panama loan has you focused on resilient balance sheets and controlled risk.
Bladex Investment Narrative Recap
To own Bladex, you need to believe in a Latin America focused trade bank that can keep turning complex sovereign and institutional relationships into repeatable fee and interest income, while protecting asset quality. The record Panama facility reinforces that core idea but does not remove key short term questions around the depth and recurrence of these transactions beyond one off syndications.
The most immediate swing factor remains deal flow in structured and syndicated credit, after prior reliance on a single large Staatsolie transaction. The biggest risk still sits in concentrated regional sovereign and quasi sovereign exposure in a volatile macro backdrop, where weaker demand or credit stress could pressure margins and earnings stability.
The Panama senior loan fits directly into Bladex’s push toward medium term structured transactions and larger mandates with sovereign and institutional clients. For a shareholder, the practical question is whether this type of facility becomes part of a broader pattern of sizeable, fee rich transactions or remains sporadic in the portfolio.
No other recent disclosure sits closer to this story than the bank’s emphasis on scaling structured finance and trade products, including its digital platform. Execution on these priorities, together with disciplined underwriting around large sovereign exposures such as Panama, will shape how resilient fee income, net margins, and the perceived risk profile appear over the next stretch of reporting periods.
What The Current Bladex Forecasts Assume
Analysts looking at Bladex are effectively sketching out a future where the bank leans on both structured deals like the Panama senior loan and a growing digital trade platform to support higher earnings on a larger revenue base. The underlying model is not about hyper growth. It is about a mid teens revenue trajectory, stable but slightly lower margins, and a funding mix that keeps net interest income and fee streams relatively predictable.
On the top line, the consensus view assumes revenue grows by 13.2% a year over the next few years. That kind of pace would normally point to more than just one off sovereign mandates. It suggests a thicker pipeline of trade finance transactions, as well as onboarding more clients and volumes into the digital platform so that fee income can play a larger role alongside interest income from the loan book.
Earnings today are put at US$224.0 million, with analysts expecting profit to reach US$300.0 million by 2029 on earnings per share of US$8.06. That implies an increase of roughly US$76 million in net income, even as profit margins are projected to soften from 69.3% to 64.0%. For you as a shareholder, the message is that analysts think Bladex can earn more absolute profit on a fatter revenue base, even if each dollar of revenue drops slightly less to the bottom line.
Those forecasts also rely on Bladex gently expanding its share count, with analysts factoring in 0.82% yearly growth in shares outstanding over the next three years. A slow creep in issuance means a growing earnings pie still needs to be large enough for per share earnings to move higher. That is where expectations around more structured mandates, recurring trade flows, and cross selling on the digital platform become important, because they shape how much of the earnings growth actually reaches each share you own.
Valuation assumptions flow directly from those operating forecasts. The consensus work up points to revenue of US$469.0 million and earnings of US$300.0 million by 2029. To bridge from today’s price to the analyst target, the math uses a discount rate close to 9.4% and a future P/E multiple of 11.0x on those forecast earnings. That projected multiple sits below the 14.7x level quoted for the broader US diversified financials group in the report, which effectively builds in a modest relative discount for the stock while still assuming some recognition of Bladex’s earnings profile.
Bladex's setup implies forecast revenue of US$469.0 million and earnings of US$300.0 million by 2029, supported by assumed 13.2% yearly revenue growth and an earnings increase of about US$76 million from US$224.0 million today.
Uncover why Bladex's fair value indicates a 20% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the highest Bladex forecasts leaned hard into fee growth from digitalization, expecting revenue of about US$498.8 million and earnings of US$332.4 million by 2029, versus roughly US$469.0 million and US$300.0 million in the baseline. If you think this record Panama loan shifts that debate, explore both narratives before deciding.
Explore 3 other Bladex fair value estimates, including one that suggests up to 99% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Bladex research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bladex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bladex's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bladex?
If this Bladex update has sharpened your focus on risk, return, and balance sheet strength, it can be useful to line those views up against a broader watchlist using the Simply Wall St Screener.
- If you want potential upside with more limited downside, start with a curated set of resilient businesses through the 31 resilient stocks with low risk scores.
- For readers hunting for value where fundamentals and price are out of sync, scan a focused group of opportunities via the 30 high quality undervalued stocks.
- Income minded investors who care about steady cash returns can review high yielding candidates using the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com