
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Valero (VLO) Stock Looks Rich Against Its Cash Flow Outlook
Valero Energy has delivered a powerful run over the past several years, which puts fresh attention on what investors are really paying for its cash generation today. With the stock now reflecting a very different market view than it did five years ago, the key issue is how that price lines up with the cash flows the business can sustain.
- Over the past 5 years, Valero Energy has returned about 7x, which puts a lot of weight on whether the current market value is grounded in its cash producing power.
- For a refiner that relies heavily on converting earnings into hard cash and managing large capital projects, any shift in refining margins or investment needs can quickly change what those future cash flows are worth today.
- If you'd rather focus on earnings, this one's for you. See what Valero Energy's 15.3x P/E says about the price.
The issue now is whether Valero Energy's current share price is adequately backed by the cash flows implied by a Discounted Cash Flow (DCF) intrinsic value estimate.
If you want to test this same cash flow question across a broader set of ideas, scan companies in the 30 high quality undervalued stocks.
Has Valero Energy Run Too Far on Cash Flow?
The Discounted Cash Flow (DCF) approach here centers on the cash Valero Energy can return to shareholders over time. Over the last twelve months, the refiner produced about $10.0b of free cash flow, a level that gives the model plenty of actual cash generation to work with rather than just headline earnings.
Analysts in the DCF framework are not assuming a straight growth story for Valero Energy. Forecast free cash flow in the late 2020s sits in the billions of dollars but trends lower by the mid 2030s, which reflects the risk that refining conditions or investment needs could pressure future cash generation from here. When those projected streams are discounted back and compared with the current share price of $382.86, the DCF output suggests Valero Energy's estimated intrinsic value is meaningfully below where the stock trades today. Find out what Valero Energy could be worth using our Discounted Cash Flow (DCF) estimate.
The Valero Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Valero Energy pick up where the valuation puzzle leaves off and spell out the specific future paths for growth, margins and earnings that would need to play out for the stock to be worth materially more or less than it is today. Instead of a single output from a ratio or DCF model, Narratives lay out the underlying assumptions so you can watch how Valero Energy's actual progress lines up with the future that number depends on, and they sit on the Community page.
Valero Energy attracts two very different readings, with one group leaning into tight refining conditions and buybacks while the other leans toward a cooler outlook on future returns.
Bull case: 15% undervalued
"Shorter cycle optimization projects planned for 2026, focused on crude and product optionality in refining plus efficiency and rate expansion in ethanol plants, are explicitly targeted at raising the earnings capacity of the existing asset base..."
Discover why this Narrative puts Valero Energy at 15% undervalued.
Bear case: 43% overvalued
"High operational cost pressures, particularly from maintenance and potential fluctuations in natural gas prices, may constrain margin improvements, thus impacting overall profitability..."
Explore why this Narrative puts Valero Energy at 43% overvalued.
One more issue for Valero Energy that the valuation does not answer
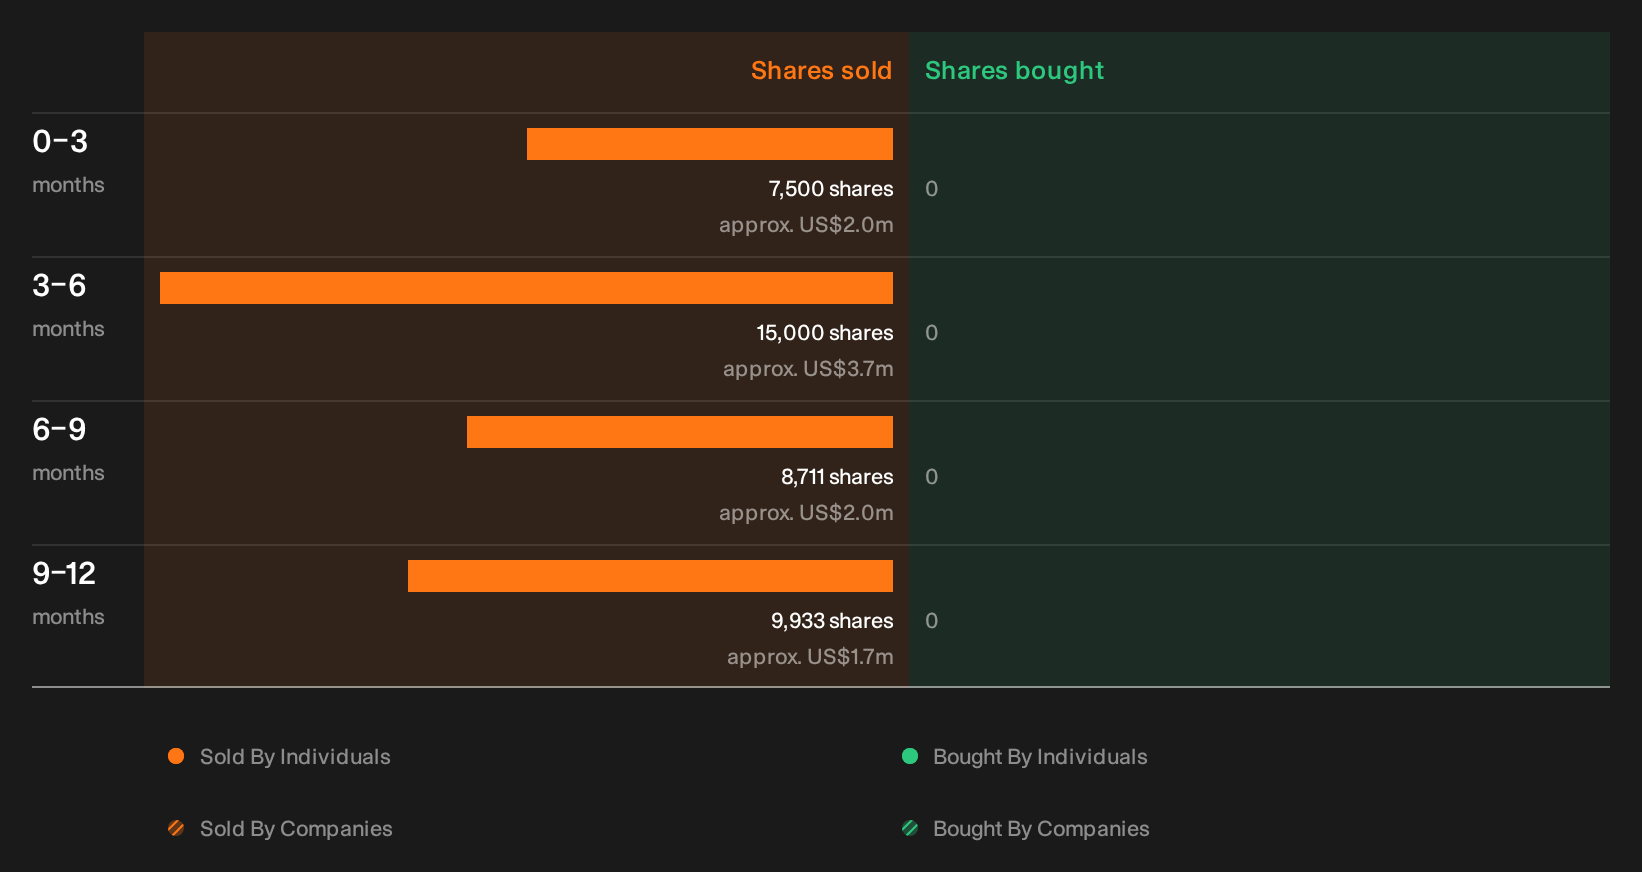
Price and cash flows tell only part of the story for Valero Energy. Recent insider activity has triggered an alert in the checks, and the identities, sizes and possible read throughs are still for you to review. See the recent insider selling flagged for Valero Energy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com