
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Sphere Entertainment (SPHR), What Is Behind The Fresh Attention?
Why Sphere Entertainment Stock Is Back In Focus
Sphere Entertainment (SPHR) moved back onto investor watchlists after stronger than expected quarterly results and a new multi year technology partnership with longtime collaborator Disguise.
The earnings surprise highlighted demand for the Las Vegas Sphere venue. The expanded Disguise agreement connected that operating momentum to a clearer technology roadmap that could influence how investors view the business over time.
Sphere Entertainment’s share price has pulled back in the short term, with a 30 day share price return of down 13.4% and a 90 day share price return of down 18.5%. The stock is still up 46.8% year to date and has delivered a 1 year total shareholder return of about 140%, which points to strong momentum that the recent earnings beat and new Disguise partnership may be helping to sustain.
Spot similar entertainment and media stories gaining traction by scanning our hand picked 16 high quality undiscovered gems that pair strong fundamentals with under-the-radar share price momentum.Spectrum of views on Sphere Entertainment is wide right now. With shares at about $138 and analyst targets near $180 while intrinsic models flag a premium, where does fair value really sit after this run and pullback?
Most Popular Narrative: 22% Undervalued
Sphere Entertainment’s most followed valuation storyline pegs fair value around $176.55 per share, ahead of the recent $138.44 close. This keeps attention on how its venue concept and content slate might support that gap over time.
The expansion into new markets, particularly the development of both full-size and smaller franchise-model Spheres internationally (such as in Abu Dhabi and potential other cities), directly positions Sphere Entertainment to benefit from the increasing demand for experiential destination entertainment, supporting long-term revenue growth and margin scalability through asset-light models.
Monetization of proprietary Sphere Studios technology and content (such as AI-driven immersive productions) across a global network of venues, bolstered by evergreen IP and syndication across all Spheres, unlocks incremental, high-margin earnings streams and reinforces Sphere's competitive moat beyond traditional ticket sales.
See why 7 investors see Sphere Entertainment as 22% undervalued.
Result: Fair Value of $176.55 (UNDERVALUED)
Still, Sphere Entertainment’s story could be tested if high construction and technology costs weigh on future venues, or if demand softens for a concentrated slate of shows.
Find out about the key risks to this Sphere Entertainment narrative.
Another View: Sphere Entertainment Looks Expensive On Sales
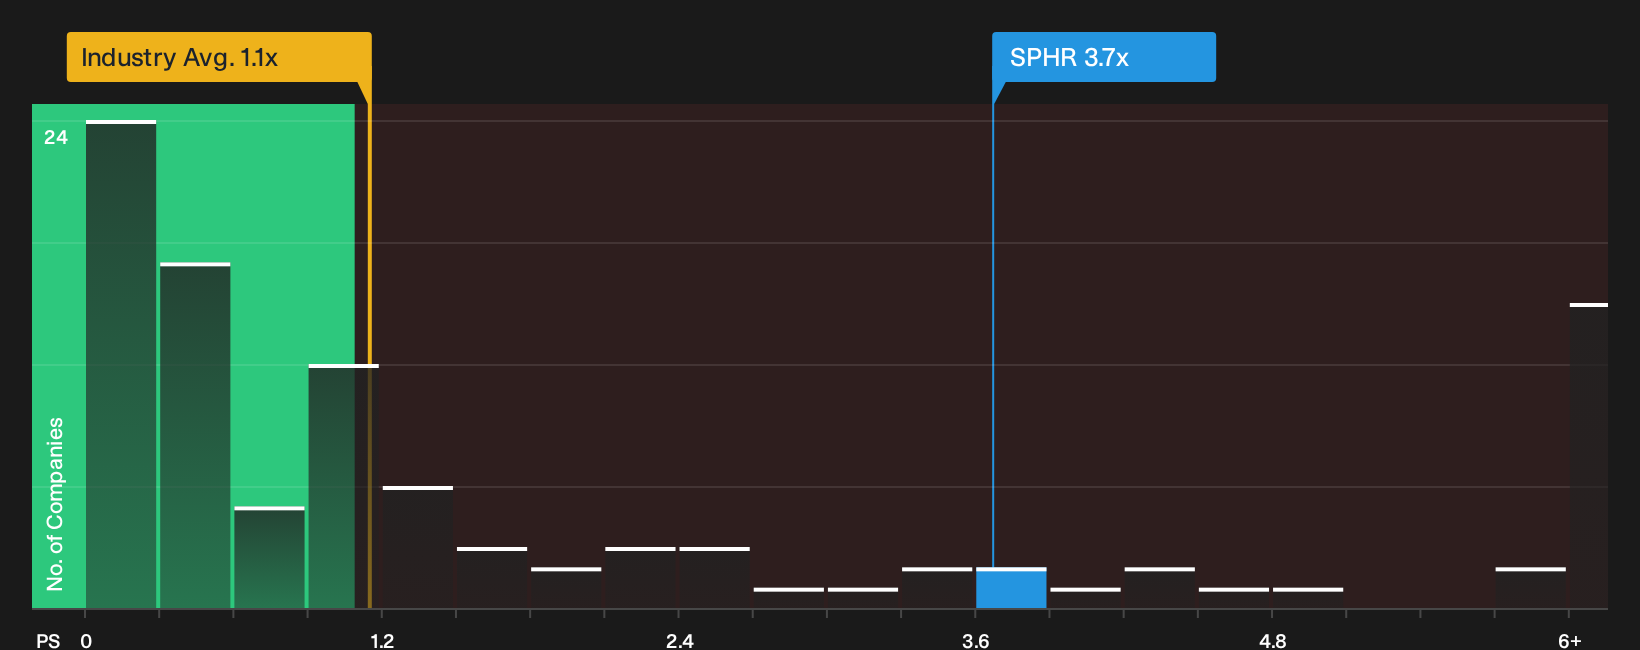
While the leading narrative frames Sphere Entertainment as about 22% undervalued, the simple P/S check tells a different story. SPHR trades on a 3.7x P/S ratio, compared with 1.1x for the US Entertainment sector, 3.4x for peers, and a fair ratio of 1.3x that the market could move toward over time. If sentiment cools, are investors comfortable with that kind of multiple risk?
To see how the valuation stacks up using this yardstick, and what the gap to the fair ratio could mean if expectations reset, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of investors see Sphere Entertainment as promising, while others are wary of the trade off between risks and rewards. Act quickly, review the underlying data, and weigh both sides of the story by checking the 1 key reward and 1 important warning sign
Looking For More Ideas Beyond Sphere Entertainment?
Sphere Entertainment might be front of mind today, but your next strong opportunity could be sitting somewhere completely different. Do not leave that search to chance.
- Target companies that mix quality with meaningful valuation gaps by scanning the 30 high quality undervalued stocks and see which stocks currently line up with that profile.
- Build a portfolio that works harder for your income goals by reviewing the 7 dividend fortresses and spotting yields that may deserve a closer look.
- Dial back potential downside and focus on resilience by checking the 30 resilient stocks with low risk scores so you are not caught off guard when conditions change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com