
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Barry Callebaut (SWX:BARN) Undervalued As Analysts See Only Limited Upside?
Barry Callebaut (SWX:BARN) is back in focus after recent share price moves, which leave the chocolate maker down about 2% over the past month and roughly 2% lower over the past 3 months.
At around CHF1,121 per share, Barry Callebaut has seen its short term share price drift lower, with the year to date share price return down 11.38%. However, the 1 year total shareholder return is positive at 4.73%, which hints that dividends are doing more of the heavy lifting than recent price momentum.
Spot under-pressure consumer stocks like Barry Callebaut and compare them with a hand picked 177 high quality undervalued stocks that pair resilient balance sheets with more appealing recent returns.Bulls point to Barry Callebaut’s positive 1 year return and rising net income, while bears focus on falling revenue, weak multi year performance and recent price drift. Which side does the current valuation support next?
Most Popular Narrative: 2% Undervalued
Barry Callebaut's most followed narrative points to a fair value of about CHF1,142 per share, which sits slightly above the last close at CHF1,121 and frames the current price as only modestly below that central estimate.
The analysts have a consensus price target of CHF1142.08 for Barry Callebaut based on their expectations of its future earnings growth, profit margins and other risk factors. However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of CHF1470.0, and the most bearish reporting a price target of just CHF960.0.
See why 27 investors see Barry Callebaut as 2% undervalued.
The fair value narrative uses a discount rate of about 4.0% and weighs declining revenue assumptions against improving margins and earnings forecasts. With the current share price only about 2% below the implied fair value of roughly CHF1,142, the market price and this framework are closely aligned, which limits the margin of safety but also suggests no glaring disconnect.
Result: Fair Value of CHF1,142 (ABOUT RIGHT)
Still, this fair value story could be knocked off course if cocoa price volatility continues to squeeze margins or if weak revenue trends and delayed customer orders persist.
Find out about the key risks to this Barry Callebaut narrative.
Another View on Barry Callebaut’s Valuation
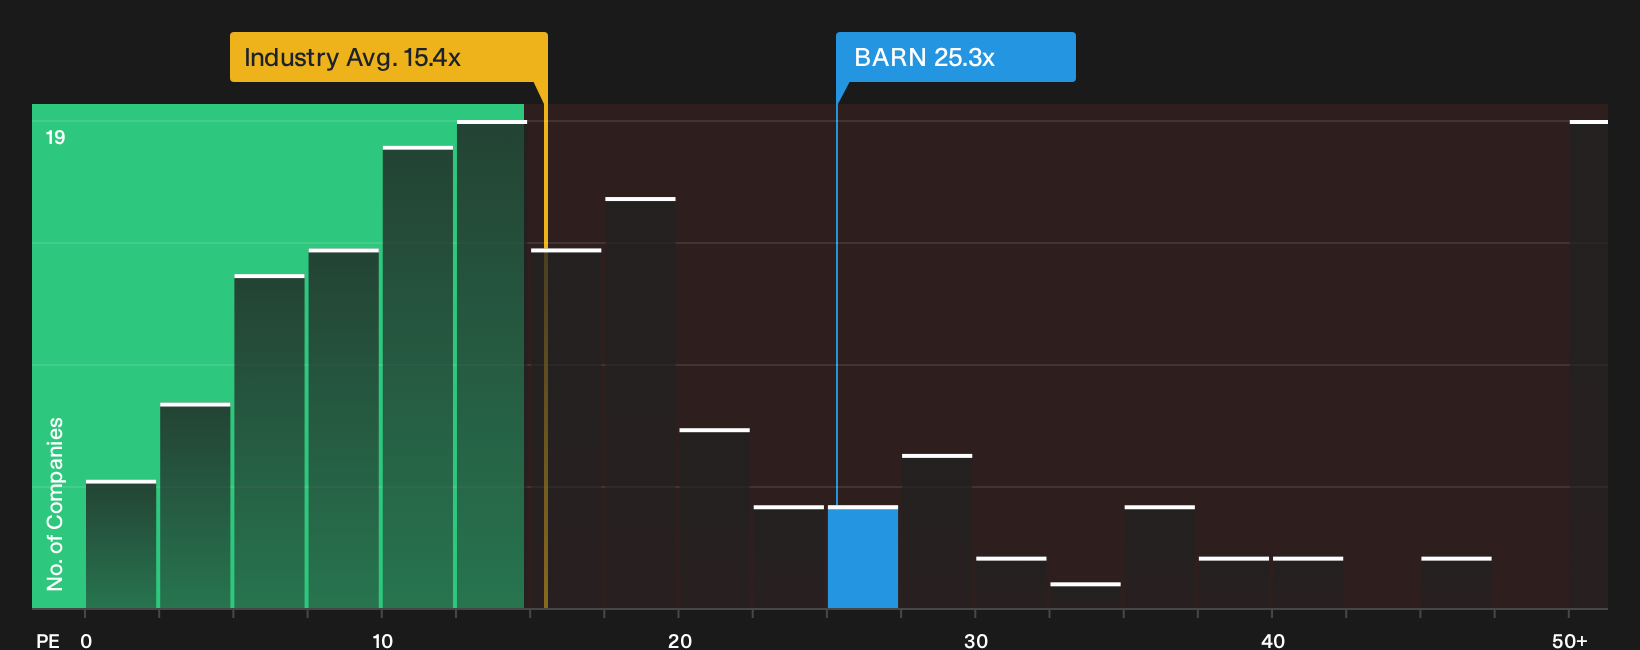
The analyst fair value puts Barry Callebaut roughly in line with its current CHF1,121 share price, but the P/E picture is less forgiving. The stock trades on about 25.3x earnings, compared with 18.8x for peers and 15.4x for the wider European Food group, even though the fair ratio sits close by at 25.6x.
That combination, a premium to sector averages but only a small gap to the fair ratio, suggests limited room for disappointment if earnings do not keep pace with expectations. The question for investors is whether Barry Callebaut has earned that premium or whether the crowd is paying up for comfort.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment on Barry Callebaut split between pressure points and bright spots, do not wait for consensus to form before you check the data yourself and weigh both sides. To see the key risks and rewards in one place, start with these 3 key rewards and 2 important warning signs.
Looking for more Barry Callebaut style investment ideas?
If Barry Callebaut has your attention, do not stop at a single ticker. Use focused stock lists to pressure test your thinking and uncover better fits.
- Target higher income potential by reviewing companies in the 158 dividend fortresses that combine robust payouts with meaningful yield.
- Strengthen capital preservation by scanning the 229 resilient stocks with low risk scores that highlight businesses with more resilient risk profiles.
- Get ahead of the crowd by investigating the 619 high quality undiscovered gems that spotlight quality opportunities the market may be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com