
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Brink's (BCO) Stock May Still Be Cheap On Current Earnings
Brink's has delivered a strong multi year share price gain, even though the stock has been softer more recently. That track record now raises a simple question for you as an investor. Is the current US$105.85 price still supported by the earnings the business is generating today?
- Over the past 5 years, Brink's has returned about 76.8%. This puts real weight on whether its profit stream can keep backing up that kind of long haul performance.
- The group runs a labor and asset intensive security and cash management operation, so its ability to convert revenue into steady earnings and free cash flow can have a direct impact on how you think about its valuation.
- There is a second opinion on Brink's worth weighing. See what analysts think Brink's's shares could be worth.
For investors, the debate is whether Brink's current share price is properly aligned with the earnings power the business is showing right now.
If you want a broader starting point alongside Brink's, a focused screen of 30 high quality undervalued stocks can help you identify additional ideas that emphasize earnings strength and valuation discipline.
Does Brink's Look Undervalued on Earnings?
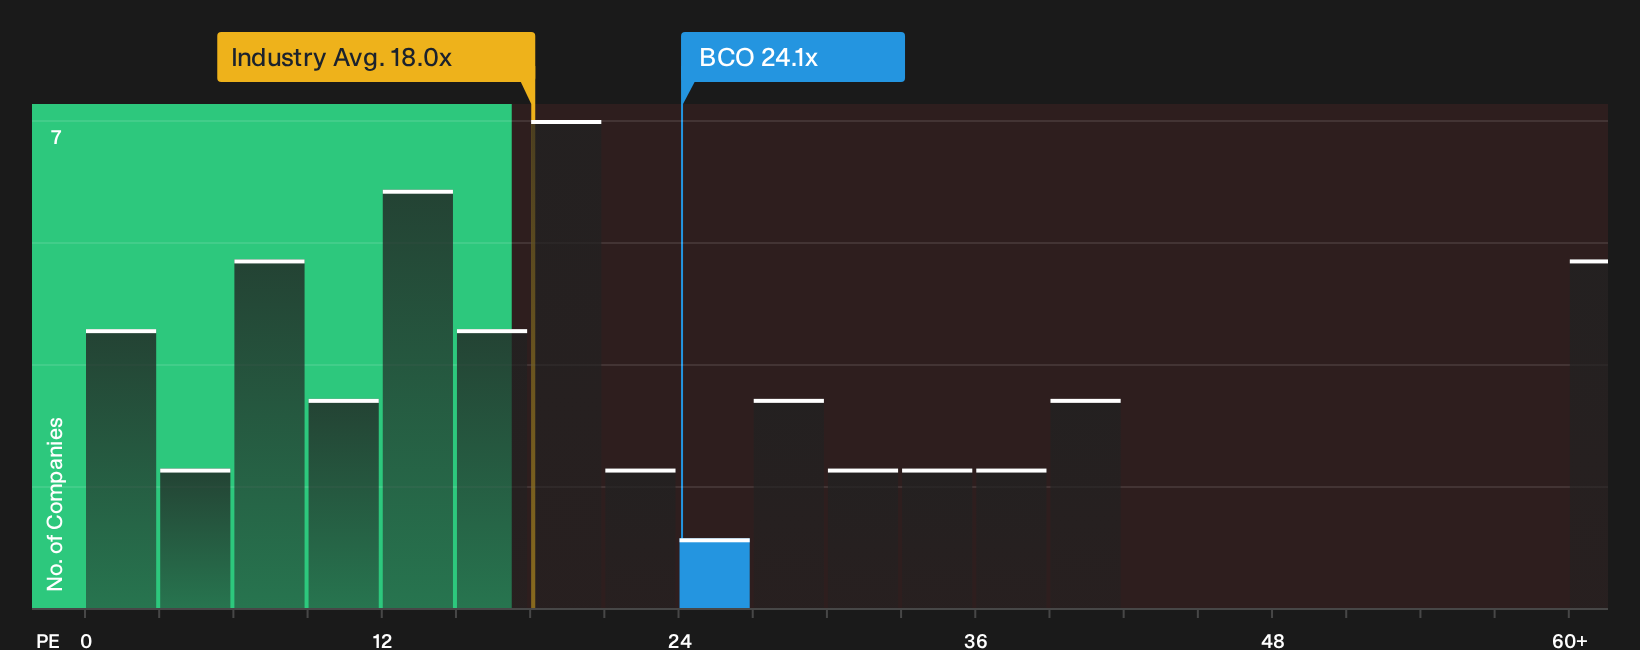
The P/E ratio is a straightforward way to see how much investors are paying for each dollar of Brink's current earnings. On this measure, Brink's trades on about 24.1x earnings, which is close to the peer group average of roughly 25.0x and above the broader Commercial Services sector on about 18.0x.
The fair value model suggests that, given Brink's specific mix of growth prospects, profitability profile, size and risk, the stock would typically command a higher P/E than where it trades now. That gap points to the shares screening as undervalued on this earnings lens, even though the headline multiple on its own does not look especially low versus the sector. Explore the numbers behind Brink's's P/E valuation.
The Brink's Narrative: What Would Justify Today's Price?
For Brink's, Simply Wall St Narratives sit between the current valuation puzzle and the assumptions that could justify a very different price. They spell out what would need to happen to future growth, margins and earnings for the stock to be worth materially more or less than today. Each scenario links a specific fair value estimate to a clear story about possible catalysts and risks, so you can track over time which version of events seems to be unfolding on the Community page.
A clear, number driven narrative on Brink's gives you a structured way to set out what you think happens next with its growth, margins and execution, then measure those assumptions against actual results as they land. It turns a loose view on the stock into a concrete roadmap you can revisit, refine and hold up against Brink's evolving financial profile over time.
Share your own Narrative for Brink's and set out the assumptions behind your valuation.
One more angle on Brink's that deserves your attention
Before forming a clear view on Brink's, it is worth checking the specific risk checks our research has flagged, since those issues can sharply change how you interpret the current valuation picture. Take a closer look at 1 major warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com