
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
FTSE Index Removal Might Change The Case For Investing In United Energy Group (SEHK:467)
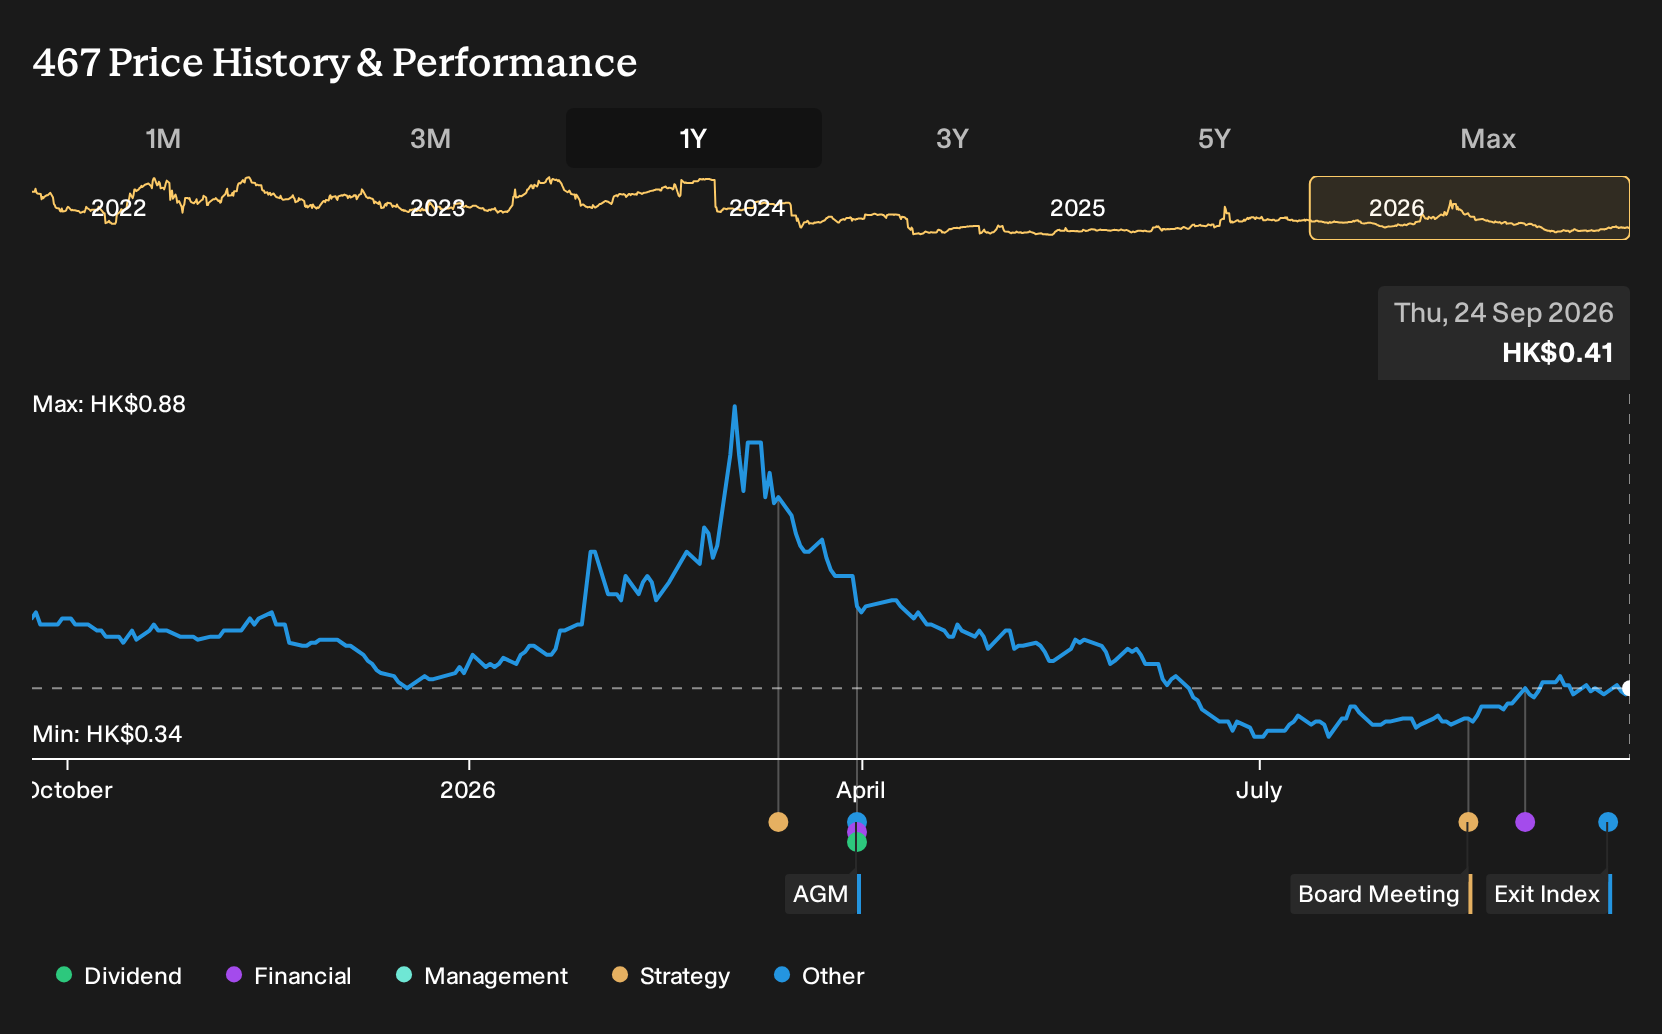
- United Energy Group Limited was removed from the FTSE All-World Index in September 2026, which affects its status within a widely used global benchmark.
- The exclusion may influence how index-tracking funds and benchmark-aware investors treat United Energy Group, with practical implications for liquidity, trading flows, and how the business is represented in diversified portfolios.
- The focus now shifts to how United Energy Group's removal from the FTSE All-World Index could reshape its broader investment narrative for investors.
Scan beyond United Energy Group's index exit and review potential replacements using the curated 176 high quality undervalued stocks that may stand to benefit if capital rotates across global benchmarks.
What Is United Energy Group's Investment Narrative?
To own United Energy Group, you need to buy into a fairly simple idea. This is an energy producer and trader with most revenue tied to upstream oil and gas, plus a smaller but growing clean power arm. The story leans on execution in places like Pakistan, Iraq and Egypt, tight cost control around capital heavy exploration and production, and the ability to sell into trading hubs such as Singapore. The recent drop from the FTSE All World Index mainly speaks to how the shares are owned, not how the fields or turbines run, so the underlying operational levers still matter more.
In the short term, the key questions center on whether management can stabilise earnings after several years of declines, and whether that recent 3.2% profit uplift is the start of something more durable or just noise around a large one off loss. Pricing conditions in oil and gas, combined with the capital demands of exploration and clean energy buildout, remain the obvious swing factors. Index exclusion could add some liquidity and sentiment pressure, yet the more pressing issue is whether United Energy Group can convert a low P/E into a healthier return on equity and cleaner profit quality over time.
Even so, there is one uncomfortable wrinkle in the United Energy Group story that only really shows up once you look at ...
There's only one way to know the right time to buy, sell or hold United Energy Group. Head to Simply Wall St's company report for the latest analysis of United Energy Group's Fair Value.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your United Energy Group research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for United Energy Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Energy Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond United Energy Group?
Once you have a view on United Energy Group, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you filter for exactly the type of businesses you want to research next.
- If capital preservation is your priority, start with companies that pair steadier fundamentals with lower risk characteristics using the 229 resilient stocks with low risk scores.
- For investors seeking stronger balance sheets and cleaner financial footing, narrow the field with a curated list of solid balance sheet and fundamentals (200 results).
- If you are hunting for opportunities that the market may not fully be paying attention to yet, scan through a focused 619 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com