
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
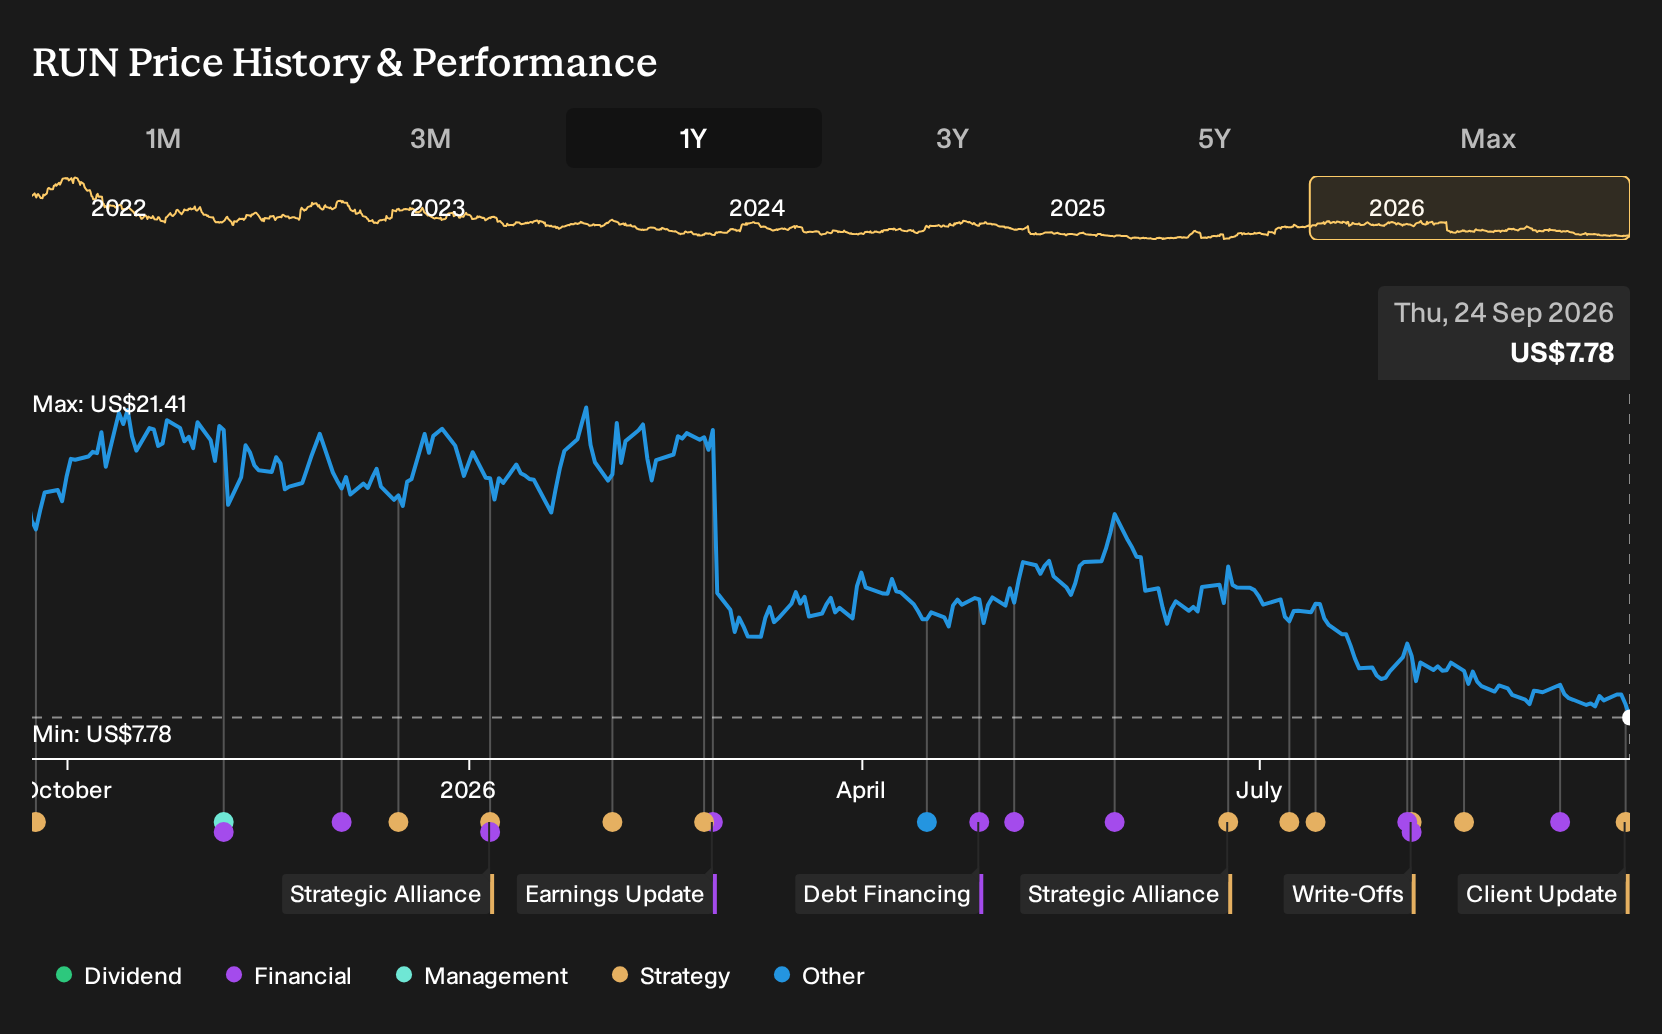
Sunrun Stock Is Down 6.9% What’s Changed As AI Compute Partnership Expands
- Sunrun and SPAN previously announced an expanded partnership that links Sunrun’s residential solar and multi-battery systems with SPAN’s XFRA distributed AI compute nodes. The offering includes whole home backup, compensation for hosting compute hardware, and grid service enrollment for customers at no upfront cost.
- The arrangement turns Sunrun’s installed battery base into both a residential backup resource and a distributed data center network, which could influence customer economics, deployment scale, and how investors think about the firm’s long term role in energy and compute infrastructure.
- We will now look at how this Sunrun and SPAN distributed compute partnership could reshape the broader investment narrative around storage.
Scan beyond Sunrun and this SPAN tie-up by reviewing hand picked 85 AI infrastructure stocks that are also tying energy, hardware, and AI compute together in fast evolving ways.
Sunrun Investment Narrative Recap
To own Sunrun stock, you need to believe that residential solar, batteries, and grid services can support a durable, profitable service model, even as tax credits phase down and customer acquisition remains expensive. The SPAN XFRA partnership leans into that belief by layering AI compute onto the existing solar plus storage footprint, which could deepen the value of each deployed system.
The more pressing near term swing factor is execution on storage attachment, grid services enrollment, and cost control while financing stays available on acceptable terms. The biggest risk remains policy and tax credit uncertainty, alongside a capital intensive structure where interest costs already weigh on earnings coverage.
The expanded SPAN collaboration is the operational highlight tied to this news. Sunrun is effectively trying to make each home battery work harder by supporting backup power, grid services, and now distributed compute. That aligns with the broader push to grow recurring services on top of the installed base, not just one off rooftop projects.
For catalysts, investors will likely watch how quickly Sunrun can sign communities into this model and prove reliable uptime for both households and XFRA nodes without stressing local distribution grids. The concept does not remove the core risks around tax credits, capital access, or rising rates. It gives Sunrun one more way to potentially monetize storage and its distributed power plant fleet.
Sunrun's narrative projects US$3.6b revenue and US$570.8m earnings by 2029. That path assumes 1.3% yearly revenue growth and an earnings increase of about US$170.1m from current earnings of US$400.7m.
Uncover how Sunrun's fair value indicates a 105% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts frame this Sunrun news through a very different lens. They already projected revenue reaching about US$4.5b and earnings near US$697.4m by 2029, driven by faster storage and grid service uptake. Those upbeat expectations may be revisited as the AI compute story sinks in.
Explore 4 other Sunrun fair value estimates, including one that suggests as much as 214% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so trust your own analysis.
- A great starting point for your Sunrun research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sunrun. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Sunrun's overall financial profile at a glance.
Looking for more Sunrun sized investment ideas?
Once you have a view on Sunrun, it can help to widen the lens and compare it with other opportunities that fit different risk and quality profiles. The Simply Wall St Screener gives you a fast way to filter by balance sheet strength, income focus, or higher risk reward setups so you can build a watchlist that actually matches your approach.
- If capital preservation ranks high for you, start with a shortlist of resilient businesses by reviewing our 31 resilient stocks with low risk scores that may better handle economic shocks.
- Income focused readers who want yield plus staying power can scan a curated pool of companies by checking out the 7 dividend fortresses that could help anchor a cash flow oriented portfolio.
- Those hunting for mispriced potential can cast a wider net by reviewing a 16 high quality undiscovered gems that might not yet be widely followed but still show solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com