
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Canadian Pacific Kansas City (TSX:CP) Could Be 11% Undervalued Following Guidance And Capex Reset
Event reset for Canadian Pacific Kansas City
Canadian Pacific Kansas City (TSX:CP) reaffirmed its full-year outlook for revenue ton-mile and earnings growth while trimming its 2025 capital spending plan to support free cash flow and shareholder payouts.
The guidance update lands as diesel costs and energy supply worries pressure freight operators, putting CPKC's transcontinental rail network in sharper focus for investors who are comparing rail to long-haul trucking.
Recent trading has been choppy. The share price is down 5.0% over the past month, but it still shows a 21.7% year-to-date share price return. The 1-year total shareholder return of 22.0% points to momentum that long-term holders of Canadian Pacific Kansas City may be watching closely.
Scan for other freight and infrastructure operators showing similar fuel efficiency and cross-border momentum by reviewing the hand picked 39 power grid technology and infrastructure stocks alongside Canadian Pacific Kansas City.
Canadian Pacific Kansas City appears to be a solid freight engine, with reaffirmed growth guidance and a cross-border network that benefits from higher diesel costs. The open question is whether that strength is already fully priced into the stock.
Most Popular Narrative: 11% Undervalued
Canadian Pacific Kansas City last closed at CA$124.50, while the most followed narrative pegs fair value closer to CA$139.53. This frames the current pricing debate around whether the network and cost discipline are fully reflected in the share price.
Expansion of the north south three country network into underpenetrated Mexico and U.S. South corridors for grain, potash, LPGs and refined fuels positions CPKC to capture share from trucking and short sea, supporting durable volume growth and higher revenue over many years.
See why 9 investors see Canadian Pacific Kansas City as 11% undervalued.
Result: Fair Value of CA$139.53 (UNDERVALUED)
Still, the bullish Canadian Pacific Kansas City narrative can crack if North American freight demand softens or if trade and tariff shifts disrupt key cross border flows.
Find out about the key risks to this Canadian Pacific Kansas City narrative.
Another View on Canadian Pacific Kansas City’s Value
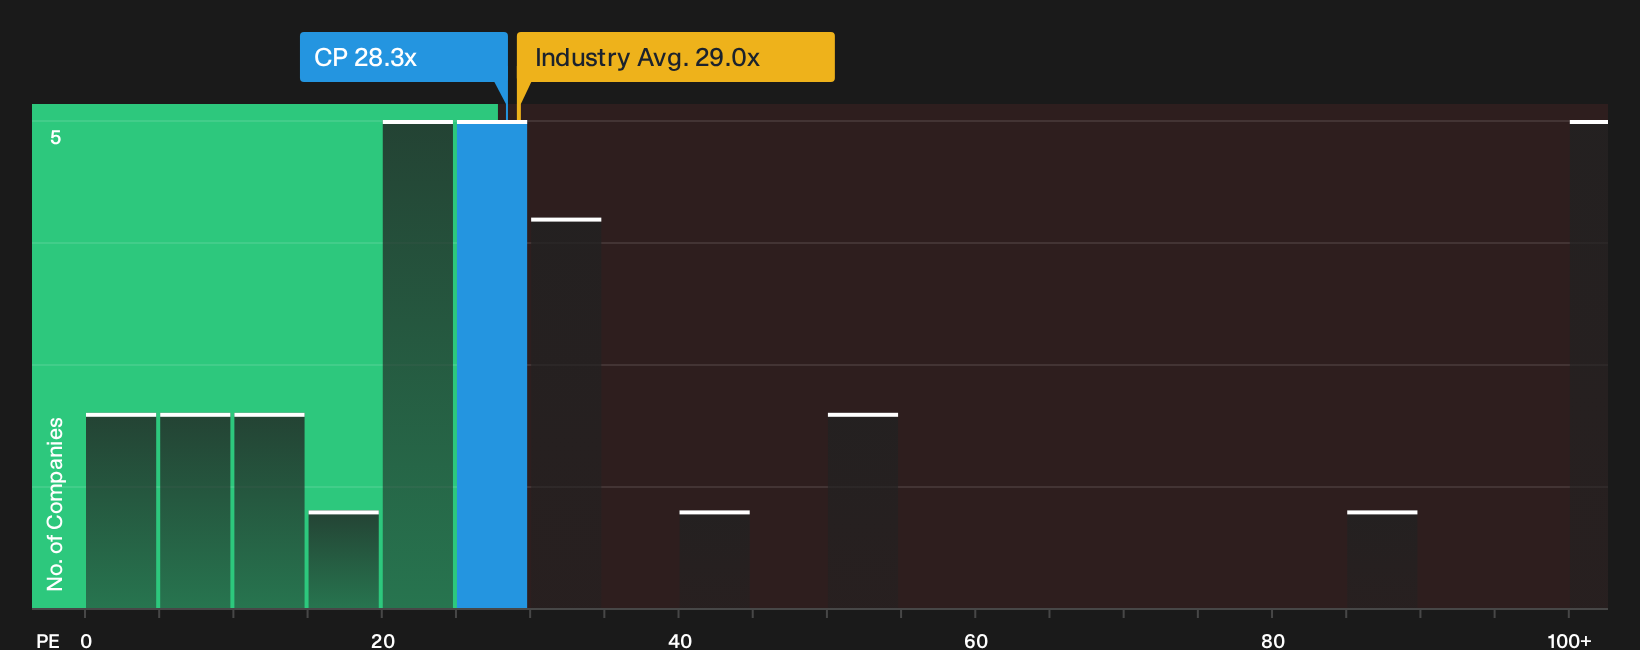
On simple P/E math, Canadian Pacific Kansas City looks expensive compared with some benchmarks. The stock trades around 28.3x earnings, above the estimated fair ratio of 23.4x and higher than the peer average of 26.5x, even though it sits below the broader North American transportation group at 30.6x. That mix signals less margin for error if sentiment or earnings expectations cool.
Our P/E based fair ratio shows how quickly the market could shift its view of Canadian Pacific Kansas City if growth assumptions change. It is worth testing whether that richer multiple still fits your own scenario for the business, or whether it points to more valuation risk than comfort today. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Canadian Pacific Kansas City so far. If you want to move quickly and build your own stance, consider weighing both sides of the story with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Canadian Pacific Kansas City?
If Canadian Pacific Kansas City has sharpened your focus on quality, do not stop here. Broaden your watchlist and pressure test your thesis against fresh opportunities.
- Target potential bargains by scanning the 5 high quality undervalued stocks that combine stronger fundamentals with pricing that may still lag underlying business quality.
- Strengthen your income stream by reviewing the 1 dividend fortresses that can help you assess higher yield opportunities with more resilient payout profiles.
- Dial back risk by filtering for the 8 resilient stocks with low risk scores and compare how these steadier candidates stack up against your current portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com