
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Indian Dividend Stocks With Yield Up To 4%
Indian dividend stocks are back in focus after the Sensex recently slumped as rising US bond yields and higher oil prices pushed borrowing costs and inflation worries to the forefront. Many investors are now looking for steadier cash returns from well covered payouts instead of relying only on share price swings. This article highlights three high yielding Indian dividend payers from our filter that screens for income strength and stability.
The three dividend stocks covered below are only a sample, and the full screen identifies 44 more income ideas with similarly solid payout stories that are not unpacked in this article.
If you want to identify, compare, and analyze the highest conviction yield opportunities that passed this filter, go straight to the Dividend Powerhouses (3%+ Yield) screener.
Emami (BSE:531162)
Overview: Emami is a Kolkata based personal and healthcare products group whose flagship brands generate steady cash flows that underpin its dividend profile.
Operations: Emami generates about ₹39.1b from personal and healthcare products, with roughly ₹32.5b from India and ₹6.6b from international markets.
Market Cap: ₹170.6b
For income investors, Emami’s long established consumer portfolio matters because recurring purchases of everyday brands can translate into consistent dividend firepower.
"Analyst consensus expects portfolio revamps in male grooming and hair care (Smart & Handsome, Kesh King) to revive growth, but this may be understated. With multiple simultaneous launches, deep research-driven product improvements, celebrity endorsements, and cross-channel D2C and offline targeting, Emami is positioned not just to regain share, but to drive step-change category expansion, leading to above-trend revenue acceleration and faster share gains than the market currently discounts."
What happens to Emami’s dividend strength if a single key factor quietly shifts the balance between higher volumes and future margin pressure.
That quiet shift is exactly what the full narrative for Emami unpacks, showing where dividend strength could decouple from headline growth expectations.

Bhansali Engineering Polymers (BSE:500052)
Overview: Bhansali Engineering Polymers manufactures ABS, SAN and related thermoplastic resins for autos, appliances and electronics, using this steady resin demand to underpin its high dividend profile.
Operations: Bhansali Engineering Polymers generates about ₹14.4b in revenue from manufacturing ABS and SAN resins, with additional contribution from trading activities.
Market Cap: ₹31.6b
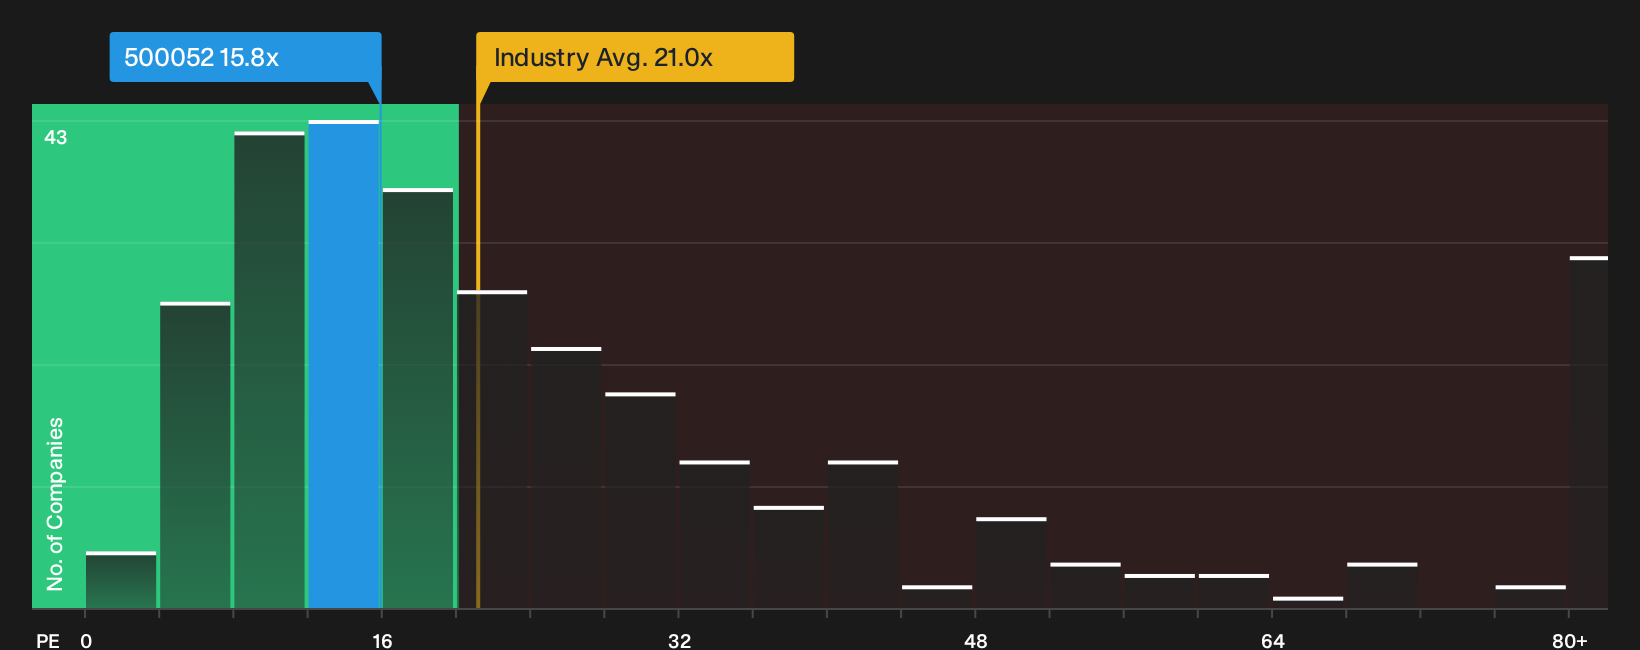
Bhansali Engineering Polymers pays a 3.15% yield and trades on a 15.8x P/E, below both the broader Indian market and Chemicals peers. Recent Q1 FY2026-27 numbers indicate stronger resin demand and higher net income that support ongoing payouts, although the quality of that dividend depends on how one unseen funding pressure plays out.
That funding pressure is the hinge, and the 2 key rewards and 1 important major warning sign shows whether Bhansali Engineering Polymers’ yield is quietly compensating you for it.
Gujarat Energy (NSEI:GUJENERGY)
Overview: Gujarat Energy supplies piped natural gas and CNG across several Indian states, using its large regulated network to fuel households, businesses and vehicles.
Operations: Gujarat Energy generates most of its ₹273.1b in revenue from city gas distribution of about ₹196.4b and gas trading of about ₹194.9b in India, partly offset by inter segment eliminations of about ₹119.8b.
Market Cap: ₹221.2b
For a yield focused investor, Gujarat Energy matters because its regulated city gas network throws off recurring cash flows that can underpin a 3%+ payout. A growing CNG footprint may allow that income stream to expand rather than just hold steady.
"Sustained policy and consumer momentum towards cleaner fuel usage and rapid urban expansion are supporting strong double-digit growth in CNG volumes, with Q1 FY '26 seeing 12% YoY CNG volume increase and the company expecting to outpace even last year's 11% growth due to robust CNG vehicle additions and strategic infrastructure investments."
What happens to Gujarat Energy’s dividend dependability if a single pressure on future funding costs quietly squeezes the cushion behind those payouts.
That squeeze is exactly what the full narrative for Gujarat Energy reveals, showing where funding costs could either cap dividend growth or accelerate Gujarat Energy’s income story.

Seeking Fresh Alternatives Beyond Dividends
Dividend payers can be a strong anchor, but breakout ideas do not wait. Momentum shifts, prices move, information decays. Scan fresh contenders before the crowd and act now.
- Spot resilient compounders early by running the 230 resilient stocks with low risk scores and focusing on businesses designed to hold up when volatility increases.
- Back structural themes with staying power by checking the 39 power grid technology and infrastructure stocks while grid upgrades and electrification trends remain less widely followed.
- Explore the next wave of automation by reviewing the 93 robotics and automation stocks and identifying potential opportunities in that area.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com