
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Renewable Energy Stocks With Direct Exposure to Energy Security Spending
Energy supply risks, price swings and new government rules are colliding to reshape where capital flows next. That mix is creating fresh openings and fresh pitfalls for anyone watching global renewable energy and grid infrastructure stocks. This article walks through three large cap companies from our Global Renewable Energy and Grid Infrastructure screener that appear most exposed to the latest energy security shock, and explains how that exposure could either help or hurt their share prices over time.
The three stocks discussed below are only a first pass, and the full screen flags 44 more large caps with grid and renewables angles that could matter just as much for your portfolio decisions.
If you want to identify patterns across the full set and analyze which tickers best fit your own thesis on energy security, head straight into the Global Renewable Energy and Grid Infrastructure screener.
Vestas Wind Systems (CPSE:VWS)
Overview: Vestas Wind Systems designs, manufactures, installs, and services onshore and offshore wind turbines worldwide, giving investors pure-play exposure to utility-scale clean power buildouts.
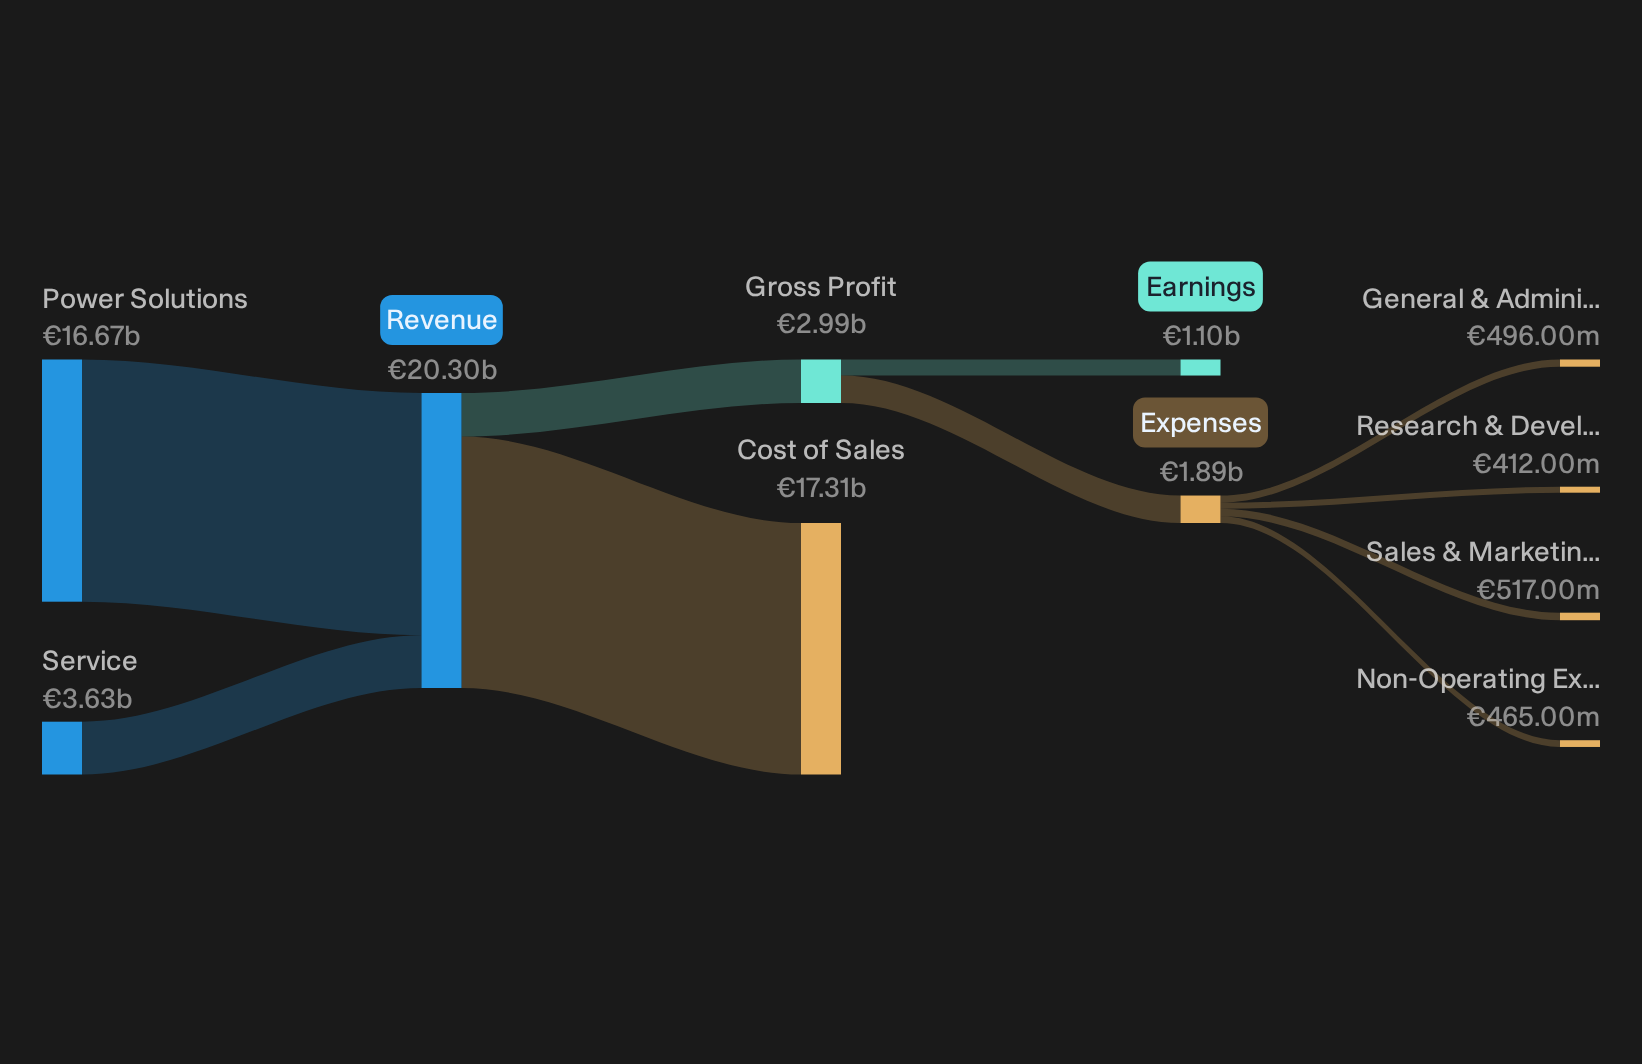
Operations: The business generates about €16.7b from Power Solutions and €3.6b from Service, tying most revenue directly to wind project build and upkeep.
Market Cap: DKK202.5b
For anyone focused on energy security and grid upgrades, Vestas Wind Systems sits at the intersection of physical wind capacity and policy-backed spending.
"Policy support in key markets and global grid reforms are driving higher demand, expanding Vestas' growth opportunities and top-line potential."
What happens to that opportunity set depends heavily on how one persistent pressure on pricing and margins ultimately resolves.
That margin pressure is only half the story, and the full narrative for Vestas Wind Systems reveals how Vestas Wind Systems could turn policy tailwinds into accelerating earnings power despite pricing strains.
Nordex (XTRA:NDX1)
Overview: Nordex designs, builds, and services large onshore wind turbines worldwide, giving direct exposure to utility scale renewable power projects.
Operations: Nordex generates about €7.2b from Projects and €900.7m from Service, with smaller consolidation adjustments, tying most income to turbine delivery.
Market Cap: €9.6b
Nordex matters in this energy security screen because every turbine it delivers feeds directly into the clean power capacity governments are now racing to add.
"Strong and rising order intake (up 83% YoY in Q2) and record order backlog (€14.3bn), driven by robust demand in core European markets and ongoing project pipeline acceleration, are closely linked to multi-year revenue trends as electrification and decarbonization efforts expand globally."
What happens to future profitability now rests on how one unresolved cost and financing pressure interacts with that expanding project pipeline.
That open question on costs and financing is exactly what the full narrative for Nordex unpacks, showing where Nordex risk may be masking real upside potential.

SMA Solar Technology (XTRA:S92)
Overview: SMA Solar Technology supplies PV and battery inverters plus EV charging gear that connect solar, storage and electrification directly into power grids.
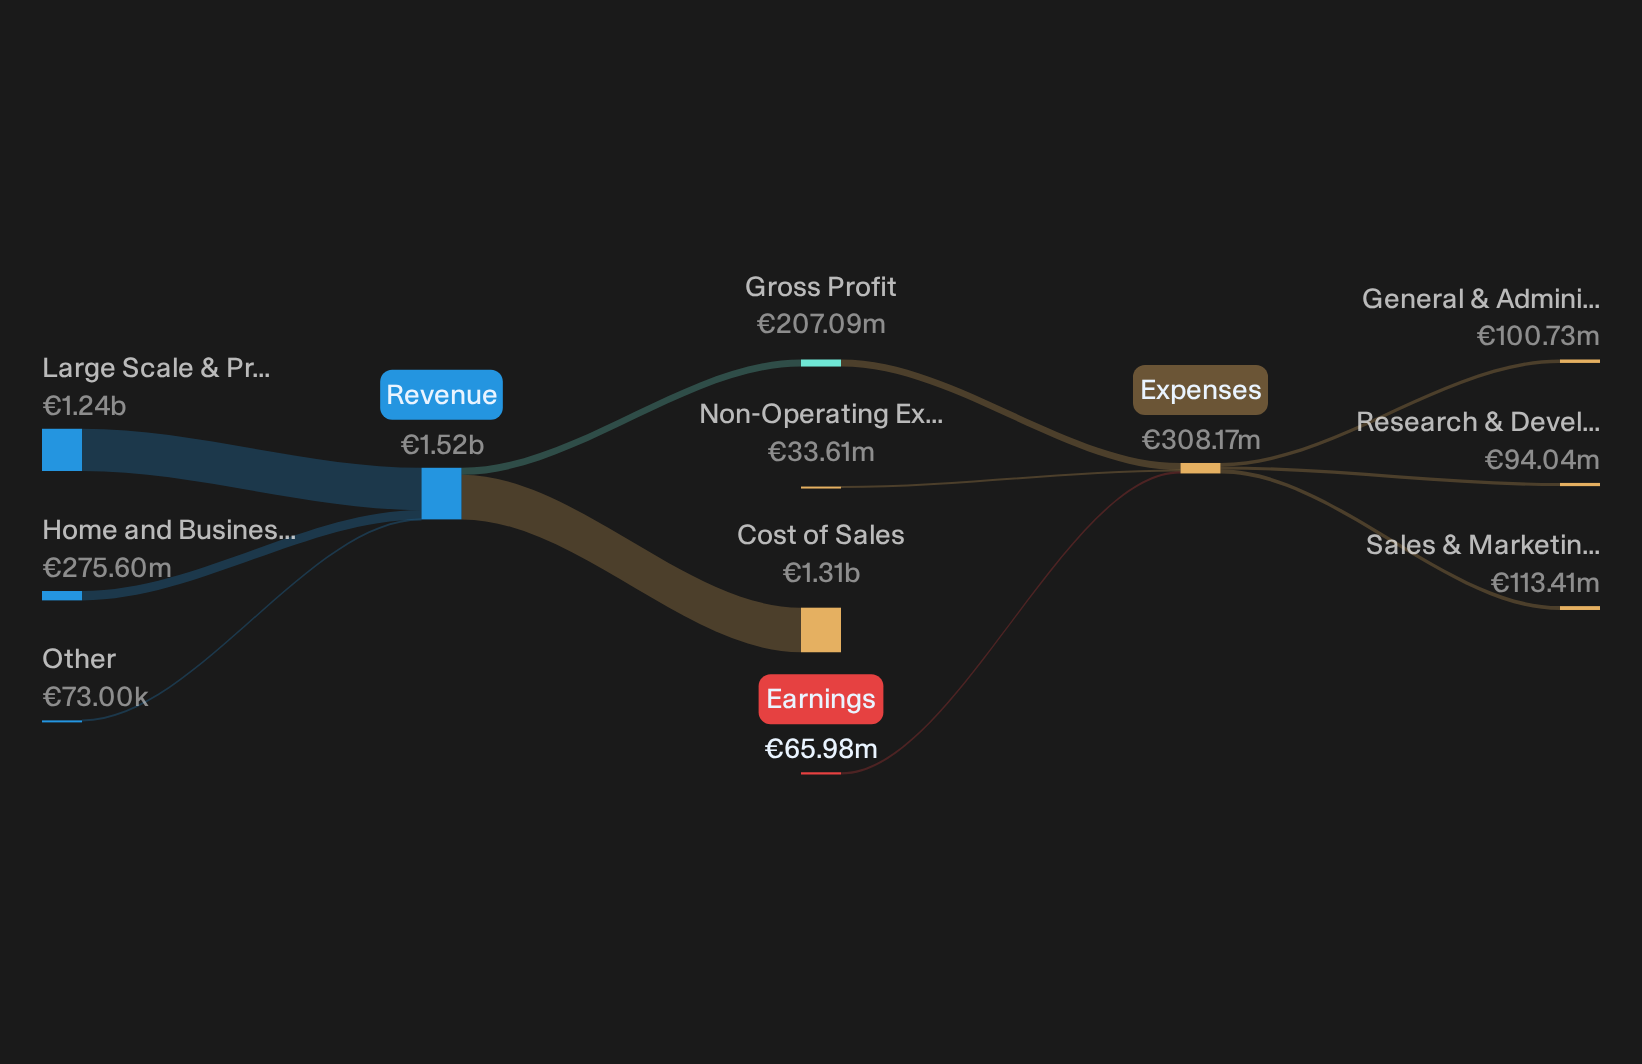
Operations: SMA Solar Technology generates about €275.6 million from Home and Business Solutions and €1.24 billion from Large Scale and Project Solutions.
Market Cap: €2.03 billion
SMA Solar Technology matters in this screener because its hardware and software sit where rooftop panels, big solar farms and batteries plug into real world grids.
"Heightened price competition from Asian inverter manufacturers in EMEA, especially in the premium/pv-only segment of HBS, is causing significant margin compression and undermining net margins, as SMA is forced to contemplate price cuts and additional restructuring."
The way that pricing pressure interacts with demand for grid-forming, storage-ready solutions could influence how much potential upside SMA Solar Technology captures.
That tension between pricing pressure and grid demand is exactly what the full narrative for SMA Solar Technology unpacks, highlighting where SMA Solar Technology risk could be masking accelerating upside potential.
Curious About High Conviction Alternatives
Fresh opportunities can move from quiet to flying under the radar fast. Scan these curated ideas before momentum is fully caught by the crowd and act now.
- Target reliable cash generators and stress test your income plan using a curated 158 dividend fortresses that screens for strength before yields start dropping.
- Hunt for under-followed winners and sift through a curated 619 high quality undiscovered gems that highlights quality businesses still under the radar for now.
- Explore the build out of critical materials and filter a focused 17 top copper producer stocks set before copper producers with momentum get fully priced in.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com