
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Crane (CR) Earnings Strength Puts Fair Value Back In Focus
Crane (CR) is back in focus after reporting Q2 2026 results that featured 25.6% year over year net sales growth and a record Aerospace & Advanced Technologies backlog of US$1.27b.
Crane's recent Q2 update has landed against a backdrop of mixed share price moves, with a 1-day share price return of 1.02% and a 7-day share price return of 3.59% contrasting with a 90-day share price return that declined 8.61%. At the same time, the 1-year total shareholder return of 14.75% and the very large 5-year total shareholder return of about 2.5x indicate that longer term holders have seen strong compounding, while recent momentum has cooled after a strong multi year run.
Scan for more industrials with Crane-like momentum in engineered products and aerospace exposure by reviewing the curated 39 power grid technology and infrastructure stocks in one pass.
Bulls point to Crane’s record aerospace backlog and the raised 2026 earnings guidance. Bears highlight the recent 90-day share price pullback after a multi-year run. Which story does the current valuation appear to support?
Most Popular Narrative: 14% Undervalued
Crane’s most followed narrative pegs fair value at $238, a touch above the last close at $204.33. This frames the recent pullback as a valuation gap rather than a finished story.
Crane's recent acquisition of PSI (Druck, Panametrics, Reuter-Stokes) positions the company to capture rising demand for advanced sensing and fluid control in both aerospace and process industries, directly benefiting from infrastructure modernization and growing automation supporting sustained revenue and future margin expansion.
See why 5 investors see Crane as 14% undervalued.
Result: Fair Value of $238 (UNDERVALUED)
Still, the Crane story can change quickly if European chemical demand stays weak or if recent PSI acquisitions deliver integration progress that is slower than expected.
Find out about the key risks to this Crane narrative.
Another View on Crane’s Valuation
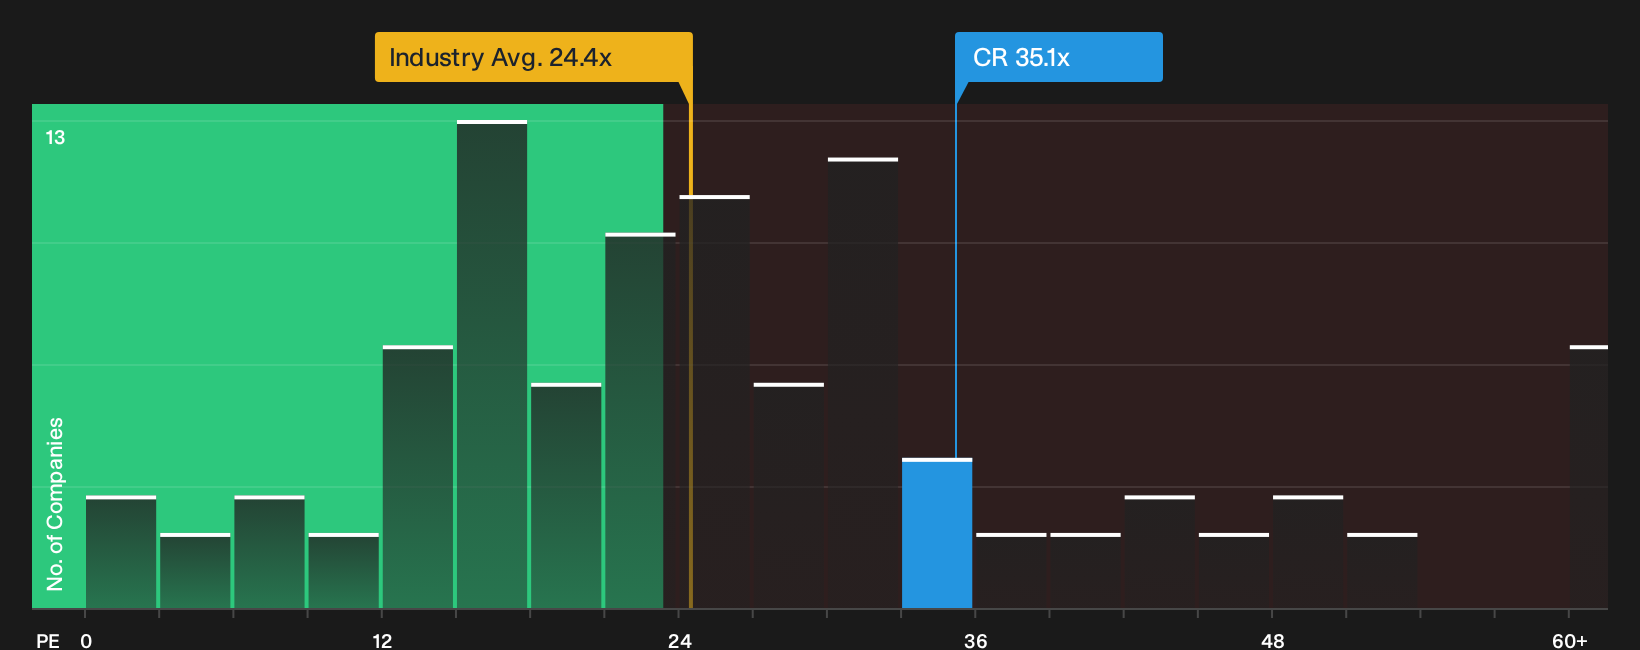
While the narrative and fair value estimate of $238 suggest Crane is modestly undervalued, the P/E picture looks far less forgiving. The shares trade on 35.1x earnings, compared with 24.6x for the US Machinery industry, 30.6x for peers, and a fair ratio of 24.1x. That gap points to real valuation risk rather than a clear bargain. Which signal should investors prioritize?
To pressure test this premium against the earnings profile and industry context, it helps to walk through a full valuation breakdown in one place, then determine how much multiple risk you are prepared to accept at today’s price. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Crane so far. If you want to move fast and form your own stance using the same core data, start by weighing its 3 key rewards and 1 important warning sign.
Looking for more Crane-like investment ideas?
If Crane has sharpened your thinking, do not stop here. Cast a wider net so you are not relying on a single storyline.
- Target potential mispricings by scanning a focused group of companies that screen as 30 high quality undervalued stocks before the crowd fully catches on.
- Build a steadier income stream by reviewing businesses that qualify as 7 dividend fortresses and may help reinforce your portfolio payouts.
- Reduce portfolio stress by concentrating on companies that pass tougher quality checks in our 31 resilient stocks with low risk scores and see which ones deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com