
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Spyre Therapeutics (SYRE) Dropped, So What Is Behind The Latest Attention?
Spyre Therapeutics (SYRE) came into focus after reporting positive 12-week induction data from Part A of its Phase 2 SKYLINE trial for SPY003 in ulcerative colitis, alongside biological proof of concept across its IBD portfolio.
Despite the positive SPY003 readout, Spyre Therapeutics shares recently pulled back, with the 30-day share price return down 17.33% and the 7-day move down 3.29%. However, the year-to-date share price return sits at 188.33%, and the 1-year total shareholder return is very large, signalling strong momentum over the longer stretch even as near-term enthusiasm cools.
Capitalize on the momentum around Spyre Therapeutics by scanning a curated group of biotech and healthcare specialists with resilient balance sheets and fundamentals through our list of solid balance sheet and fundamentals (23 results).Spyre Therapeutics now has clinical momentum and a rich IBD pipeline, yet the share price has cooled after a steep run. Is this still a quality story at a stretched valuation, or has enthusiasm already been priced in?
Most Popular Narrative: 27% Undervalued
Spyre Therapeutics last closed at $88.17, while the most followed narrative implies a fair value of $120.08. The story currently prices in a sizeable gap between trial potential and today’s market value.
The plan to use co formulated α4β7, TL1A and IL 23 antibodies with extended half life and high concentration formulations for less frequent subcutaneous dosing, if it translates into high uptake among IBD prescribers, could support premium pricing and help net margins over time.
See why 1 investors see Spyre Therapeutics as 27% undervalued.
Result: Fair Value of $120.08 (UNDERVALUED)
Still, the Spyre Therapeutics story depends heavily on delivering stronger SKYLINE and SKYWAY data, while also managing insider selling that has already coincided with sharp single day share declines.
Find out about the key risks to this Spyre Therapeutics narrative.
Another View on Spyre Therapeutics Valuation
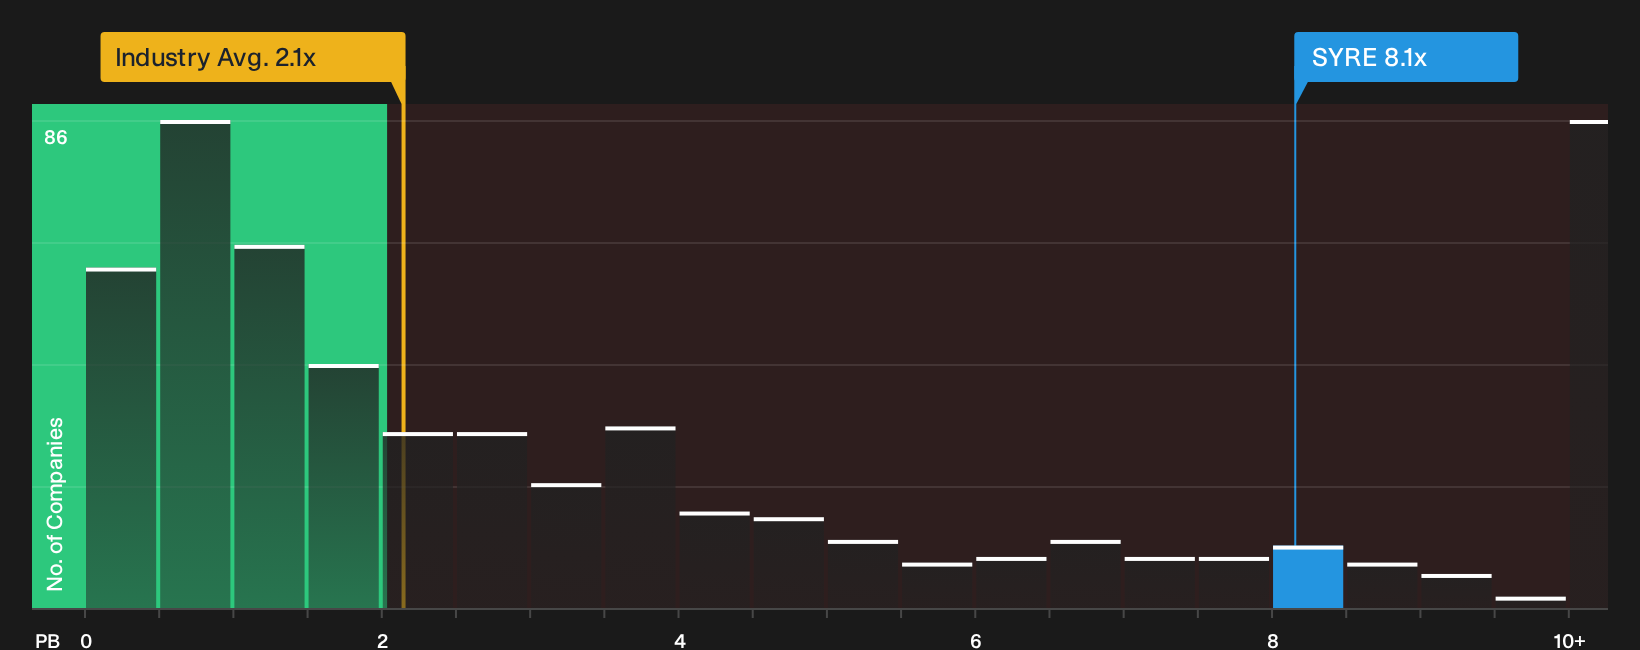
The analyst narrative frames Spyre Therapeutics as about 27% undervalued, yet the share price tells a different story when using a simple P/B lens. SYRE trades at 8.1x book value compared with 2.2x for the wider US biotech group and 10.9x for close peers.
That gap suggests investors already pay a heavy premium to the sector and a discount to direct comparables, which leaves limited room for error if clinical or funding assumptions change. If the market were to move toward a lower fair ratio in the future, would that still fit your risk appetite for a pre revenue biotech?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Spyre Therapeutics can create noise, so move quickly, review the numbers for yourself, and weigh both sides of the story through 1 key reward and 5 important warning signs
Looking for more investment ideas beyond Spyre Therapeutics?
If Spyre Therapeutics has caught your attention, consider broadening your watchlist with a few targeted stock ideas that could help refine your overall portfolio positioning.
- Explore potential mispricings by scanning companies that screen well on quality and valuation through our 30 high quality undervalued stocks.
- Review businesses that currently offer robust payout profiles to help strengthen your income stream using our 7 dividend fortresses.
- Focus on businesses with cleaner finances and sturdier fundamentals to prioritize resilience via our 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com