
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Vericel (VCEL) Dropped, So What Is Driving Attention Now?
Vericel (VCEL) has been drawing attention after recent trading performance, with the share price closing at US$38.79. The stock is higher compared with the past year, yet has retreated over the past month.
Short-term momentum for Vericel has cooled, with the share price down 3.6% over one day and about 10% over the past month. This comes even though the year-to-date share price return is positive and the 1-year total shareholder return of roughly 30% points to a much stronger longer-term payoff profile than recent trading suggests.
Scan beyond Vericel to see how it compares with other medical and biotech names showing resilient fundamentals using our hand-picked list of solid balance sheet and fundamentals (23 results) for potential ideas.
Vericel now trades well below the average analyst price target, even after a strong 1 year run and a softer recent patch. Is that a meaningful discount or a fair warning label on the valuation?
Most Popular Narrative: 32% Undervalued
Against the latest close at $38.79, the most followed narrative for Vericel points to a fair value closer to the mid $50s, which sets a very different framing to the recent pullback.
Ongoing operational initiatives such as automation, new manufacturing facility ramp (with expected commercial manufacturing for MACI in 2026), and salesforce expansion are increasing plant utilization and operational leverage, supporting steady gross margin expansion and bottom-line (EBITDA) growth as scale increases.
See why 8 investors see Vericel as 32% undervalued.
Result: Fair Value of $57.14 (UNDERVALUED)
Still, Vericel’s heavy reliance on just three therapies, along with the rising cost base tied to salesforce and manufacturing expansion, could quickly challenge this optimistic fair value story.
Find out about the key risks to this Vericel narrative.
Another View on Vericel’s Valuation
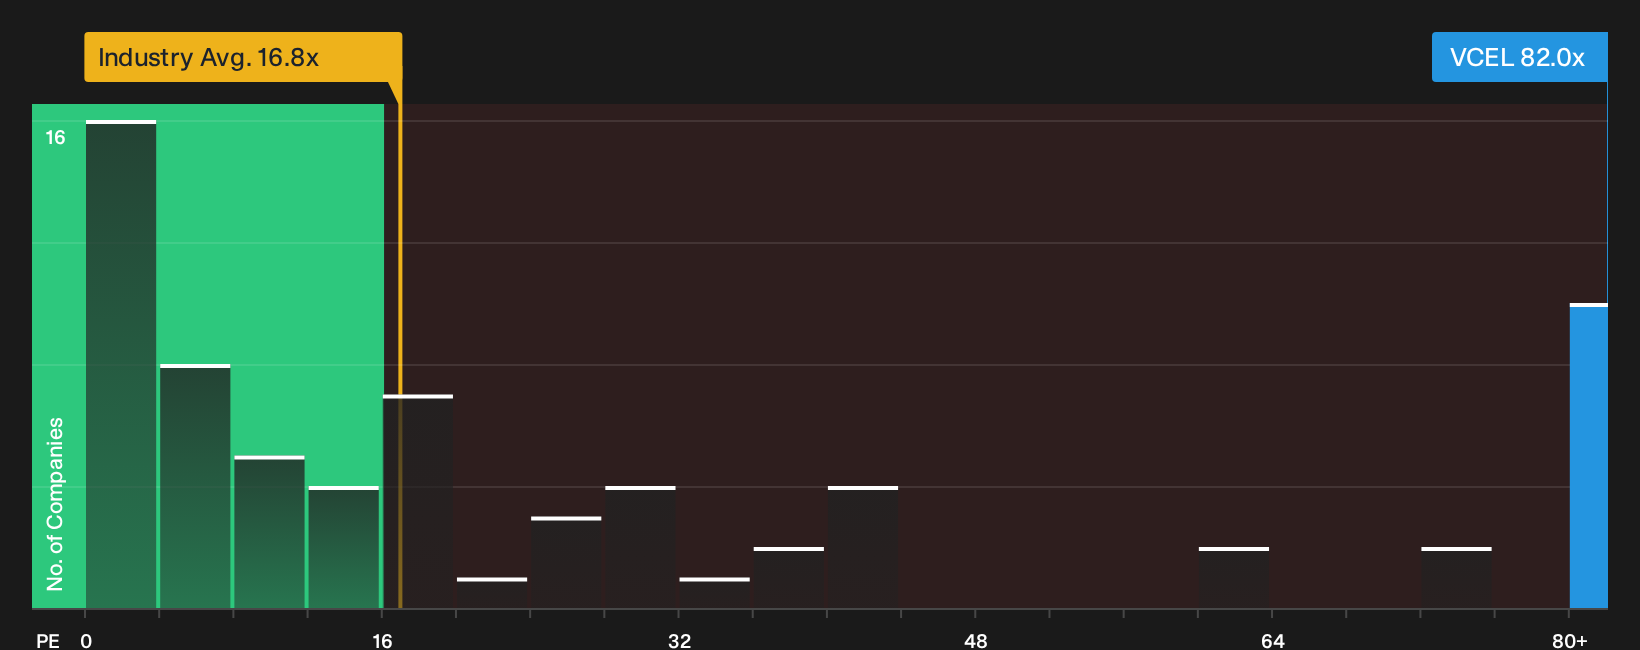
That fair value narrative around $57.14 leans heavily on long term earnings forecasts. The market today is telling a different story. Vericel trades on a P/E of 82x, compared with an estimated fair ratio of 23.5x, the US Biotechs industry at 17.6x, and peer average of 19x.
Such a wide gap suggests investors are paying a premium price for projected growth, which raises the question of how much execution risk you are willing to accept for that kind of multiple.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
That valuation tension around Vericel can look either exciting or uncomfortable depending on your risk appetite, so move quickly, test the assumptions yourself, and weigh the 3 key rewards.
Looking for more investment ideas beyond Vericel?
If Vericel has your attention, broaden your watchlist with a few focused sets of opportunities that match different risk profiles and income goals.
- Target potential mispricing by reviewing companies our data tags as better quality at appealing entry points through the 30 high quality undervalued stocks.
- Build steadier income streams by scanning for payout-focused opportunities in the 7 dividend fortresses.
- Dial back risk without parking cash on the sidelines by filtering for resilient businesses using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com