
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Trend Brand Rollouts Just Shift Ulta Beauty's (ULTA) Investment Narrative?
- Flower Knows and COSRX announced major U.S. expansion through Ulta Beauty this month, moving curated product ranges from Ulta.com into hundreds of physical stores, including Flower Knows placements in 450 locations and a feature in Ulta Beauty's Just Dropped Beauty platform.
- The broadened in-store footprint of these trend driven brands gives Ulta Beauty fresh product stories across color cosmetics and lip care, which can influence traffic, merchandising productivity, and how effectively the retailer appeals to younger, beauty engaged shoppers.
- We will look at how Ulta Beauty's investment narrative around exclusive brands is influenced by Flower Knows' Just Dropped Beauty placement.
Scan how Ulta Beauty's exclusive brand momentum compares with other retailers leaning on niche labels through our hand picked 16 high quality undiscovered gems that are poised to benefit from similar under the radar demand.
Ulta Beauty Investment Narrative Recap
Owning Ulta Beauty means believing its mix of specialty stores, e-commerce and exclusive brands can keep pulling shoppers in, even as beauty competition tightens and wage, rent and benefit costs keep creeping higher. The biggest near term swing factor is how effectively Ulta Beauty replaces high margin Target shop in shop revenue as that partnership winds down in 2026.
On that front, the Flower Knows and COSRX news looks incremental rather than transformational. These launches support the existing thesis around exclusive and trend driven assortments attracting Gen Z and Millennial shoppers. They do not remove the core risk that store level expenses and ongoing investment in international growth and digital tools could run ahead of sales.
The Flower Knows Just Dropped Beauty feature is most relevant here. It plugs directly into Ulta Beauty’s push toward exclusive and emerging labels that can carry higher margins and deeper loyalty engagement. A curated set of five hero items in 450 stores offers Ulta Beauty a test bed for merchandising, pricing and storytelling inside its own four walls.
For you as a shareholder, the question is how repeatable that model is as a catalyst. If this type of limited time, trend led rollout supports traffic and basket size without meaningfully lifting SG&A per store, it can partially offset pressure from the Target exit and rising store costs. If it fails to scale or loses shopper interest, the risk case around margin squeeze and slower profit growth stays front and center.
What The Current Ulta Beauty Forecasts Assume
Ulta Beauty's narrative projects US$14.9b in revenue and US$1.4b in earnings by 2029, based on analyst expectations for 5.4% yearly top line growth and an earnings increase of about US$200m from US$1.2b today.
Uncover why Ulta Beauty's fair value indicates a 15% potential upside to its current price that may not last much longer.
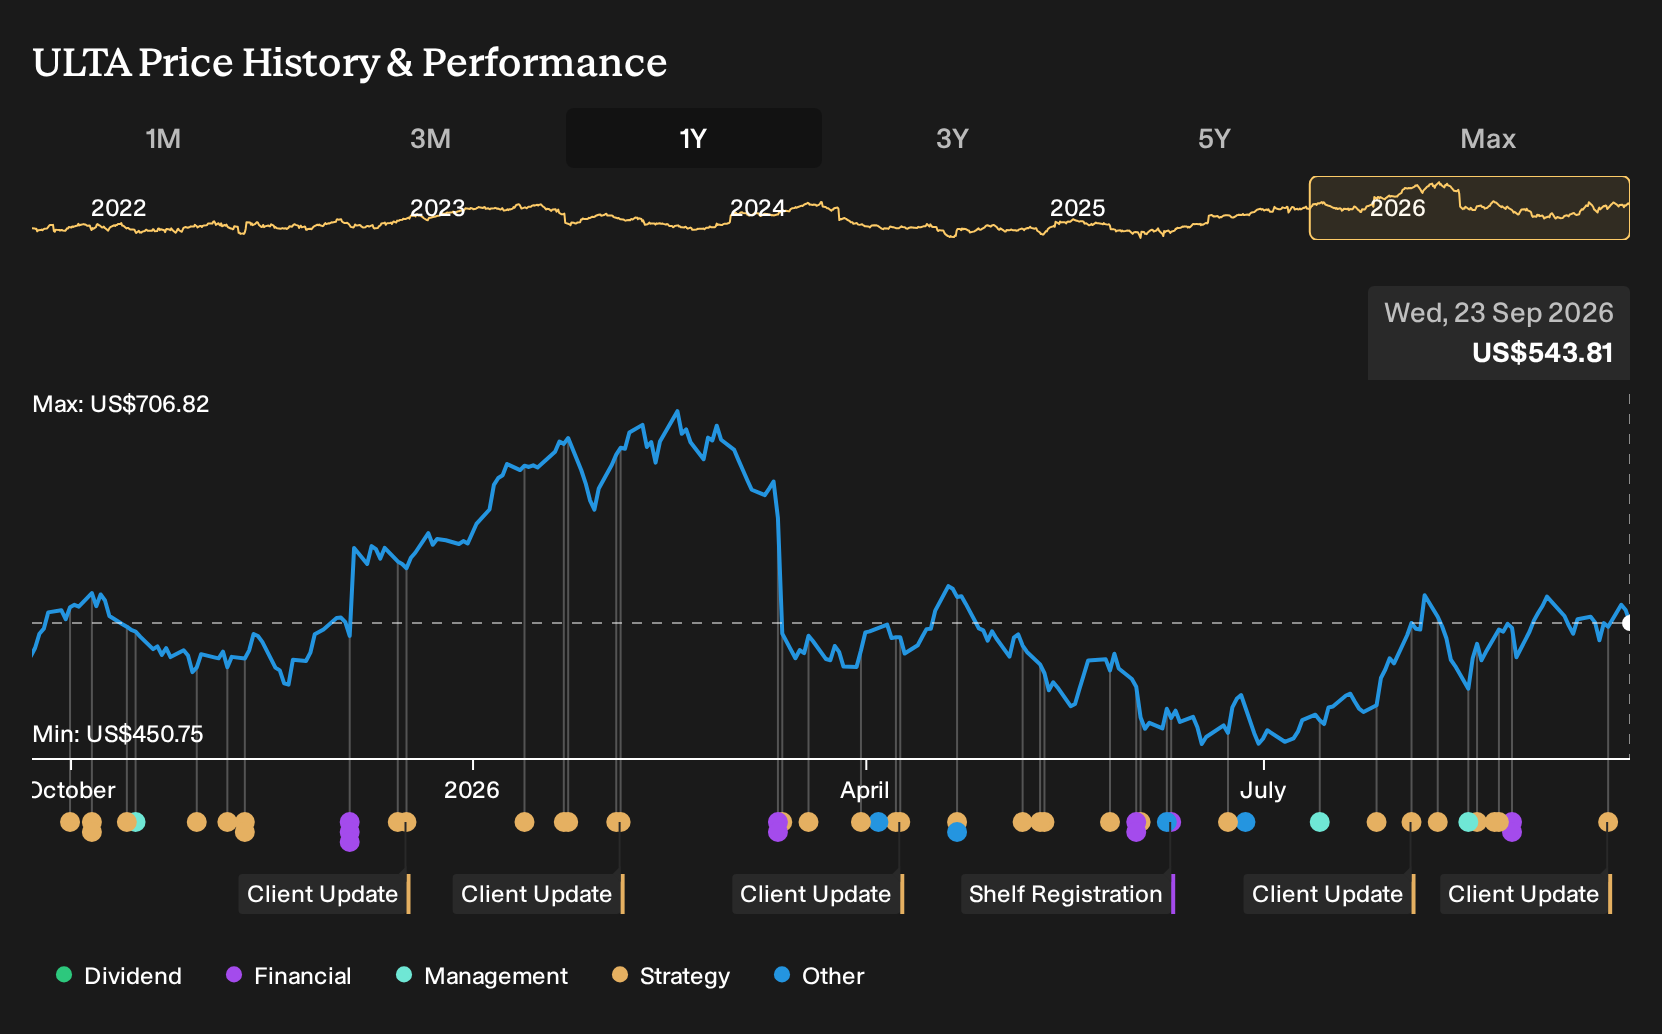
Exploring Other Perspectives
One bearish twist you may want to explore is privacy risk. The most pessimistic Ulta Beauty analysts already assumed slower progress from AI and data efforts, with revenue only reaching about US$14.7b and earnings around US$1.4b by 2029. Those views predate the Flower Knows and COSRX news, so opinions could shift meaningfully from here.
Explore 6 other Ulta Beauty fair value estimates, including one that suggests as much as 27% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ulta Beauty research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ulta Beauty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ulta Beauty's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ulta Beauty?
Once you have a view on Ulta Beauty, it can help to widen your watchlist and compare it with other businesses that fit clear financial themes. The Simply Wall St Screener is built for this kind of side by side work so you can pressure test your thesis against a broader set of opportunities.
- For investors who care most about valuation support, there is a focused set of companies trading on what may be appealing fundamentals through the 30 high quality undervalued stocks.
- If capital preservation and steadier profiles matter more to you than rapid expansion, consider scanning the 31 resilient stocks with low risk scores as a way to spot businesses with more resilient risk scores.
- When you want balance sheets that can absorb shocks and still fund growth plans, filter for companies screened in the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com