
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ASX Penny Stocks Under A$50M Market Cap To Watch
The Australian market is facing a challenging landscape, with the ASX 200 showing signs of strain as oil prices surge past US$100 per barrel and inflation concerns mount. Amidst these broader economic pressures, investors often turn their attention to penny stocks, which represent smaller or newer companies that can offer unique growth opportunities. While the term "penny stocks" may seem outdated, these investments continue to attract interest due to their potential for affordability and growth when backed by strong financials.
Here's a peek at a few of the choices from the screener.
Clover (ASX:CLV)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: Clover Corporation Limited is involved in the production, refining, and sale of natural oils and encapsulated powders across multiple regions including Australia, New Zealand, Asia, Europe, the Middle East, and the Americas with a market cap of A$162.75 million.
Operations: The company's revenue is primarily derived from its Nutritional Oil and Microencapsulated Powders segment, which generated A$97.41 million.
Market Cap: A$162.75M
Clover Corporation Limited, with a market cap of A$162.75 million, has demonstrated significant earnings growth of 49.1% over the past year, surpassing its 5-year average and the broader Chemicals industry. The company is debt-free, enhancing financial stability and reducing risk exposure. Clover's recent earnings report showed an increase in net income to A$10.46 million from A$7.02 million last year, alongside a dividend increase announcement reflecting confidence in cash flow sustainability. Trading at a substantial discount to estimated fair value, Clover presents potential for investors seeking value opportunities within the penny stock segment in Australia.
- Dive into the specifics of Clover here with our thorough balance sheet health report.
- Evaluate Clover's prospects by accessing our earnings growth report.
Civmec (ASX:CVL)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: Civmec Limited is an investment holding company offering construction and engineering services across the energy, resources, infrastructure, marine, and defense sectors in Australia, with a market cap of A$899.49 million.
Operations: The company's revenue is derived from three primary segments: Energy (A$105.69 million), Resources (A$587.11 million), and Infrastructure, Marine & Defence (A$210.18 million).
Market Cap: A$899.49M
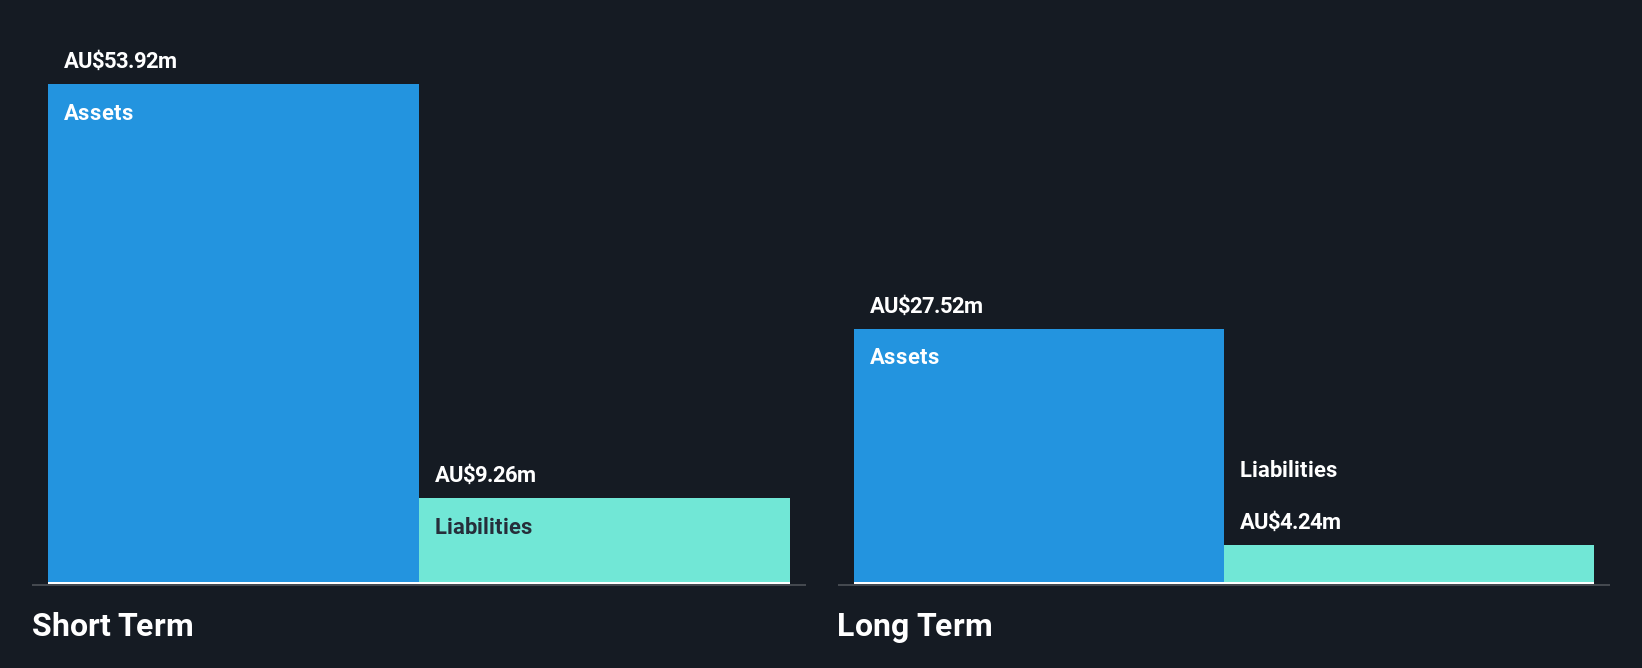
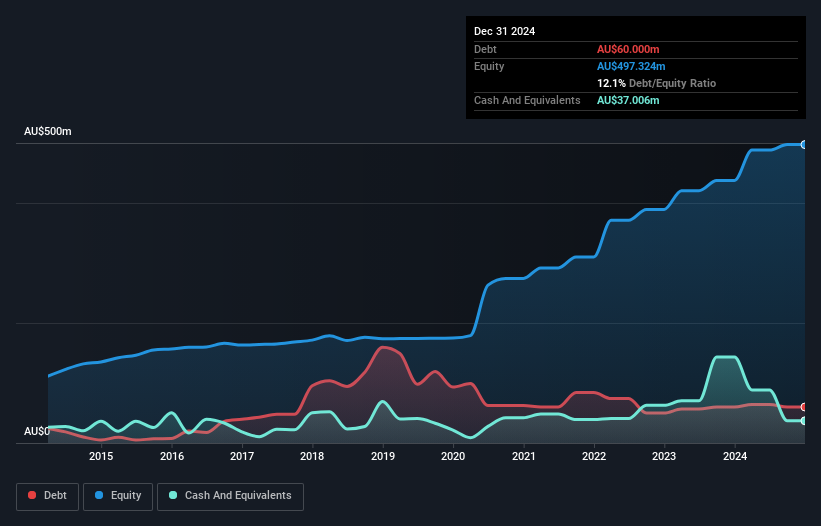
Civmec Limited, with a market cap of A$899.49 million, reported revenue growth to A$902.98 million for the fiscal year ended June 2026. Despite low return on equity at 8.8% and negative operating cash flow affecting debt coverage, Civmec's interest payments are well covered by EBIT at 23.1x. The company's short-term assets exceed both short and long-term liabilities, indicating solid balance sheet management. However, its dividend yield of 3.4% is not well supported by free cash flows, raising sustainability concerns despite recent dividend affirmations and a modest earnings per share increase from continuing operations over the past year.
- Unlock comprehensive insights into our analysis of Civmec stock in this financial health report.
- Explore Civmec's analyst forecasts in our growth report.
Rubicon Water (ASX:RWL)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: Rubicon Water Limited designs, manufactures, installs, and maintains irrigation automation software and hardware across Australia, New Zealand, Asia, and internationally with a market cap of A$57.79 million.
Operations: The company generates revenue of A$61.08 million from its Industrial Automation & Controls segment.
Market Cap: A$57.79M
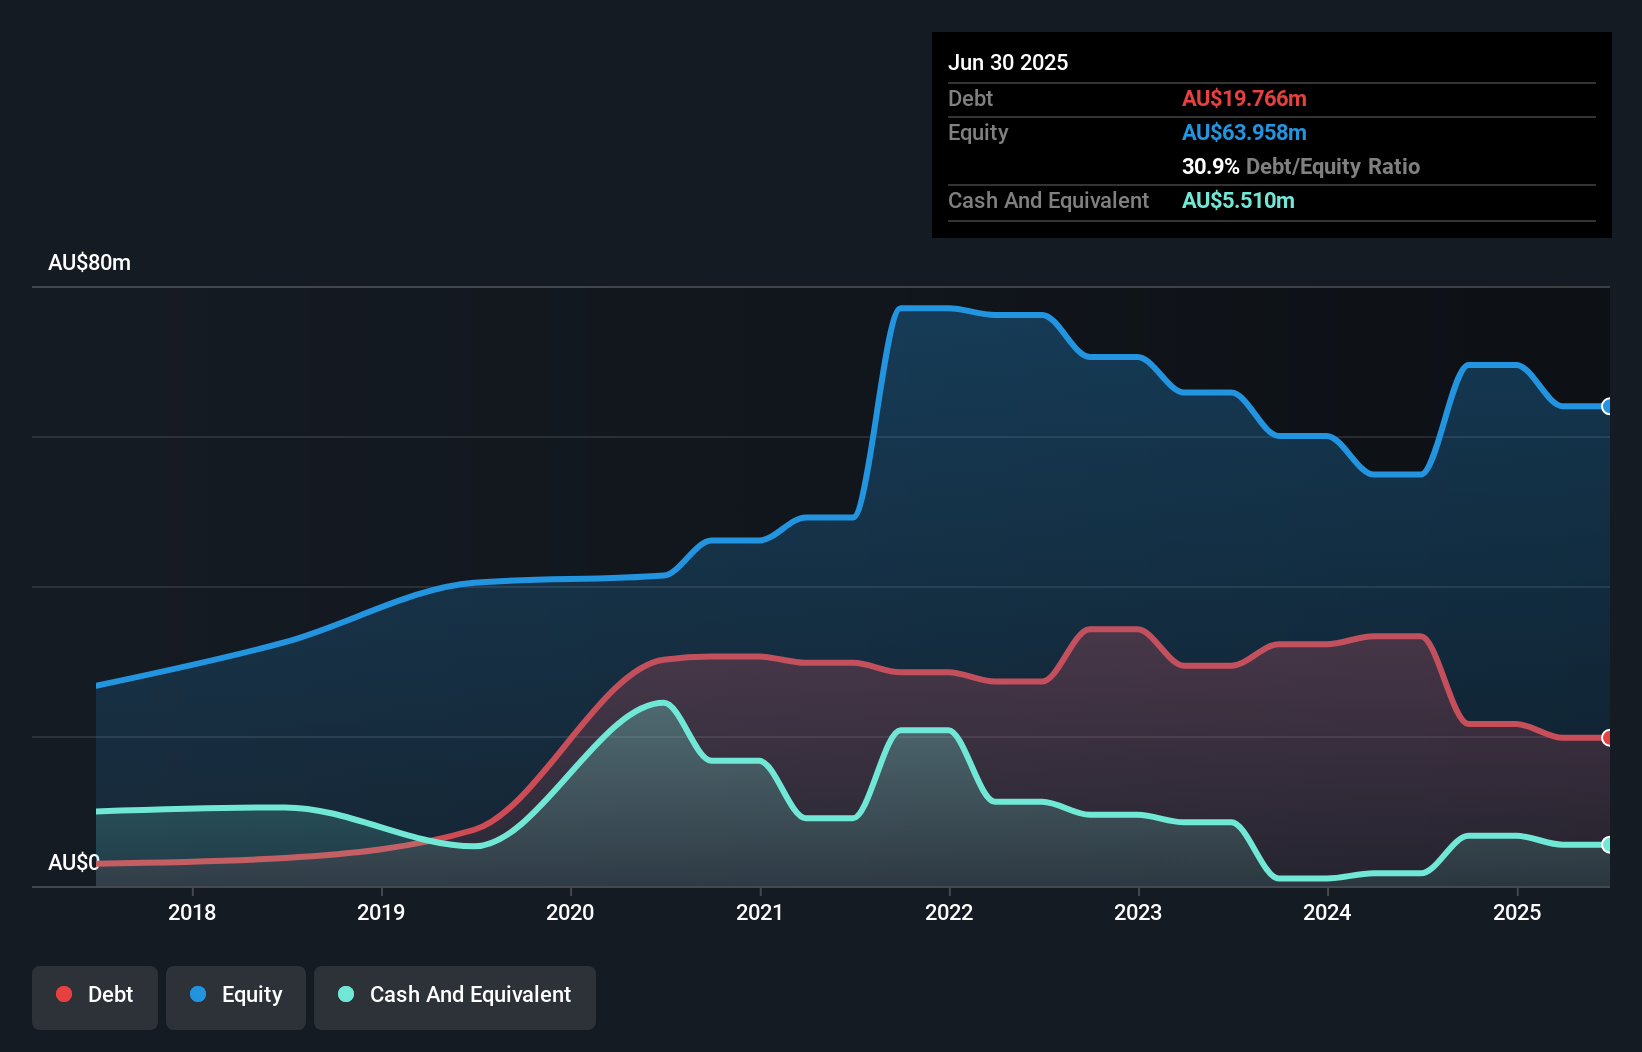
Rubicon Water Limited, with a market cap of A$57.79 million, faces challenges as it reported a net loss of A$15.52 million for the year ended June 2026, despite generating revenue of A$61.08 million from its Industrial Automation & Controls segment. The company's financial health is supported by satisfactory debt levels and seasoned management and board teams. Recent executive changes include the appointment of Lukasz Hansdorfer as CFO following Andrew Bendall's retirement due to health issues. Rubicon continues its international growth trajectory with new contracts like the US$1.4 million Nebraska water stewardship project while maintaining a stable cash runway exceeding three years despite ongoing volatility in share price.
- Jump into the full analysis health report here for a deeper understanding of Rubicon Water.
- Gain insights into Rubicon Water's outlook and expected performance with our report on the company's earnings estimates.
Key Takeaways
- Investigate our full lineup of 394 ASX Penny Stocks right here.
- Ready For A Different Approach? Uncover 27 companies that survived and thrived after COVID and have the right ingredients to survive Trump's tariffs.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com