
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
WeRide (WRD) Wins Spain Permit, Is It Still A Bargain?
WeRide (WRD) moved into focus after securing Spain’s first national permit for Level 4 autonomous passenger vehicles, a regulatory green light that opens deployment preparations in Madrid with Uber and AVOMO.
The regulatory win in Spain comes at a time when WeRide’s share price has been volatile, with a 7 day share price return of 4.46% and a 90 day gain of 6.36%, in contrast to a sharp year to date share price decline of 37.7% and a 1 year total shareholder return down 46.38%.
Scan beyond WeRide and size up other autonomous and AI-focused players that analysts have filtered into 38 profitable AI stocks that aren't just burning cash as potential candidates for solid fundamentals and potentially resilient share price trends.
After the Spain permit-driven bounce, WeRide still trades at a steep discount to analyst targets. Is this where most of the upside sits ahead, or has the bulk of the rerating already played out?
Most Popular Narrative: 58% Undervalued
WeRide’s most followed valuation storyline pegs fair value at $14.09 versus the last close of $5.85, framing a wide gap that hinges on how far and how fast robotaxi fleets scale across key cities.
City level fully driverless permits in Abu Dhabi, together with integration on Uber, give WeRide a reference model for scaling similar arrangements in Dubai, Riyadh and other high fare, driver constrained cities, which could support higher ride volume and service revenue per vehicle.
See why 8 investors see WeRide as 58% undervalued.
Result: Fair Value of $14.09 (UNDERVALUED)
Still, the WeRide narrative hinges on regulators continuing to grant permits and on heavy R&D spending eventually supporting economics that are strong enough to shrink today’s sizeable losses.
Find out about the key risks to this WeRide narrative.
Another View On WeRide’s Valuation
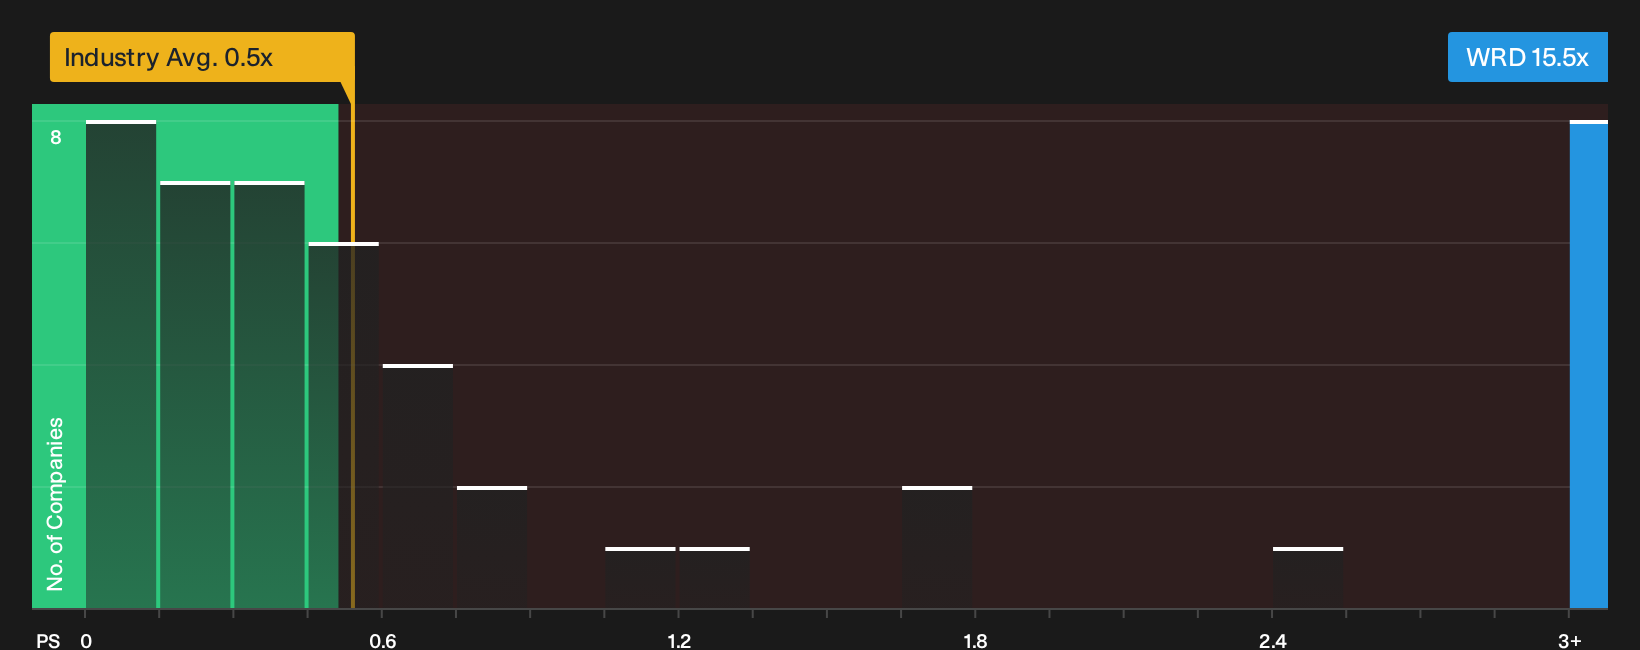
While the prevailing WeRide storyline leans on a fair value of $14.09 and a large discount to that figure, the P/S picture sends a very different signal. WRD trades around 15.5x sales compared with 2.2x for peers, 0.5x for the wider US Auto Components group and a fair ratio of 4.4x, which points to meaningful valuation risk if sentiment cools.
For anyone weighing these opposing signals, the key question is whether WeRide’s growth path and business model are strong enough over time to keep the current P/S multiple from drifting closer to that fair ratio or industry levels.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Still unsure whether recent sentiment around WeRide is too cautious or too optimistic, given the mix of steep drawdown and upbeat narratives? Act quickly, stress test the numbers yourself, and then see how that lines up with 2 key rewards.
Looking for more investment ideas beyond WeRide?
If WeRide has you thinking harder about where risk and reward really line up, use the screener to quickly surface other opportunities before the next move passes you by.
- Spot potential mispricings early and compare them side by side with your watchlist using the 30 high quality undervalued stocks.
- Target resilient balance sheets that can better handle rough patches by filtering for a list of solid balance sheet and fundamentals (23 results).
- Hunt for future leaders before they hit the mainstream by scanning through 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com