
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To FMC (FMC) Global Field Trials
- On September 17, 2026, AgroSpheres and FMC Corporation reported that two proprietary RNA-based bioinsecticide candidates from their existing collaboration had progressed from discovery into global field trial development across the United States, Brazil and Asia, following several years of laboratory, greenhouse and small-scale field-plot testing.
- This step moves FMC's biologicals pipeline closer to potential commercialization and places real-world performance, regulatory progress and future manufacturing requirements under sharper scrutiny for the business.
- We will now look at how FMC's investment narrative could be reshaped by RNA bioinsecticide candidates entering broad global field trials.
Compare FMC's RNA bioinsecticide push with peers that also screen as potential value ideas by scanning our curated list of 30 high quality undervalued stocks across global markets.
FMC Investment Narrative Recap
For FMC, the core belief is that crop protection demand, new proprietary actives and biologicals can offset pricing pressure, regulatory friction and rising generic competition. In the near term, the focus is on stabilising margins, progressing the product pipeline and demonstrating that the existing portfolio can support earnings while the business carries elevated leverage.
The biggest near term catalyst is execution on new products, including the RNA bioinsecticide program, together with cost transformation and working capital discipline. The main risk remains financial strain. FMC has reported losses, interest is not well covered by earnings and the dividend is not supported by profits, which limits the room for missteps.
The collaboration with AgroSpheres, which is moving RNA based bioinsecticide candidates into global field trials, is the clearest operational swing factor tied to this news. It aligns with FMC's goal to increase higher margin biologicals and plant health offerings while differentiating against generics and regulatory pressure on older chemistries.
For catalysts, the trials now need to clear three hurdles: real world performance versus existing chemistries, regulatory progress across the United States, Brazil and Asia, and clarity on eventual manufacturing economics. Any progress in these areas could support the broader thesis that FMC's pipeline and restructuring efforts can justify its discounted P/S multiple.
FMC's narrative projects US$3.9 billion in revenue and US$313.5 million in earnings by 2029. This assumes 6.6% yearly revenue growth and an earnings increase of about US$3.0 billion from current earnings of a US$2.7 billion loss.
Uncover why FMC's fair value indicates a 37% potential upside to its current price that could narrow quickly.
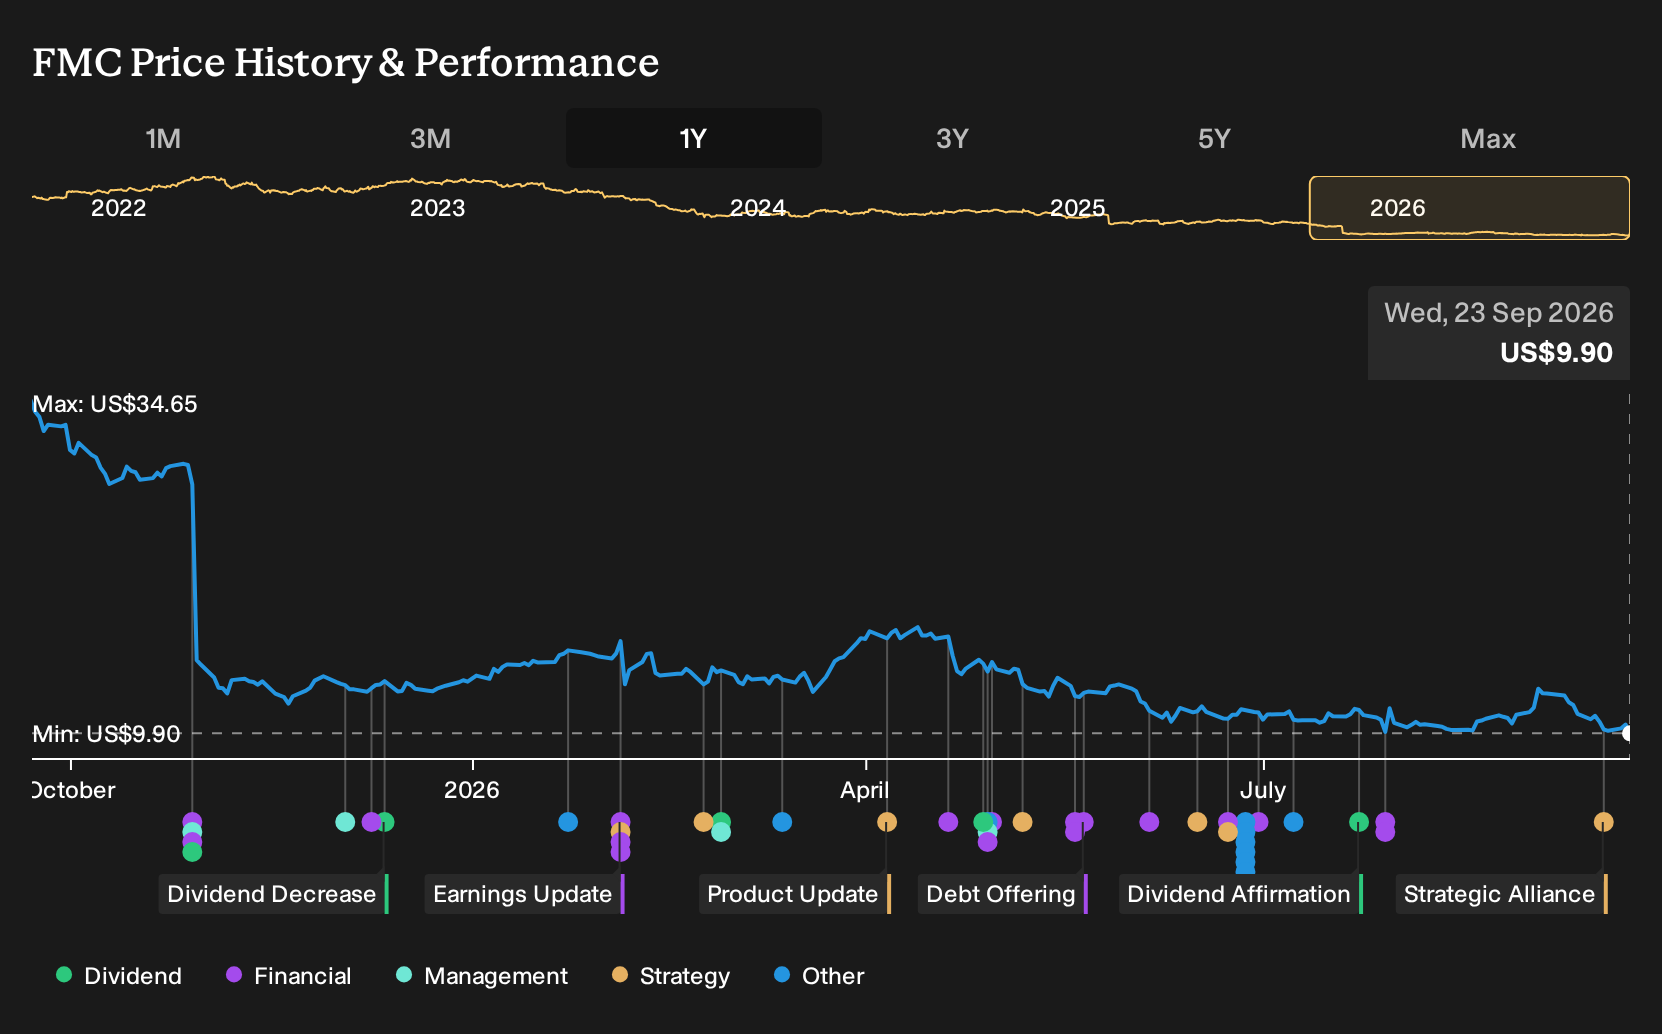
Exploring Other Perspectives
One alternate view focuses on FMC’s R&D commitment. The most pessimistic analysts worry that limited reinvestment could cap the payoff from RNA tools, even with this new AgroSpheres step. Before the news, they were only baking in about 5.1% annual revenue growth to roughly US$3.8b and US$317.0m of earnings by 2029. That gap in expectations shows how widely opinions can differ. It is therefore worth exploring several narratives before deciding how this development might reshape your own view.
Explore 4 other FMC fair value estimates, including one that suggests it could be worth just $11.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your FMC research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for FMC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate FMC's overall financial health at a glance.
Looking For More FMC Investment Ideas Beyond This Story?
If this FMC update has you rethinking where you want to put fresh capital to work, it can help to scan a wider field of companies that fit different risk and return profiles.
- For investors hunting resilient businesses with an emphasis on balance sheet strength, start with a list of solid balance sheet and fundamentals (23 results) that can handle tougher conditions without leaning heavily on new borrowing.
- If steady income is a priority, survey a range of higher yielding payers by reviewing a curated mix of 7 dividend fortresses that focus on cash returns to shareholders.
- Those looking for mispriced opportunities can cast a wider net across global markets and study a 16 high quality undiscovered gems that screens for quality fundamentals hiding behind quieter tickers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com