
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Qorvo (QRVO) Could Be 31% Above Fair Value On Index Exit
Index exit puts Qorvo back under the microscope
Qorvo (QRVO) has been removed from the PHLX Semiconductor Sector Index, an index adjustment that can alter how some funds and benchmarks gain exposure to the chipmaker.
The change comes at a time when Qorvo trades near US$119.59 and carries a market value around US$10.4b. This may encourage investors to reassess how the business fits into broader semiconductor portfolios.
Over the past year, Qorvo has delivered a 28.22% 1 year total shareholder return, while the 30 day share price return of 25.40% and year to date share price return of 38.62% suggest that momentum has been building ahead of this index removal.
Scan how Qorvo's index exit compares with other potential movers by checking the hand picked 85 AI infrastructure stocks in the semiconductor supply chain.
Qorvo now trades near the top of its recent range after a sharp run and a fresh index exit. Should investors consider putting money to work here, or wait for a calmer entry point and a lower valuation?
Most Popular Narrative: 31% Overvalued
Qorvo's most followed narrative points to a fair value of about $91.46, which sits well below the recent $119.59 share price. The gap puts the recent rally and the index exit in sharper focus for anyone weighing fresh exposure.
The analysts have a consensus price target of $91.46 for Qorvo based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $4.0 billion, earnings will come to $597.6 million, and it would be trading on a PE ratio of 16.2x, assuming you use a discount rate of 12.0%.
See why 18 investors see Qorvo as 31% overvalued.
Result: Fair Value of $91.46 (OVERVALUED)
Still, Qorvo’s heavy reliance on a single customer and the execution risk around its diversification plans could quickly challenge the current narrative of overvaluation.
Find out about the key risks to this Qorvo narrative.
Another View: What Qorvo’s P/E Is Really Saying
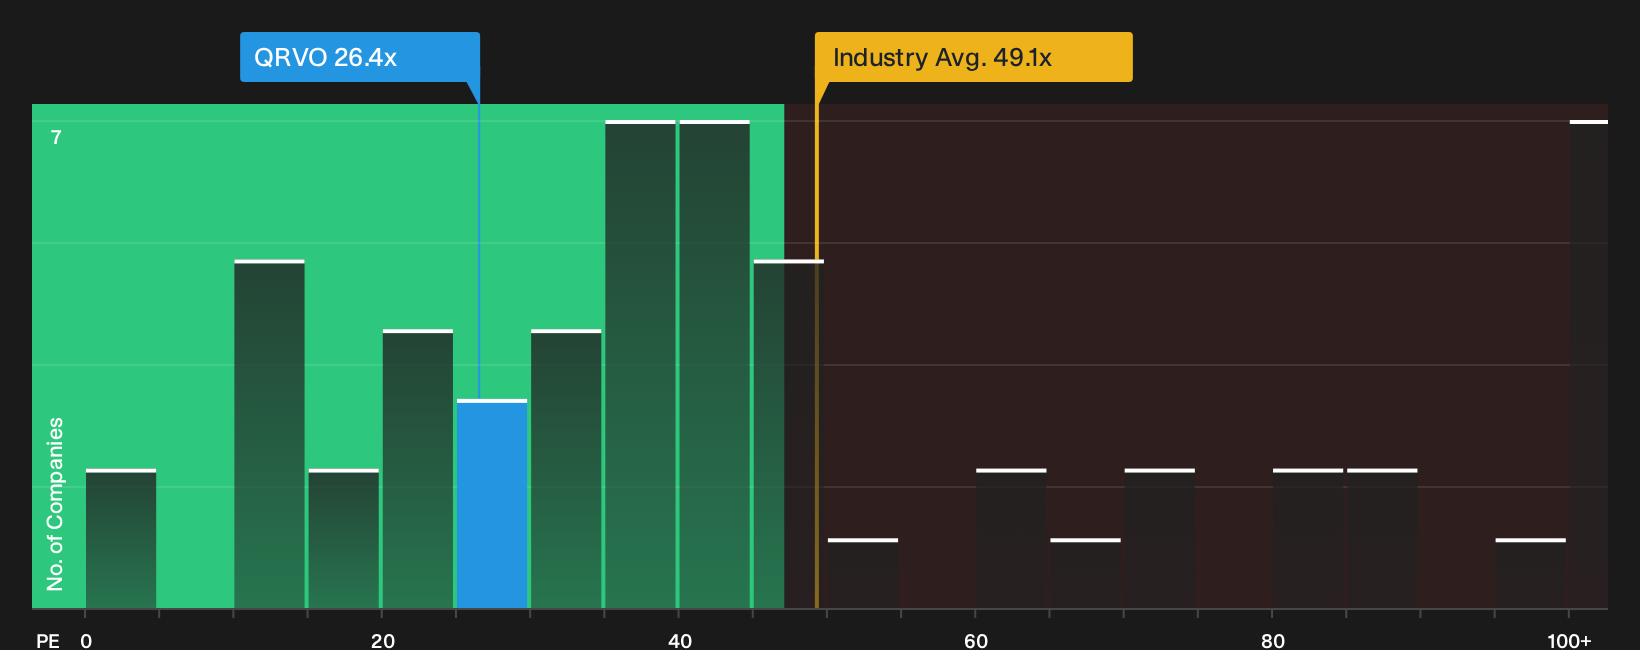
Qorvo may screen as overvalued against the $91.46 fair value from the analyst narrative, yet its current P/E of 26.4x tells a different story. That multiple sits well below both peers at 35.2x and the wider US Semiconductor group at 49.3x, while still above a fair ratio of 22.3x.
For you as an investor, that gap suggests the market already prices Qorvo at a premium to the fair ratio, but not at the richer levels seen across many rivals. The question is simple: does the risk of the P/E sliding toward 22.3x matter more to you than the chance it stays closer to peer levels?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Qorvo story points to mixed conviction, so move quickly, test the assumptions against the raw numbers, and weigh both the 3 key rewards and 1 important warning sign.
Looking for more Qorvo style investment ideas?
You now have a clearer view of Qorvo, so keep that momentum going and use the screener to uncover fresh, higher conviction ideas that match your risk level.
- Target reliable cash generators by scanning a list of solid balance sheet and fundamentals (23 results) that can better withstand shocks than more fragile peers.
- Hunt for pricing gaps with a 30 high quality undervalued stocks that couples stronger fundamentals with more modest expectations baked into the share price.
- Secure more predictable income streams by reviewing a 7 dividend fortresses that focuses on higher yields supported by underlying cash flow.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com