
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
A Nearly $20 Million Reason to Buy CoreWeave Stock
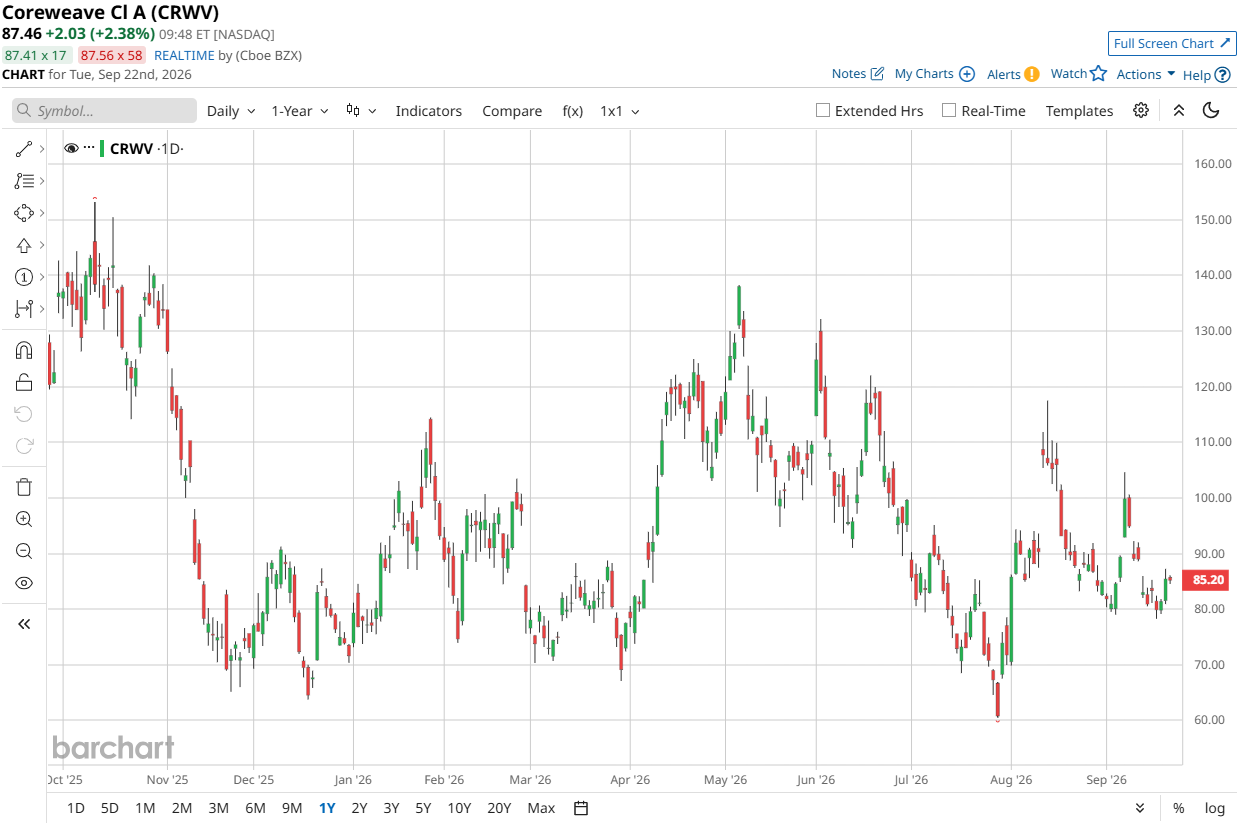
CoreWeave’s (CRWV) transformation from an Ethereum (ETHUSD) mining operation into a major player in artificial intelligence (AI) infrastructure ranks among Wall Street’s more surprising business pivots. Founded in 2017, the company took advantage of the 2018 to 2019 crypto winter by acquiring distressed GPU hardware and redirecting those resources toward compute-intensive workloads. Today, however, CRWV stock is under pressure as investors weigh CoreWeave’s aggressive capital spending against the promise of AI-driven growth.
The pressure intensified on Sept. 17, when shares fell 4% after the company announced a $3 billion convertible notes offering along with a program permitting the sale of up to 35 million Class A shares. The convertible offering was later upsized to $3.7 billion with a conversion price of approximately $97.85 per share.
That same-day decline caught the attention of Cathie Wood’s Ark Invest. On Sept. 17, the firm purchased 239,083 shares of CRWV stock worth $19.9 million through the Ark Innovation ETF (ARKK) and Ark Next Generation Internet ETF (ARKW).
Wood’s investment signals confidence in CoreWeave’s longer-term prospects. The more consequential issue, however, is whether the company can convert extraordinary AI demand into growth that is both profitable and efficiently financed.
About CoreWeave Stock
Headquartered in Livingston, New Jersey, CoreWeave is a cloud infrastructure provider focused on AI workloads. Its platform offers GPU and CPU computing, networking, storage, Kubernetes, lifecycle management, and AI development tools. With a market capitalization of $39.8 billion, CoreWeave provides businesses with the infrastructure needed to build, train, deploy, and scale AI models. Its services also support machine learning, rendering, pixel streaming, and batch processing.
Over the past 52 weeks, CRWV stock has declined 35%. The recent weakness has been equally notable, with the stock down 14% over the past three months. However, the stock is up by more than 8% in the past five trading sessions.
From a valuation perspective, CRWV stock currently trades at 7.7 times sales. That multiple is above the industry average, indicating that investors are assigning a premium valuation to the company.
A Closer Look at CoreWeave’s Q2 Earnings
On Aug. 11, CoreWeave reported a strong second quarter of fiscal 2026, sending shares more than 19% higher in the following trading session. Revenue jumped 112% year-over-year (YOY) to $2.6 billion, ahead of analysts’ estimate of $2.54 billion, while revenue backlog surged 246% YOY to $104 billion at quarter-end.
The backlog figure excludes more than $25 billion in additional commitments secured early in Q3. More than 50% of the existing backlog is already tied to contracts where customer delivery has begun, giving CoreWeave greater visibility into future revenue and providing a clearer line of sight as those commitments convert into sales.
Adjusted EBITDA grew 100% YOY to $1.5 billion in Q2, while the 59% adjusted EBITDA margin remained below the prior-year level as the company continued absorbing substantial infrastructure-ramp costs. Adjusted operating income reached $128 million, down 36% YOY. CoreWeave also posted an adjusted net loss of $567 million, compared with a net loss of $130 million in Q2 fiscal 2025.
Capital intensity was equally striking, with capital expenditures reaching $9.4 billion during the quarter, slightly above the high end of the company’s guided range. That elevated spending reflects faster customer deliveries and the need to bring additional infrastructure online.
Looking ahead, CoreWeave expects Q3 revenue between $3.45 billion and $3.6 billion. Capex for Q3 is projected at $11.5 billion to $13.5 billion as the company delivers significant new capacity to customers.
For full-year 2026, CoreWeave raised its revenue guidance to $12.4 billion to $13.2 billion and now expects full-year 2026 capex of $35 billion to $39 billion. The company also raised its year-end annualized run-rate revenue (ARR) forecast to $18.5 billion to $19.5 billion.
Wall Street expects CoreWeave to remain in investment mode over the coming quarters, with losses likely to widen before easing. For Q3 fiscal 2026, analysts project loss per share to widen 406% YOY to $1.57. For the full fiscal year, estimates call for a loss per share of $5.19, widening 93% from the previous year. The earnings outlook improves in fiscal 2027, however, with analysts forecasting a loss per share of $3.47, representing a 33% YOY improvement.
What Do Analysts Expect for CoreWeave Stock?
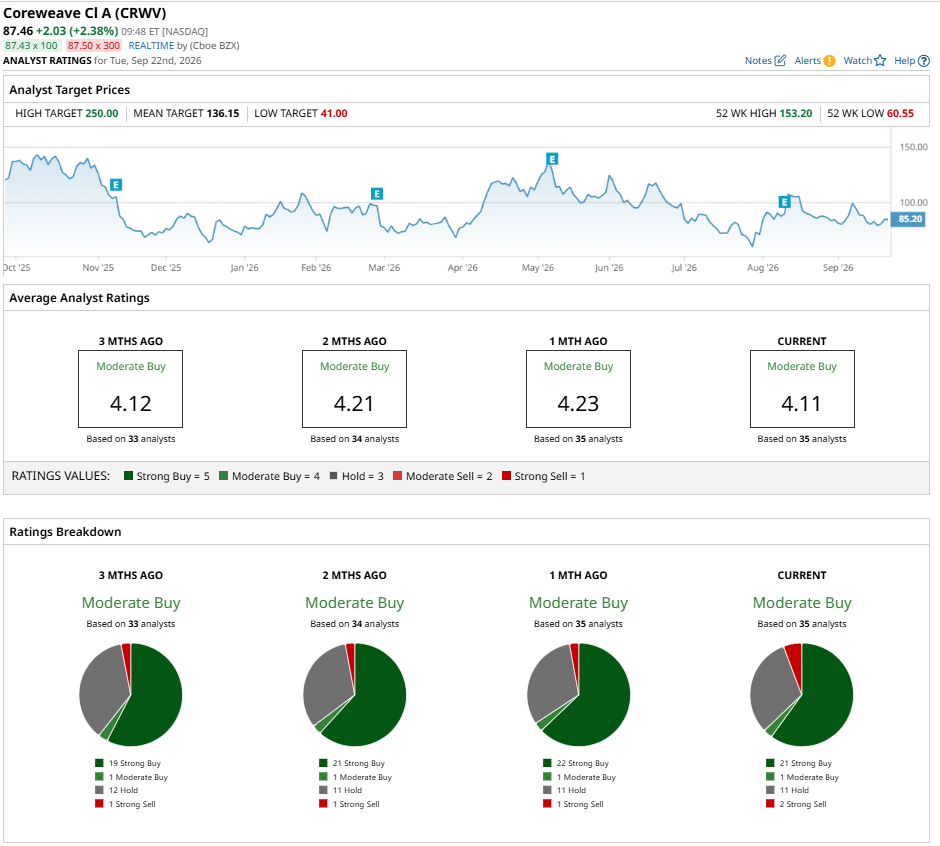
Wall Street’s overall assessment of CoreWeave remains favorable. CRWV stock currently carries a consensus “Moderate Buy” rating. Of the 36 analysts covering the stock, 22 recommend a “Strong Buy” rating, one analyst has a “Moderate Buy” rating, 11 recommend a “Hold,” and two have a “Strong Sell" rating.
The average price target of $135.69 represents potential upside of 58% from current levels. Meanwhile, the Street-high target of $250 from Rosenblatt analyst John McPeake implies the stock could climb as much as 191% from here. McPeake recently reiterated a “Buy” rating on CRWV stock, arguing that CoreWeave is “taking advantage of […] strength in fundamentals” to improve its balance sheet. In particular, he pointed to the company’s convertible notes offering and at-the-market (ATM) program as important steps toward improving its financial position.
On the date of publication, Aanchal Sugandh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.