
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 European Auto Service Stocks Riding Hybrid Growth
Europe’s car market is quietly rewiring itself as hybrids race ahead and Chinese brands push deeper into EU showrooms, while trade rules and new tariffs reshape the playing field in real time. That shift creates both potential upside and fresh risk for any stock tied to auto after-sales, servicing or parts. This article spotlights three European after-sales and service stocks linked to that story and explains how the same headlines could help or hurt each one.
The three stocks covered below are just a sample from this after-sales theme, and the full screen surfaced 22 more European operators with similarly interesting stories that are not mentioned in this article. To go straight to the full stock list and analyze, filter and identify your own highest conviction ideas, head into the European Auto After-Sales and Service Networks Leveraging Hybrid Growth screener.
Inter Cars (WSE:CAR)
Overview: Inter Cars is a leading European distributor of car and truck spare parts, supplying garages and fleets across multiple EU markets.
Operations: Inter Cars generates most of its revenue from PLN21.5b in spare parts sales, with an additional PLN0.7b from its Ukraine operations.
Market Cap: PLN12.9b
Inter Cars sits right in the sweet spot of this screener, supplying the growing pool of hybrids, EVs and combustion vehicles. All of these vehicles need increasingly complex replacement parts and service support as the car park evolves across Europe.
"Inter Cars is investing heavily in warehouse robotization and digital transformation, with new facilities planned in Poland and Romania. These efforts in automation are expected to optimize processes and reduce costs, potentially improving net margins and overall earnings."
How much of that margin story ultimately sticks will depend on one unseen pressure that could quietly reshape pricing power across its network.
That pressure point is the starting line for the full narrative for Inter Cars, which maps where pricing power could crack and where Inter Cars might quietly accelerate instead.

Nokian Renkaat Oyj (HLSE:TYRES)
Overview: Nokian Renkaat Oyj designs and manufactures passenger and heavy vehicle tires and runs the Vianor service network across key global markets.
Operations: The business generates most of its €1.4b revenue from Passenger Car Tyres at €899 million, with Heavy Tyres and Vianor contributing the rest.
Market Cap: €2.2b
Nokian Renkaat fits within this after-sales theme because every additional hybrid or EV kilometre on European roads eventually runs through its replacement tire and service channels.
"The push toward higher value winter, all season and 18 inch plus tires raises the bar for continued product launches and marketing. If consumer willingness to pay for premium features weakens, mix and pricing power could soften, which would pressure revenue growth and segment EBITDA margins."
A key factor for the investment case is how the unresolved balance between costs and pricing develops across its premium tyre portfolio.
That pricing tug of war is where the story gets interesting, and the full narrative for Nokian Renkaat Oyj shows how Nokian Renkaat could still turn premium pressure into accelerating opportunity.

Bilia (OM:BILI A)
Overview: Bilia runs a Nordic full-service car retail and after-sales network, tying new and used vehicle sales directly into workshops, servicing and parts.
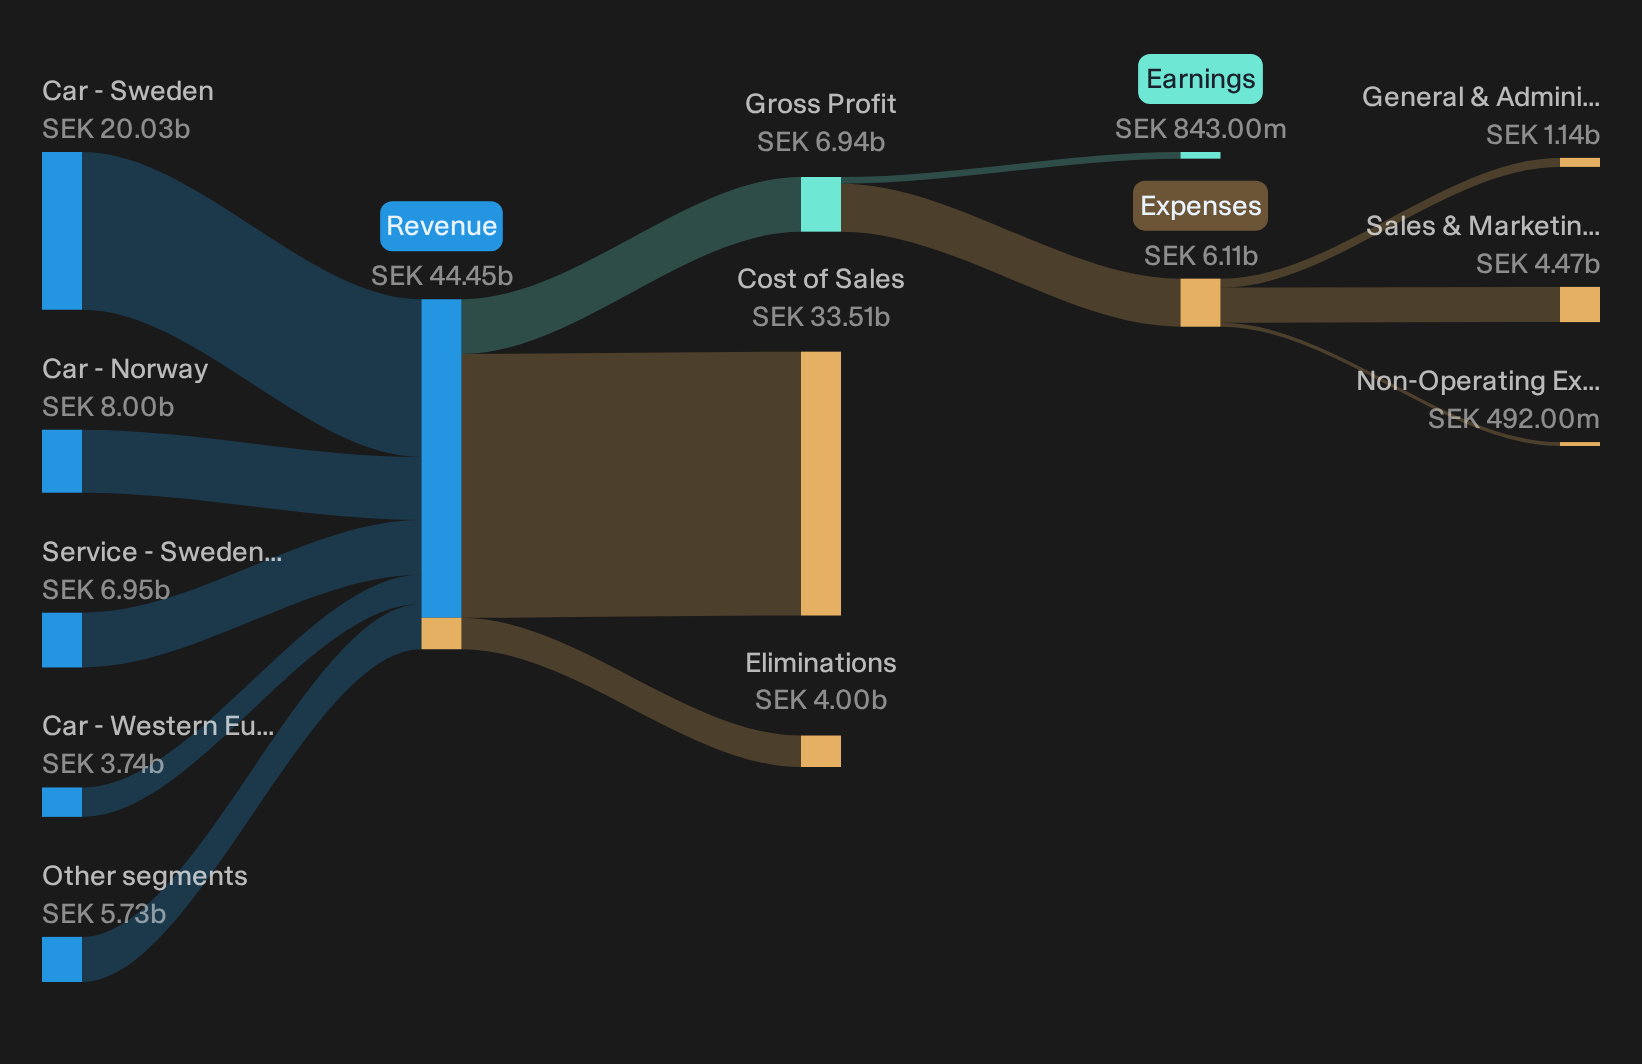
Operations: Bilia generates most of its revenue from Swedish car operations at SEK20.0b and Swedish service operations at SEK7.0b, with Norway and Western Europe contributing smaller car and service revenue streams.
Market Cap: SEK13.5b
Bilia matters for this hybrid focused screener because its workshops, service bays and fuel sites are tightly linked to how drivers actually use and maintain an increasingly electrified car fleet across its Nordic footprint.
"Bilia is accelerating its targeting of the older car segment and integrating new EV brands such as Polestar, XPENG, and Lynk & Co into its workshops, positioning the company to capture incremental aftersales and service revenue as the car population ages and EV adoption rises. This may support high-margin, recurring earnings growth."
What happens when one quiet shift in how those hybrid and EV customers service their cars tips the balance for Bilia’s margins?
If that margin tipping point matters to you, the full narrative for Bilia describes how Bilia’s service mix, EV partnerships and capital allocation could be quietly accelerating.
Seeking Fresh Alternatives Before They Fly?
Some of the most interesting ideas break out quietly, then move fast once the crowd catches on. Scan these fresh lists while it matters and get an early look.
- Spot strong balance sheets before momentum traders arrive by running through the list of solid balance sheet and fundamentals (199 results) and pick out businesses with financial room to move.
- Explore potential momentum in high-yield payers by scanning the 158 dividend fortresses and focus on companies where cash returns remain front and center.
- Find under the radar operators before attention spikes by working through the 618 high quality undiscovered gems and isolate stories the broader market has not fully priced.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com