
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Sumitomo Rubber Industries (TSE:5110) A Bargain As Its Share Price Sits At ¥2,037?
Sumitomo Rubber Industries (TSE:5110) drew renewed attention after its recent share move, with the price closing at ¥2,037. Investors are now weighing this level against the group’s tyre-focused, globally diversified operations.
That latest move sits against a tougher backdrop, with the share price return down 11.1% over the past month and 16.2% lower year to date. Even so, total shareholder return over the past year is 17.4%, which hints that momentum has recently cooled after a stronger run.
Scan how Sumitomo Rubber Industries stacks up against other potential opportunities by comparing it with a hand picked 18 high quality undervalued stocks that share solid fundamentals and attractive pricing signals.
Bulls point to Sumitomo Rubber Industries’ global tyre footprint and recent earnings growth, while bears focus on the sharp pullback. The valuation numbers now need to show which side currently has the stronger case.
Price-to-Earnings of 8.7x: Is it justified?
On the latest data, Sumitomo Rubber Industries trades on a P/E of 8.7x, which screens as good value against both its peers and the wider JP Auto Components industry. That multiple sits on a last close of ¥2,037 and reflects how the market is pricing each unit of current earnings.
The P/E ratio compares the share price to earnings per share and is often used for established manufacturers where profit is a key focus. For a mature tyre and rubber products group with a long operating history, it helps investors judge how much they are paying today for the profit stream the business is already generating.
Analyst and model-based checks point in the same direction. The stock is flagged as trading at good value relative to its peer group average P/E of 10.6x and the JP Auto Components industry average of 9.8x. The SWS fair P/E estimate sits higher again at 14.7x, which indicates that the current 8.7x level is materially lower than the ratio the market could potentially move towards if expectations and pricing were to converge.
Explore the SWS fair ratio for Sumitomo Rubber Industries.
Result: Price-to-Earnings of 8.7x (UNDERVALUED)
Still, any renewed weakness in global tyre demand, or pressure on margins from higher input costs, could quickly challenge the current Sumitomo Rubber Industries valuation story.
Find out about the key risks to this Sumitomo Rubber Industries narrative.
Another view using the SWS DCF model
The P/E points to value, but the SWS DCF model also suggests Sumitomo Rubber Industries trades below an estimated future cash flow value of ¥3,698.1 per share versus the current ¥2,037. That gap looks meaningful. However, it raises a simple question for investors: Which signal do you trust more right now?
Look into how the SWS DCF model arrives at its fair value.
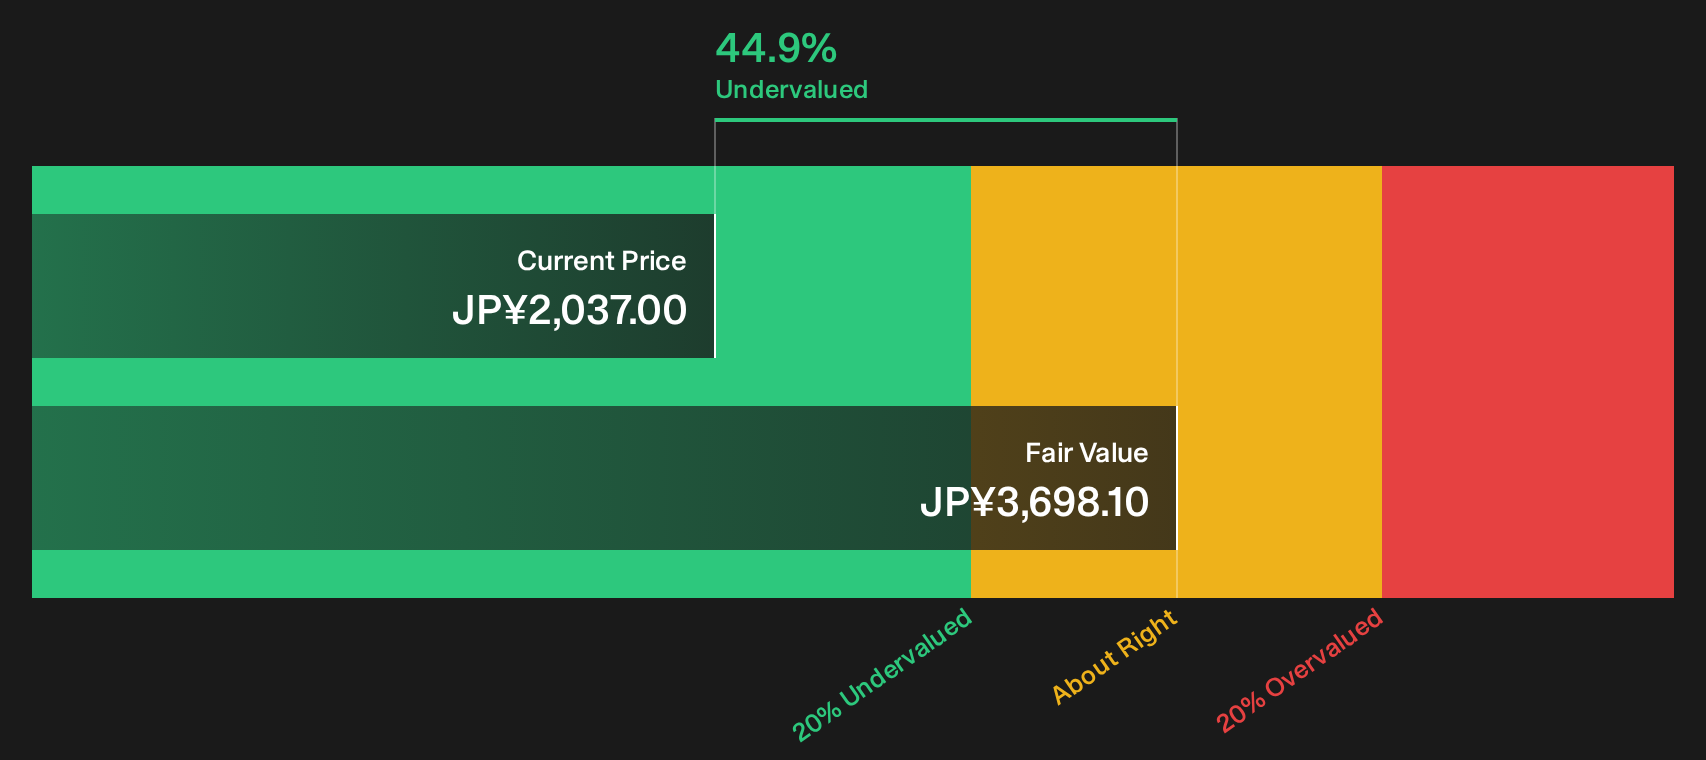
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sumitomo Rubber Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Sumitomo Rubber Industries can make the picture feel blurred, so consider moving quickly, pulling up the full data set, and weighing both the risks and the upside for yourself using the 5 key rewards and 1 important warning sign
Looking for more ideas beyond Sumitomo Rubber Industries?
If Sumitomo Rubber Industries has caught your eye, do not stop there. Broaden your watchlist with a few focused screens that highlight different strengths.
- Target potential mispricing by scanning a curated 18 high quality undervalued stocks that already combine solid fundamentals with appealing valuation signals.
- Prioritise resilience by reviewing a 21 resilient stocks with low risk scores that may help anchor your portfolio when conditions turn choppy.
- Spot future contenders early by checking a 75 high quality undiscovered gems that pair quality metrics with limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com