
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Our Pick Of The Best Canadian Penny Stocks In September 2026
Global government bond yields are nearing 4%, a level not seen since 2007, and that shift in borrowing costs keeps rewarding investors who can find smaller Canadian companies with strong finances already proving themselves in the past year. This corner of the market offers potential mispricing where the balance sheet does more talking than hype. This article breaks down three higher quality penny stocks that fit that profile.
The three elite penny stocks covered below are a starting sample. The full screen surfaced 15 more Canadian companies with equally compelling balance sheets, insider alignment, and recent share price strength that do not fit into one article.
To go deeper into this idea, head straight into the Elite Penny Stocks screener to identify, filter, and analyze the highest conviction setups that match your own risk and return preferences.
ACT Energy Technologies (TSX:ACX)
Overview: ACT Energy Technologies provides measurement while drilling, rotary steerable systems, and related directional drilling services that help oil and gas producers optimize wells.
Operations: ACT Energy Technologies generates about $550 million from directional drilling services, with around $220 million from Canada and $331 million from the United States.
Market Cap: $293 million
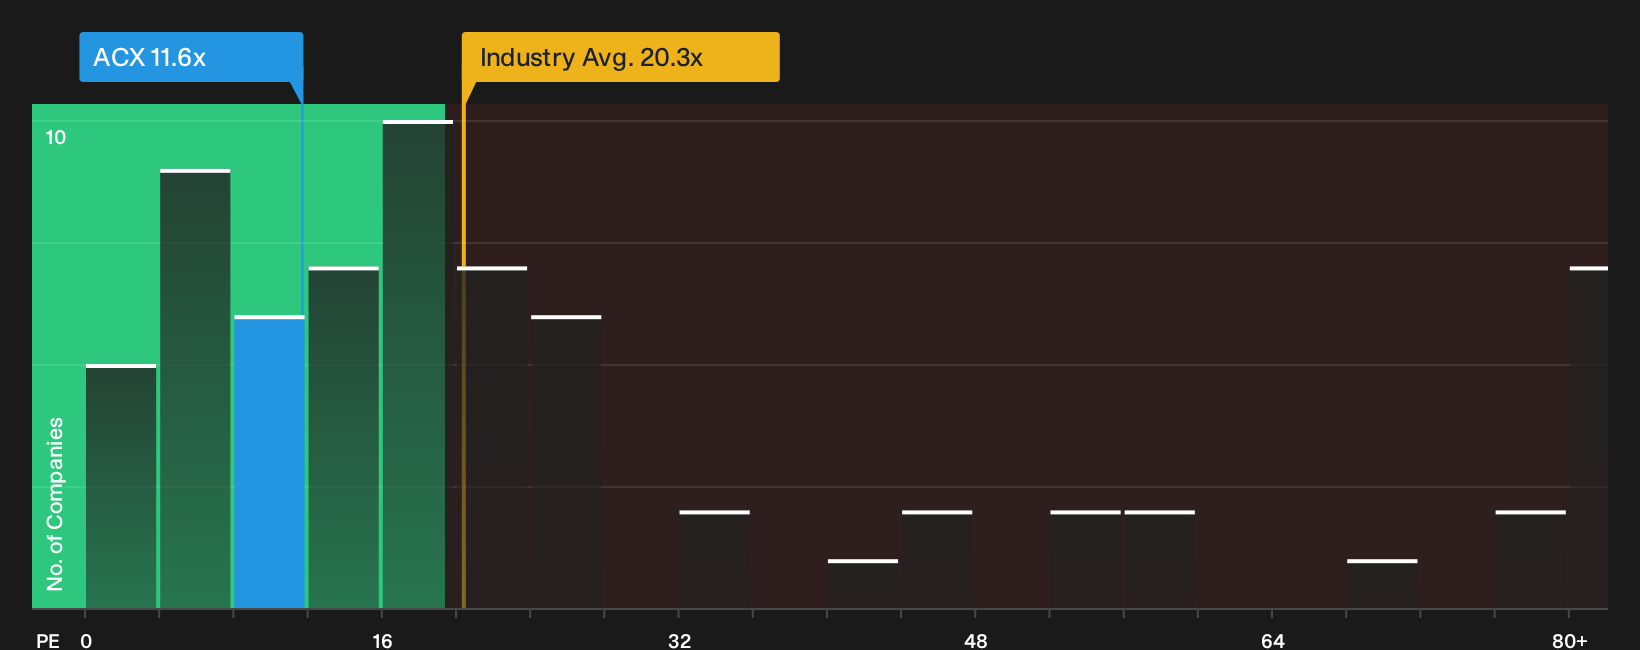
ACT Energy Technologies plugs directly into the Elite Penny Stocks theme through its MWD and rotary steerable services, supported by analyst forecasts of 9.4% annual earnings growth and a P/E of 11.6x versus a 20.6x industry average. The stock also screens as deeply undervalued, yet the high debt load means future returns could depend on how pressure on cash flow evolves.
If that debt and cash flow tension has your attention, go straight to the 3 key rewards and 2 important warning signs to see what might be masking or amplifying the opportunity.
Alvopetro Energy (TSXV:ALV)
Overview: Alvopetro Energy focuses on onshore oil and natural gas production in Brazil, developing the Caburé, Murucututu, Bom Lugar and Mãe-da-lua fields.
Operations: The business generates about $62 million from oil and gas exploration and production, with roughly $59 million sourced from Brazil and $3 million from Canada.
Market Cap: $373 million
Alvopetro Energy fits the Elite Penny Stocks theme through its producing Brazilian gas fields, where onshore wells, infrastructure and cash returns all point to a business already executing rather than just promising growth.
"Field diversification: successful step-out/multi-zone wells proving reserves are NOT concentrated in a single Murucututu structure (the single biggest re-rating driver)."
What happens to Alvopetro Energy’s upside if one quiet shift in future cash generation changes how sustainable those rich margins look?
If that cash profile is what you care about next, go straight to the full narrative for Alvopetro Energy to see how Alvopetro Energy’s risk and reward are really decoupling.

Athabasca Oil (TSX:ATH)
Overview: Athabasca Oil develops long life thermal oil sands and Duvernay light oil and gas assets in Alberta for energy buyers.
Operations: Athabasca Oil generates about CA$1.28 billion from Athabasca thermal oil and CA$103 million from Duvernay Energy, entirely in Canada.
Market Cap: CA$4.9 billion
Athabasca Oil fits within this Elite Penny Stocks theme because its thermal oil sands business is supported by a balance sheet that management indicates can fund growth from internal cash generation.
"Expansion of Athabasca Oil’s long life Leismer thermal project toward 40,000 bbl/d by the end of 2027 at an estimated capital efficiency of about $25,000 per flowing barrel and an expected sustaining breakeven of roughly US$45 WTI. This strategy is intended to pursue higher future revenue and operating margins from a larger, lower cost production base."
The key variable is how changes in future cash returns might influence the balance between growth initiatives and efforts to maintain margins.
That trade off between funding growth and protecting returns is exactly what the full narrative for Athabasca Oil unpacks, showing where Athabasca Oil could be accelerating or stalling next.

Seeking Alternatives Before The Crowd
Fresh breakouts and quiet momentum shifts do not stay under the radar for long. Scan these curated ideas while it matters and get in early.
- Spot cash rich operators with staying power. Then zero in on resilient balance sheets using the list of solid balance sheet and fundamentals (7 results).
- Ride potential income momentum from reliable cash distributions by checking out the curated pipeline of high yield opportunities in the 1 dividend fortresses.
- Track capital flowing into next wave infrastructure and position ahead of grid upgrades through the targeted list in the 39 power grid technology and infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com