
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Boot Barn Holdings (BOOT) Could Be 45% Undervalued As Holiday Demand Lifts Attention
Boot Barn Holdings (BOOT) drew fresh attention after the footwear retailer climbed 3.8% on seasonal shopping data that pointed to firm Halloween demand and a potentially solid holiday spending backdrop for apparel and footwear.
For context, Boot Barn Holdings is trading at US$124.49, with the share price declining about 23% over the past month and roughly 33% year to date, even though the 3-year total shareholder return is up about 57% and the 5-year total shareholder return is about 29%. This suggests the latest Halloween and holiday demand data is being weighed against a cooler near term outlook and shifting risk perceptions after a strong multi year run.
Scan beyond Boot Barn Holdings and compare this holiday spending story with other retailers on the 16 high quality undiscovered gems that pair solid fundamentals with quieter share price attention.
After a 3.8% jump on holiday buzz but a year to date decline of about 33%, the real tension around Boot Barn Holdings now sits in the gap between the US$124.49 share price and valuation estimates. Where does fair value actually land?
Most Popular Narrative: 45% Undervalued
On the widely followed view, Boot Barn Holdings screens as materially cheaper than an estimated fair value of about $225 per share compared with the current $124.49 price. This perspective puts a lot of weight on how durable its store rollout and brand mix really are.
Robust store expansion into underpenetrated markets, particularly in population-growing regions, is driving higher-than-expected new store performance, strong customer acquisition, and increased sales productivity. This expansion provides an ongoing tailwind for revenue and positions Boot Barn to benefit from broader demographic shifts, supporting long-term top-line growth.
See why 11 investors see Boot Barn Holdings as 45% undervalued.
Result: Fair Value of $225 (UNDERVALUED)
Still, Boot Barn Holdings leans heavily on rapid store openings and on Western and workwear categories, so weaker new store returns or fashion shifts could quickly challenge that undervalued story.
Find out about the key risks to this Boot Barn Holdings narrative.
Another View: Boot Barn Holdings Through The Cash Flow Lens
That 45% undervalued story runs into resistance once the SWS DCF model is brought into the picture. On this framework, Boot Barn Holdings at $124.49 trades well above an estimated future cash flow value of about $51.98 per share, which implies overvaluation and a very different risk reward profile.
For readers who lean on discounted cash flows rather than price targets, Look into how the SWS DCF model arrives at its fair value.
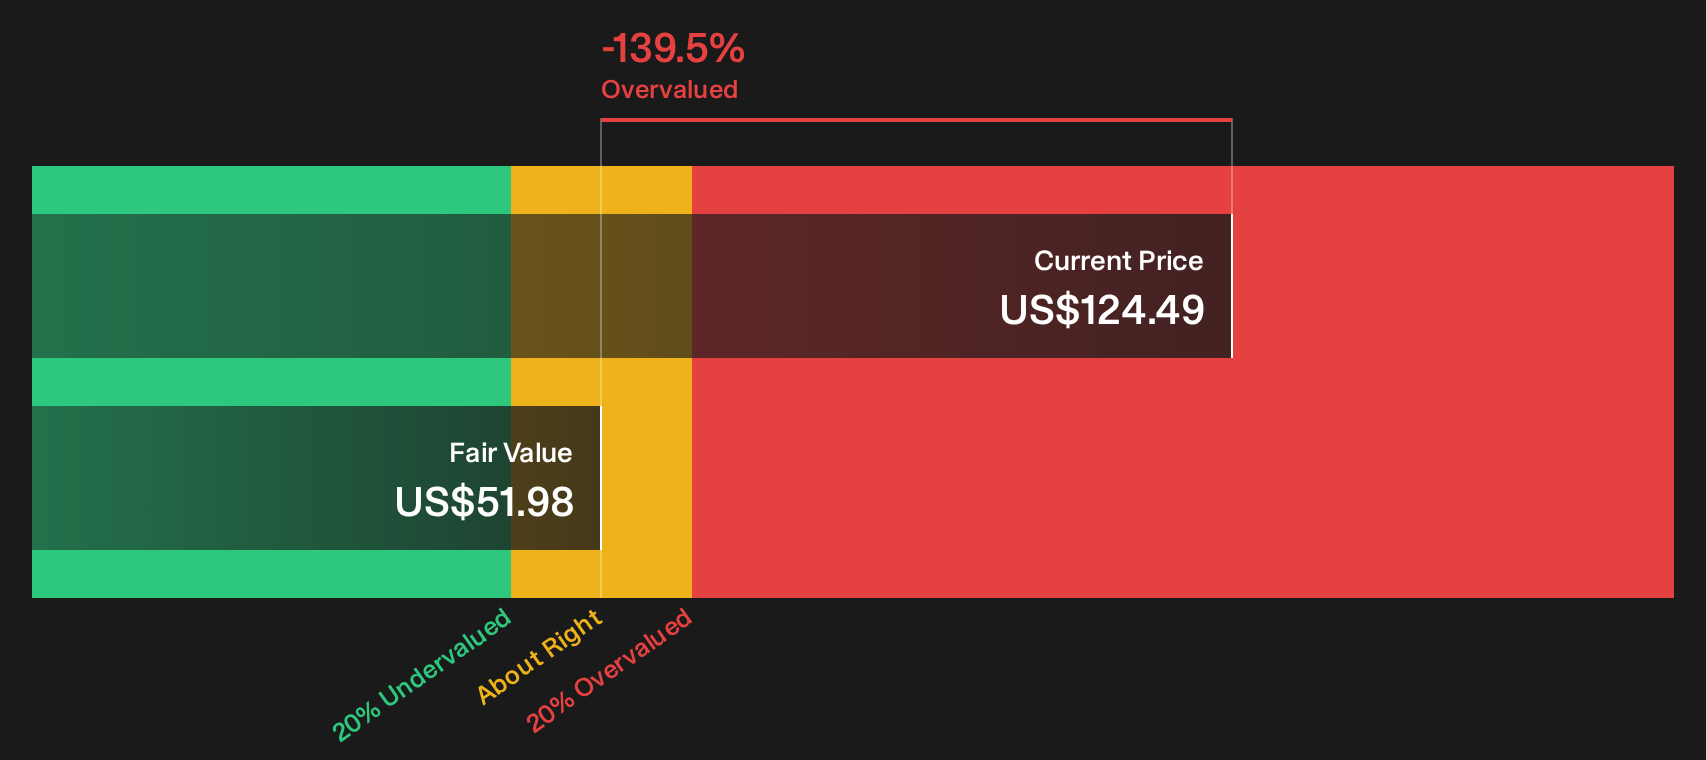
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Boot Barn Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Boot Barn Holdings can be confusing, so move quickly to review the full picture yourself, including the 4 key rewards.
Looking for more ideas beyond Boot Barn Holdings?
If Boot Barn Holdings sharpened your focus on valuation gaps and risk trade offs, do not stop here. Cast the net wider and pressure test your next move.
- Zero in on quality at a discount by scanning companies that appear mispriced on fundamentals through the 30 high quality undervalued stocks.
- Prioritise resilience and sleep better at night by filtering for companies with stronger finances using the list of solid balance sheet and fundamentals (23 results).
- Balance potential upside with a measure of stability by searching through the 31 resilient stocks with low risk scores before committing fresh capital.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com