
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Brookfield Asset Management Ulc (TSX:BAM) Could Be 18% Undervalued After Oakbrook Center Refinancing
Brookfield Asset Management Ulc (TSX:BAM) has been in focus after affiliates of its GGP unit arranged an $800 million refinancing for Illinois mall Oakbrook Center, returning about $65 million of equity to sponsors.
For context, Brookfield Asset Management Ulc’s refinancing move arrives after a mixed stretch for the stock. The share price is down about 11.8% over the past month and roughly 13.0% year to date, yet still reflects a 56.9% three year total shareholder return. This points to stronger longer run compounding than the recent 19.2% one year total shareholder loss might suggest.
Pressure test Brookfield Asset Management Ulc against a curated 8 resilient stocks with low risk scores that focuses on resilient balance sheets and steadier business models when refinancing moves hit the headlines.
Brookfield Asset Management Ulc just pulled fresh cash out of a flagship mall while the share price has slipped. Is most of the easy upside already in the rear view mirror, or does the valuation still leave meaningful room ahead?
Most Popular Narrative: 18% Undervalued
Brookfield Asset Management Ulc last closed at CA$63.85, which sits below the most widely followed narrative fair value of CA$77.35. This frames the refinancing news within a wider thesis built around private markets and AI infrastructure exposure.
Rising demand for AI related infrastructure and power supply, including the US$100b global AI infrastructure program and the AI fund targeting US$10b, is supporting higher deployment into long-term contracted assets with potential to lift both fee-related earnings and margin efficiency.
See why 21 investors see Brookfield Asset Management Ulc as 17% undervalued.
Result: Fair Value of CA$77.35 (UNDERVALUED)
Still, the Brookfield Asset Management Ulc story leans on continued appetite for private markets and large AI infrastructure projects. Any slowdown or project delays could quickly challenge that under-valuation narrative.
Find out about the key risks to this Brookfield Asset Management Ulc narrative.
Another View On Brookfield Asset Management Ulc's Valuation
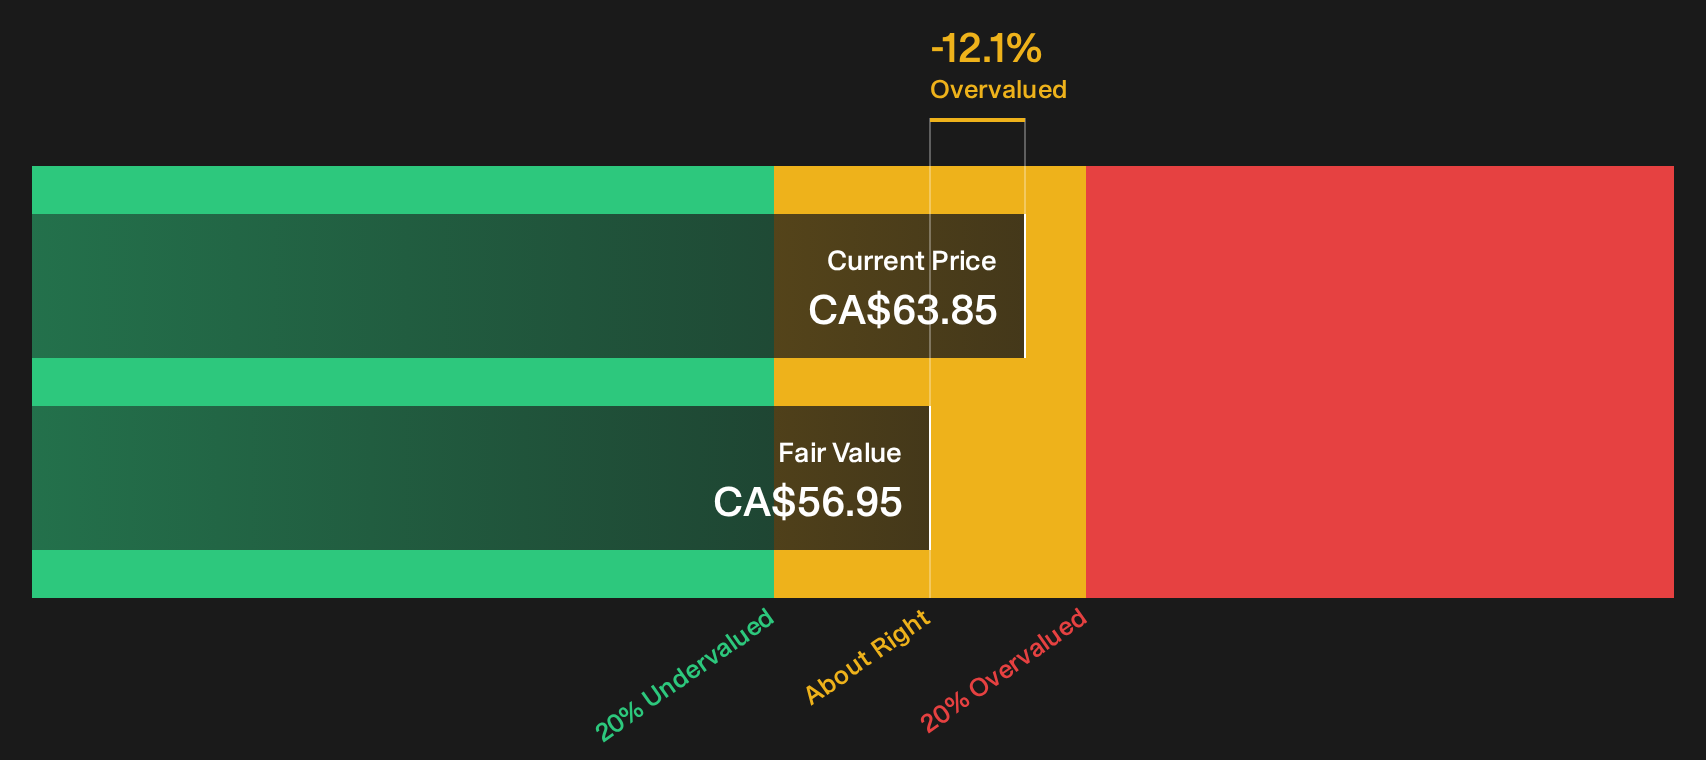
The first story presents Brookfield Asset Management Ulc as about 18% undervalued at CA$63.85 compared with a CA$77.35 fair value. A different perspective suggests something less comfortable. Our DCF model points to a future cash flow value of CA$56.95, which would make the current quote look expensive instead.
If the same cash flows can support both an undervalued narrative and an overvalued DCF outcome, the key question is which set of assumptions you consider most reliable for Brookfield Asset Management Ulc over the long term.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Brookfield Asset Management Ulc can feel confusing, so move quickly, review the full data set yourself, and then weigh the 3 key rewards and 1 important warning sign.
Looking for more Brookfield Asset Management Ulc sized ideas?
Brookfield Asset Management Ulc highlights how quickly narratives can shift, so broaden your watchlist now with fresh, data driven opportunities before the next move leaves you reacting late.
- Target potential mispricing by scanning a curated set of high quality prospects using the 5 high quality undervalued stocks that filters for strong fundamentals and appealing valuations.
- Prioritize resilience by focusing on companies with healthier finances through the list of solid balance sheet and fundamentals (7 results) that surfaces sturdier balance sheets and cleaner leverage profiles.
- Hunt for under-the-radar opportunities by checking the 9 high quality undiscovered gems that spotlights smaller businesses with solid metrics before they attract broader attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com