
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Jack Henry & Associates Stock Underperforming the Dow?
With a market cap of $10.4 billion, Jack Henry & Associates, Inc. (JKHY) is a financial technology company that connects people and financial institutions through technology solutions and payment processing services. It operates through four segments: Core, Payments, Complementary, and Corporate and Other, offering platforms and services ranging from core banking systems and digital/mobile banking to payment processing, risk management, and hardware solutions.
Companies valued at $10 billion or more are generally classified as “large-cap” stocks, and Jack Henry & Associates fits this criterion perfectly. The company provides a range of products including SilverLake, Symitar, CIF 20/20, Core Director, and the Banno Digital Platform.
Shares of the Monett, Missouri-based company have dipped 23.3% from its 52-week high of $193.39. Over the past three months, the stock has increased 18.4%, outpacing the Dow Jones Industrial Average's ($DOWI) marginal decline during the same period.
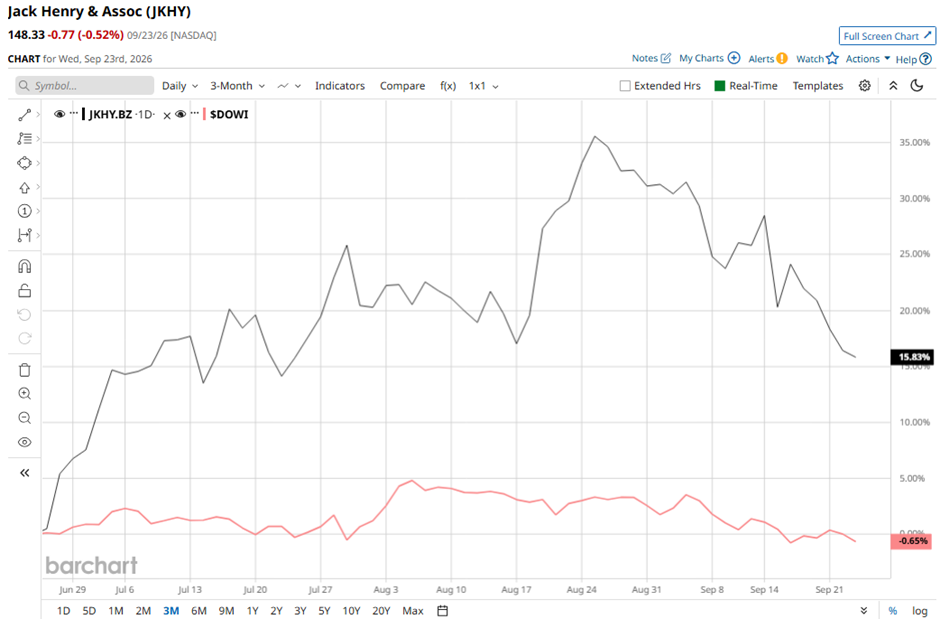
Shares of the financial technology firm have fallen 18.7% on a YTD basis, underperforming DOWI’s 7.2% return. Moreover, the stock has declined 1.1% over the past 52 weeks, compared to DOWI's 11.3% gain over the same time frame.
Yet, JKHY stock has been trading above its 50-day and 200-day moving averages since late June.
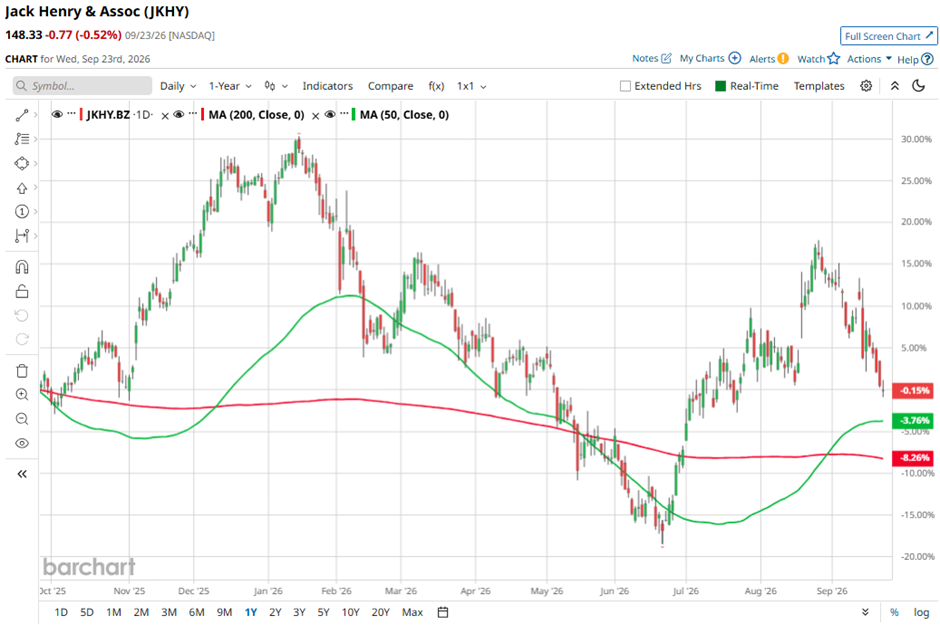
Jack Henry & Associates shares climbed 6.5% following its Q4 2026 results on Aug. 18, with better-than-expected EPS of $1.57 and revenue of approximately $644 million. Growth was supported by strong demand for its banking and payments technology, with services and support revenue up 2.5% and processing revenue up 7.5%, while management highlighted a robust sales pipeline and continued adoption of AI-driven solutions.
In comparison, rival Accenture plc (ACN) has lagged behind JKHY stock. ACN stock has decreased 31.6% on a YTD basis and 22.1% over the past 52 weeks.
Despite the stock’s underperformance relative to the Dow over the past year, analysts are cautiously optimistic about its prospects. JKHY stock has a consensus rating of “Moderate Buy” from the 20 analysts covering it, and the mean price target of $188 is a premium of 26.7% to current levels.
On the date of publication, Sohini Mondal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.