
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Taiwan Semiconductor Manufacturing (NYSE:TSM) Sees Early A14 Interest, Is It 18% Above Fair Value?
Taiwan Semiconductor Manufacturing (TSM) has drawn fresh attention after reporting strong customer interest in its upcoming A14 process technology, with initial tape outs ahead of schedule and volume production targeted for 2028.
The recent A14 update comes after a strong run in Taiwan Semiconductor Manufacturing’s share price, with a 39.72% year to date share price return and a 60.39% total shareholder return over the past year. This signals momentum that investors are watching closely.
Scan beyond Taiwan Semiconductor Manufacturing and see which other chipmakers are catching strong AI demand with our curated list of 85 AI infrastructure stocks.
The surge in Taiwan Semiconductor Manufacturing now forces a simple fork in the road. Are you paying up for a stronger business, or for sentiment that has raced ahead of the fundamentals as they stand today?
Most Popular Narrative: 18% Overvalued
Taiwan Semiconductor Manufacturing closed at $446.57, while the most followed narrative pegs fair value at $378.29. The story centers on whether investors are stretching too far for quality.
TSMC is a wonderful business. $417.52 is not a wonderful price. A wonderful business at a foolish price makes a foolish arithmetic, and no amount of margin brilliance in Hsinchu changes what the numbers say in New York.
See why 108 investors see Taiwan Semiconductor Manufacturing as 18% overvalued.
Result: Fair Value of $378.29 (OVERVALUED)
Still, this Taiwan Semiconductor Manufacturing story could flip quickly if hyperscaler AI capex cools or credible 2 nm competition from Intel and Samsung begins to have an impact.
Find out about the key risks to this Taiwan Semiconductor Manufacturing narrative.
Another Angle On Taiwan Semiconductor Manufacturing’s Valuation
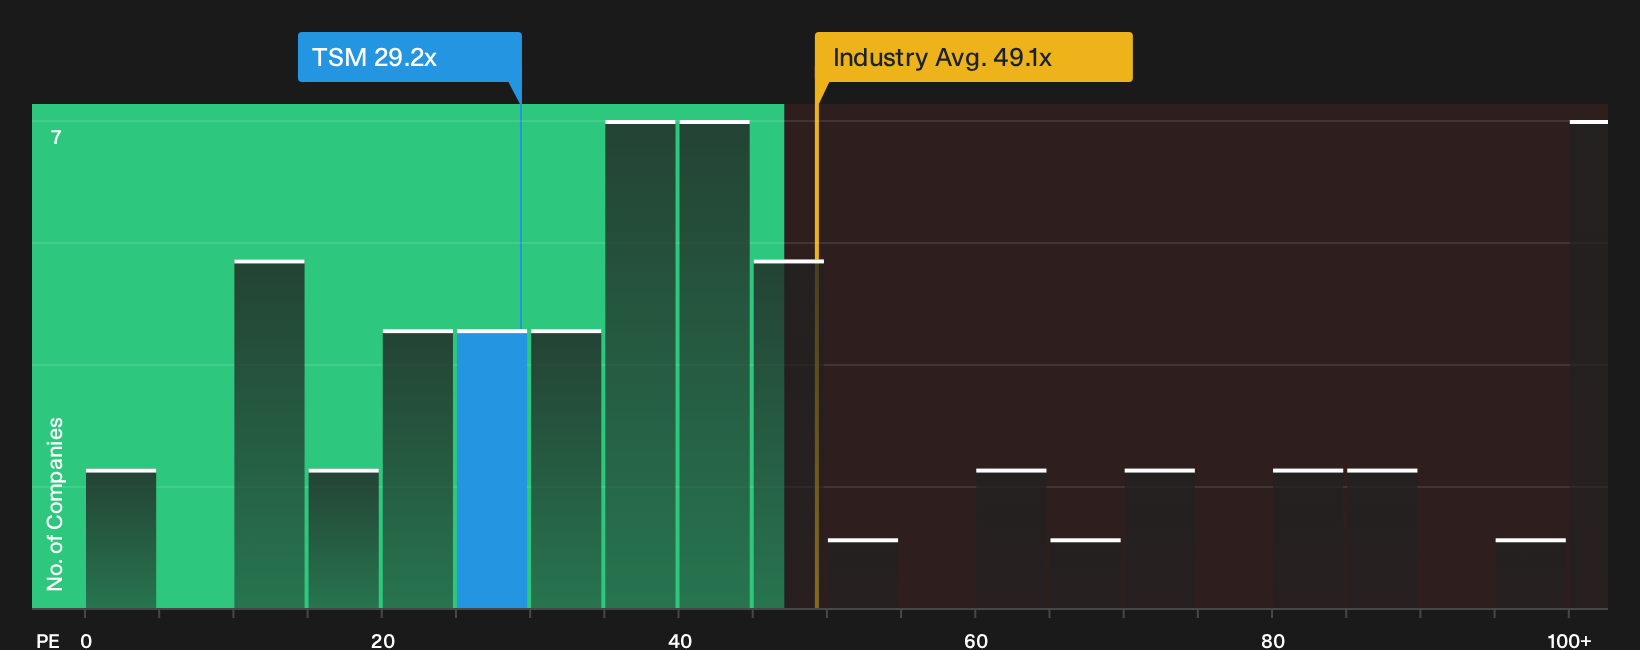
The earlier narrative leans on detailed scenario work and a fair value of $378.29 that frames Taiwan Semiconductor Manufacturing as 18% overvalued at $446.57. The market is telling a different story. On a simple P/E basis of 29.2x, TSM trades well below both peers at 62.9x and the Semiconductor industry at 49.1x, and even below a fair ratio of 43.4x that our regression work suggests the multiple could move toward over time. This raises the question of whether that gap reflects investors appropriately pricing in risk, or whether it could be an opportunity that future earnings might eventually close.
For a closer look at how the numbers line up against earnings power and peer comparisons, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this Taiwan Semiconductor Manufacturing debate feels finely balanced, treat it as your prompt to move quickly and test the numbers yourself. To see both sides of the story in one place, review the 4 key rewards and 1 important warning sign.
Looking for more ideas beyond Taiwan Semiconductor Manufacturing?
If the Taiwan Semiconductor Manufacturing debate has sharpened your thinking, do not stop there. Use this momentum to widen your opportunity set before the market moves on.
- Zero in on quality at a discount and scan our 30 high quality undervalued stocks that combine fundamentals with attractive pricing.
- Prioritise resilience and protect your downside by focusing on 31 resilient stocks with low risk scores with steadier profiles.
- Hunt for tomorrow’s potential leaders early and review the 16 high quality undiscovered gems before others start paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com