
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why SoFi Stock Is a Good Buy Now
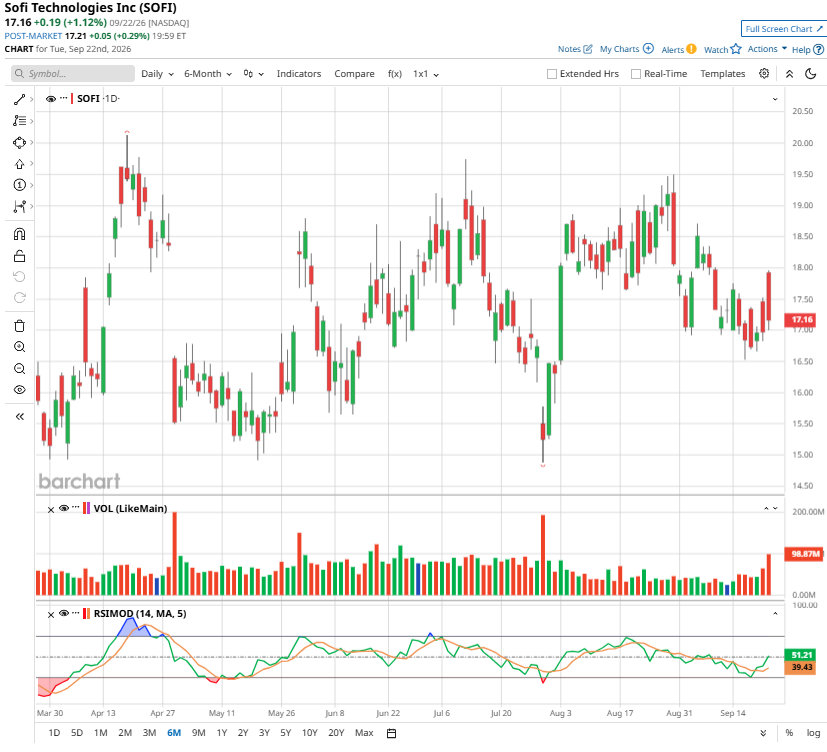
SoFi Technologies (SOFI) stock has underperformed so far this year, with shares down approximately 34.5% year to date. The stock has also traded within a relatively narrow range for several months.
One of the biggest factors behind SoFi’s underperformance is the increasing contribution of its lending business to overall revenue. In the second quarter, SoFi reported record adjusted net revenue of $1.2 billion, up 40% year over year. However, much of that growth came from lending. The lending segment generated $712 million in revenue, compared with $551 million from the combined Financial Services and Technology Platform businesses.
As a result, revenue from SoFi’s non-lending operations represented about 46% of total adjusted net revenue. This reflects a continued decline in its share price over the past two consecutive quarters. Notably, SoFi’s non-lending operations accounted for 57% of total revenue in Q4 2025.
The higher contribution from lending indicates that SoFi is retaining more originated loans on its balance sheet. This increases interest income and supports revenue growth, but it also requires greater capital allocation. More importantly, keeping loans on its balance sheet exposes SoFi directly to credit risk and potential defaults. These risks can help explain the market’s more cautious view on the stock.
However, the significant decline in SoFi stock suggests those concerns are already somewhat reflected in the share price. Meanwhile, SoFi continues to expand its member base and is seeing higher adoption of products among existing customers, which is strengthening the economics of its broader financial ecosystem over time. SoFi is also focused on diversifying its revenue base and reducing its reliance on lending, which is likely to boost its share price.
SoFi’s Growth Drivers
SoFi’s growing member base and rising product adoption support continued growth. In the second quarter, the company added about 1.1 million members, bringing total membership to 15.8 million, a 35% year-over-year increase. At the same time, total products increased by 2.2 million to 24.4 million, a 42% increase from the prior-year period.
More importantly, product growth has outpaced membership growth by a significant margin, suggesting growth is increasingly driven not only by customer acquisition but also by higher monetization of its existing customer base. This is strategically important as higher engagement increases customer lifetime value and lowers the cost of acquiring incremental revenue.
The acceleration in cross-buy further supports this trend. Existing members accounted for 51% of new products opened during the quarter, up from 43% the previous quarter and 35% a year earlier. The rising contribution from existing customers indicates that members are increasingly using SoFi for multiple financial needs.
While SoFi is growing its membership base and seeing higher product adoption, its stock will likely get a significant boost from its push to expand capital-light revenue streams. Although changes in the revenue mix have created some near-term volatility, fee-based businesses are showing renewed momentum.
SoFi’s fee-based revenue reached $472 million in the second quarter, representing 39% of total revenue and increasing 22% sequentially. Growth came from several areas, including the Loan Platform Business (LPB), origination fees, interchange revenue, and brokerage-related income.
The LPB is a key catalyst for future growth. It helps generate fee income by originating and facilitating loans that are ultimately funded or purchased by third parties. This model lets the company scale its origination capabilities while limiting direct exposure to credit risk and reducing the capital required to support loan growth.
Looking ahead, management has also indicated it expects non-lending businesses to eventually contribute more than half of total revenue, which could spur a recovery in its share price.
SoFi Stock Is a Good Buy Now
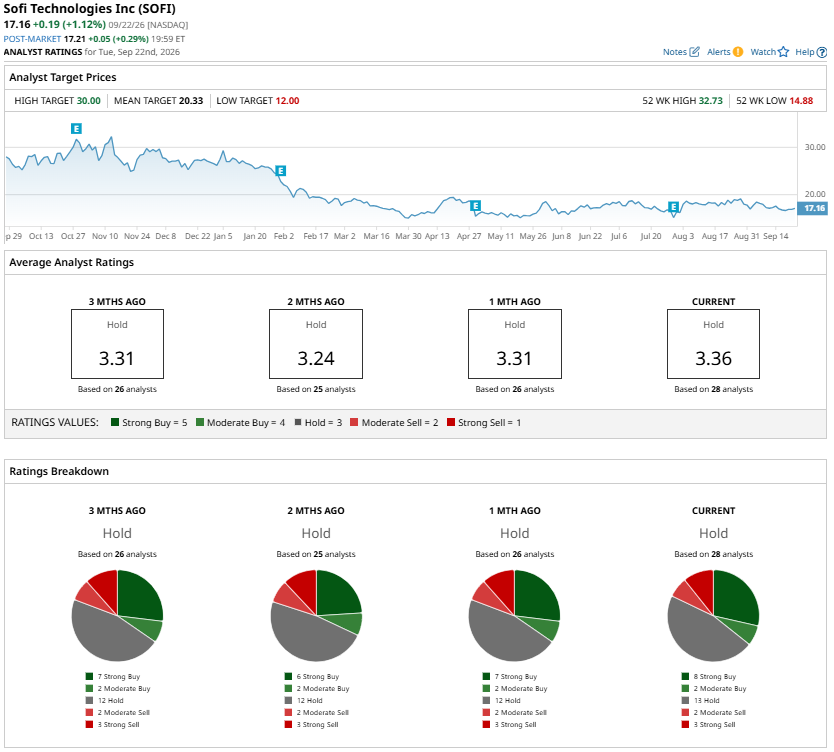
Wall Street analysts maintain a “Hold” consensus rating on SoFi stock, reflecting concerns about the company’s increasing exposure to its lending business. However, SoFi’s efforts to scale its non-lending, capital-light businesses, coupled with strong membership growth, greater product adoption among existing members, and an expanding deposit base — which provides a low-cost funding source — support the company’s long-term growth prospects. Moreover, the recent pullback in SoFi’s share price presents an attractive entry point.
On the date of publication, Sneha Nahata did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.