
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Old Dominion Freight Line (ODFL) Stock May Trade At A Premium To Cash Flow
Old Dominion Freight Line has delivered a 27.5% return over the past 5 years, which naturally puts the focus on whether the current share price around US$177 is still in line with what its cash flows can support. With the stock having moved both up and down over shorter periods, the question now is how much of the recent story is already reflected in the valuation.
- A 27.5% gain over 5 years means long term holders have seen meaningful value creation, which raises the stakes on whether the present valuation is fully backed by the cash the business can generate.
- The planned 4.9% general rate increase effective October 5, 2026 may support revenue per shipment and help offset cost pressures in wages, fuel and real estate, which can influence the level and durability of future cash flows.
- What if you looked at Old Dominion Freight Line through its earnings instead? See what Old Dominion Freight Line's 33.8x P/E says about the price.
The issue now is whether Old Dominion Freight Line's current share price is reasonably aligned with the intrinsic value suggested by its Discounted Cash Flow (DCF) estimate based on those cash flows.
If you are weighing Old Dominion Freight Line against other businesses where valuation hinges on cash generation, it can help to compare it with a wider group of 30 high quality undervalued stocks.
Is Old Dominion Freight Line Getting Expensive on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash Old Dominion Freight Line can generate for shareholders over time. On the latest numbers, the business produced roughly $872 million of free cash flow over the last twelve months, with analysts and extrapolated estimates pointing to growing annual cash generation by the end of the next decade.
That growth path assumes Old Dominion Freight Line remains a solid cash producer rather than a turnaround story, which is important when the stock already trades at $177.72. The DCF output suggests the estimated intrinsic value sits modestly below that price, so the market is giving the company some credit for continued execution and disciplined spending. Because the announced 4.9% general rate increase from October 5, 2026 is aimed at offsetting cost pressure rather than driving aggressive expansion, it helps explain why the valuation screens only slightly rich on cash flow rather than deeply stretched. Find out what Old Dominion Freight Line could be worth using our Discounted Cash Flow (DCF) estimate.
The Old Dominion Freight Line Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Old Dominion Freight Line's DCF puzzle leaves off and spell out which future paths for growth, margins and earnings would need to hold for the stock to be worth materially more or less than today. Each Narrative on the Community page treats Old Dominion Freight Line's fair value as a thesis about the business that can be tracked over time, rather than a single frozen snapshot.
Old Dominion Freight Line draws two very different readings from the community, with one group seeing more upside in the network than the other.
Bull case: 37% undervalued
"Old Dominion Freight Line's decision to keep more than 35% excess service center capacity and to invest an additional US$115 million in 2026 capex, including extra spend on tractors, trailers and real estate, creates room for higher shipment density through the network..."
Discover why this Narrative puts Old Dominion Freight Line at 37% undervalued.
Bear case: roughly fairly valued
"The continued weakness in LTL tons per day, with a 9% decline in the third quarter of 2025 and an 11.6% decline in October versus the prior year, points to prolonged demand pressure that could keep revenue growth subdued and limit operating leverage in the network..."
Explore why this Narrative puts Old Dominion Freight Line at roughly fairly valued.
One more Old Dominion Freight Line signal worth checking before you move on
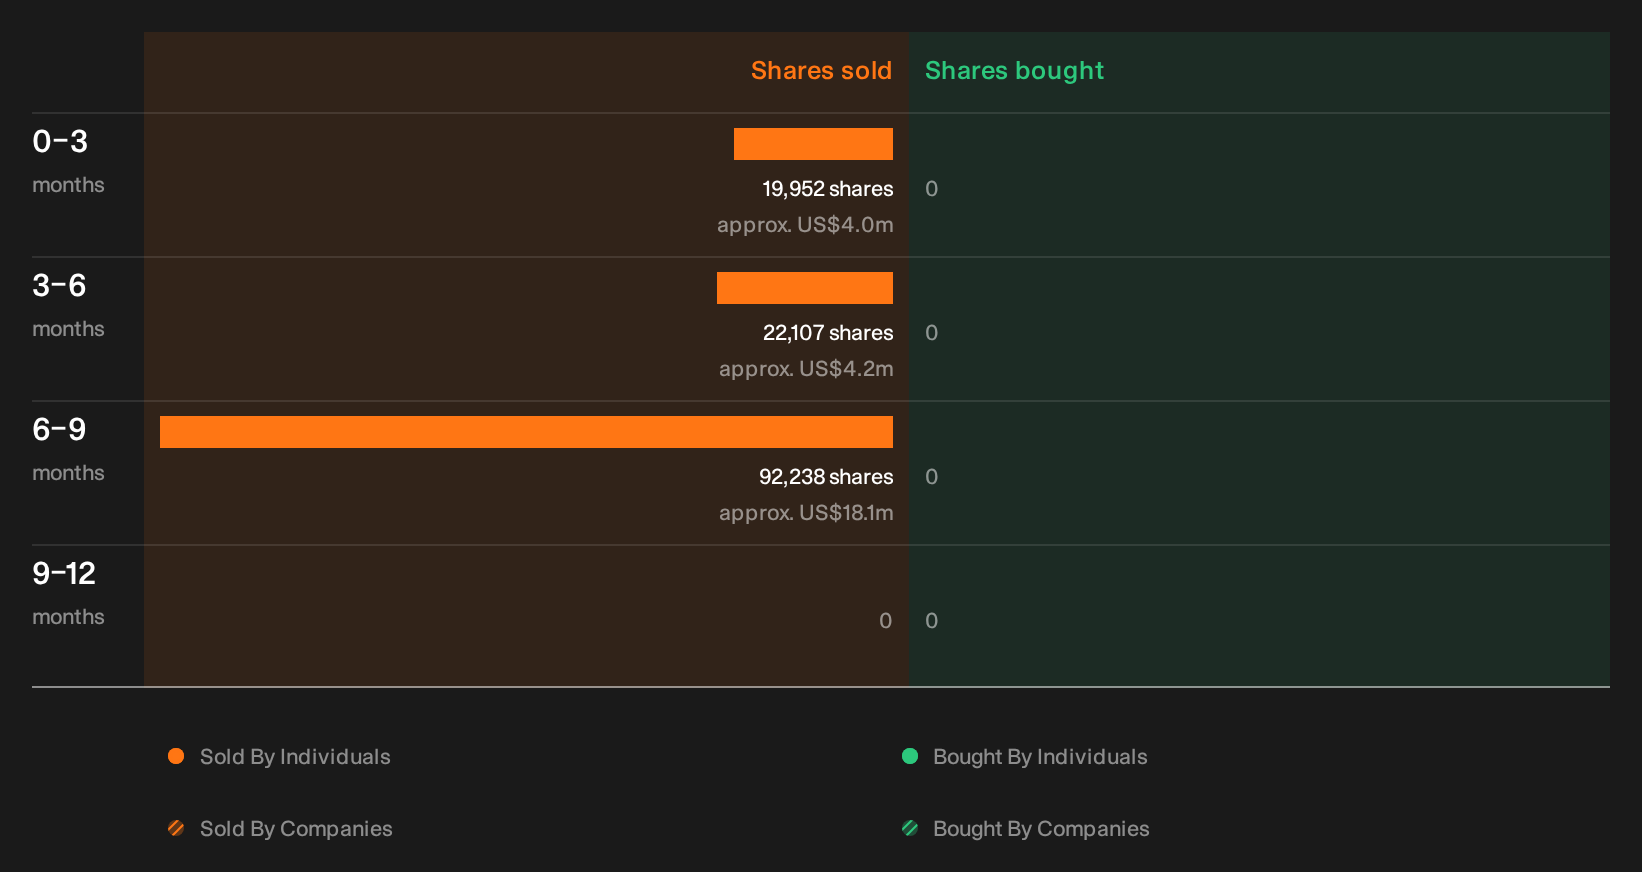
Before closing the book on Old Dominion Freight Line, it is worth pausing on one quieter clue. Recent insider share sales have been flagged by our checks and the individuals involved, the sizes and what they might suggest are all still for you to review. See the recent insider selling flagged for Old Dominion Freight Line.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com