
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Lockheed Martin (LMT) Wins $1.2 Billion PrSM Production Contract
- Lockheed Martin (NYSE:LMT) received a US$1.2b U.S. Army contract for Precision Strike Missile Increment 2 production.
- The agreement moves PrSM from development into production, with added capability to engage moving maritime targets.
- The contract expands Lockheed Martin's role in providing long range precision fires for U.S. and allied land forces.
- The PrSM Increment 2 production award should not be the only factor shaping your view of Lockheed Martin today. Take a look at 1 warning sign we have identified for Lockheed Martin.
Consider broadening your watchlist to other defense and aerospace contractors working on advanced long range missile systems our screener containing 16 high quality undiscovered gems.
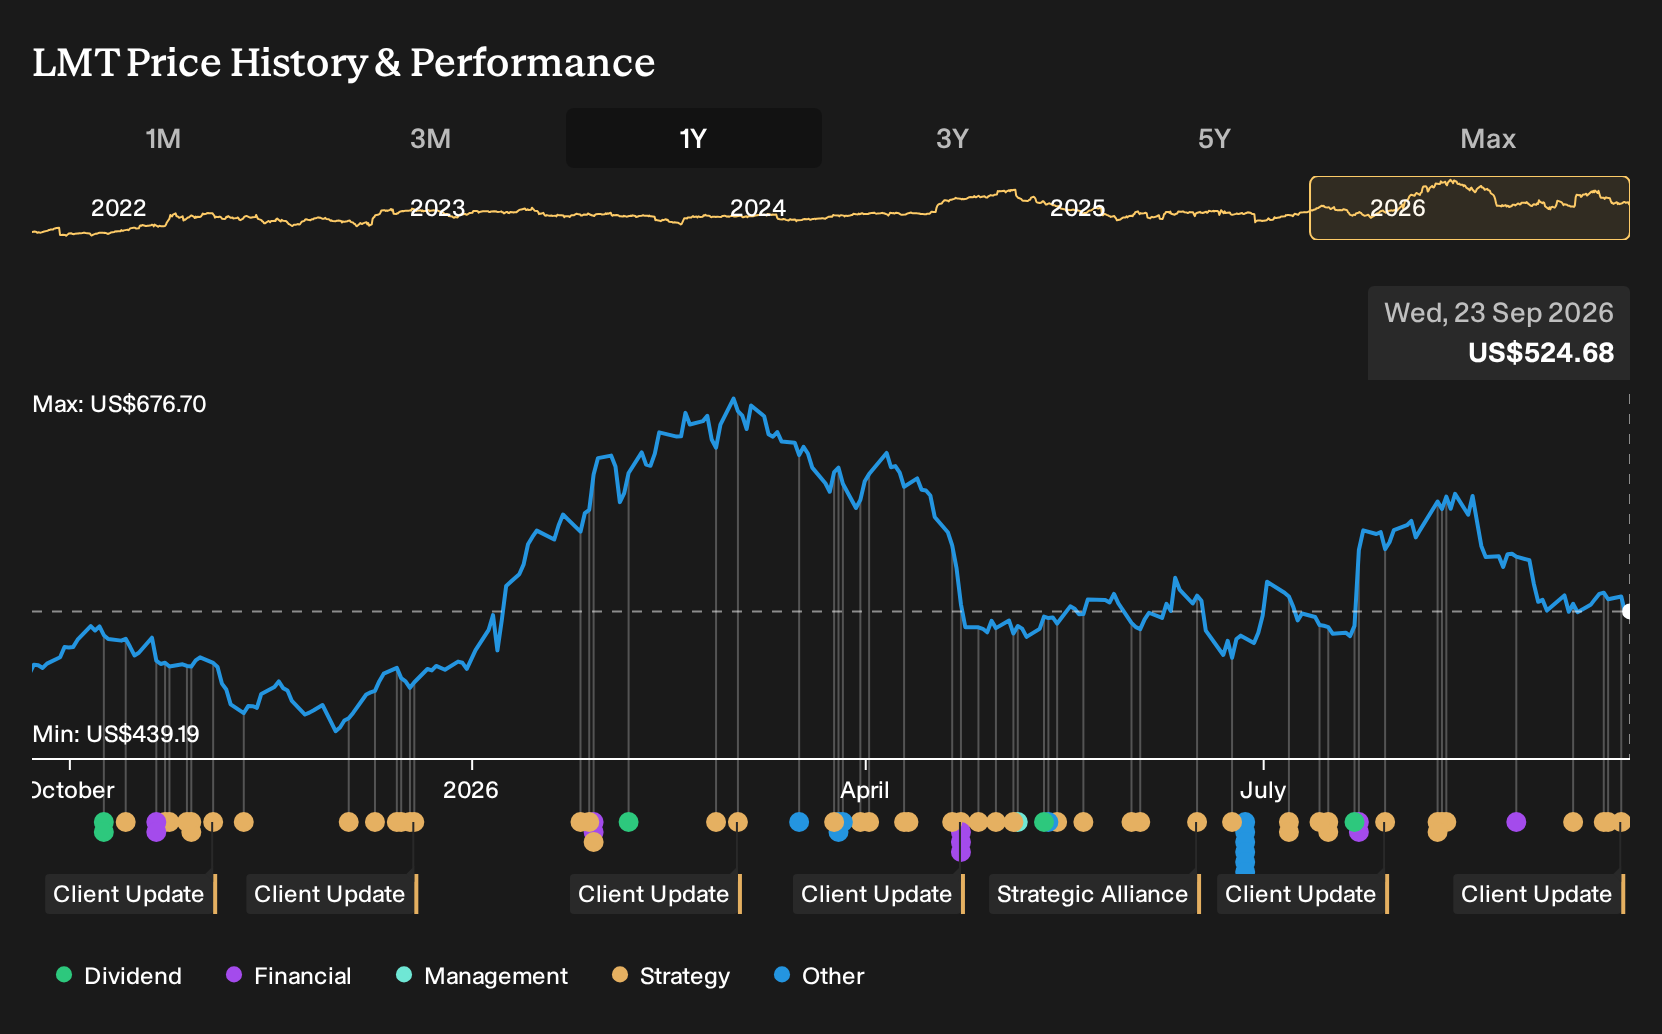
Lockheed Martin operates as a large US$120.6b aerospace and defense contractor that builds and supports advanced weapons, aircraft, and technology systems for militaries worldwide, so a missile program like PrSM fits directly into its core role of supplying long range precision firepower to land forces.
See which insiders are buying and selling Lockheed Martin following this latest news.
What This PrSM Contract Signals For The Lockheed Martin Story
The central bet in Lockheed Martin’s Narrative is that long term missile and munitions frameworks convert a large backlog into steadier revenue, higher margins and stronger free cash flow, rather than just headline contract wins.
"Lockheed Martin is moving munitions like PAC-3, THAAD, PrSM and JATM onto seven year framework agreements that aim to triple or quadruple production and allow the company to retain a larger share of cost savings from capacity investments such as robotics in Camden, which can support higher future revenue and structurally stronger net margins..."
See how the full story points towards a $638 fair value for Lockheed Martin.
This PrSM Increment 2 award reinforces the bullish side of that thesis. It pushes another missile program out of pure development and into an indefinite delivery, indefinite quantity structure that aligns with the framework approach described in the Narrative. For investors, it speaks directly to the idea that missile output, not just aircraft like the F 35, is a core earnings engine at Lockheed Martin.
The bear case is not erased. An IDIQ that spans procurement, follow on production and further development still brings execution and cost risk on a complex program, similar to what critics highlight on other fixed price and classified work. Compared with peers such as RTX or Northrop Grumman, any difficulty in scaling PrSM production or managing the supply chain would directly affect existing concerns around margin pressure and high debt.
The takeaway for readers is that the same PrSM contract can look like confirmation of a munitions led bull story or fresh fuel for execution worries, depending on which Lockheed Martin Narrative you already lean toward.
The one check on Lockheed Martin many readers skip before acting
Before you treat Lockheed Martin as a long term holding or a short term trade, it helps to see where analysts think the story actually heads over the next few years. See where analysts expect Lockheed Martin to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com