
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CRISPR Therapeutics (CRSP) Stock May Trade At A Premium To Book Value
CRISPR Therapeutics has seen a mixed share price journey in recent years, and that uneven record puts fresh focus on whether the current market value lines up with what its balance sheet actually supports. With the stock changing hands around book value related questions, the issue for you is how much weight to give that accounting base when thinking about today’s price.
- Over the past 5 years the share price has fallen 49.4%, which makes the gap between past investor experience and the value implied by its book equity especially important.
- The business relies heavily on research and development spending, which can affect both the size and reliability of its book value as a guide to long term earning power and potential capital needs.
- There is a second opinion on CRISPR Therapeutics worth weighing. See what analysts think CRISPR Therapeutics's shares could be worth.
The issue now is whether the current CRISPR Therapeutics share price is reasonably supported by its book value compared with the industry average.
If you are weighing CRISPR Therapeutics mainly through the lens of balance sheet strength, it can also help to scan a wider set of companies using the solid balance sheet and fundamentals stocks screener (23 results).
Has CRISPR Therapeutics Run Too Far on Book Value?
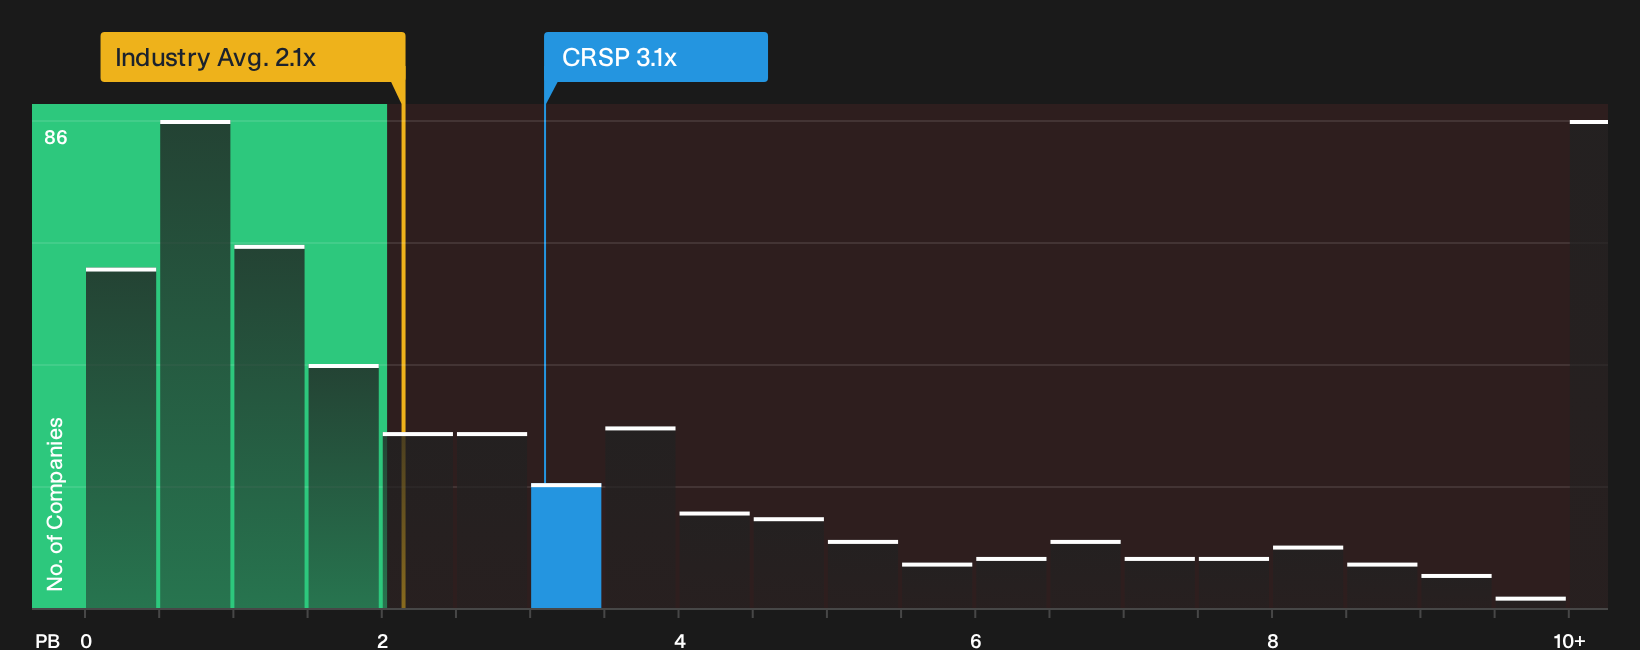
P/B is a useful cross check for CRISPR Therapeutics because the business is still heavily shaped by its balance sheet and research pipeline rather than steady profits. The current P/B of about 3.1x sits noticeably above the Biotechs sector average of roughly 2.1x, which means the market is paying a higher price for each dollar of accounting equity than is typical across the group.
That premium also looks large next to the peer set, where the average P/B is around 11.4x but is often skewed by a few extreme readings. For an investor, the key takeaway is that on a simple book value lens CRISPR Therapeutics screens as overvalued relative to the broader industry, so you would need to be comfortable that the research portfolio and future funding options justify paying more for its current equity base. Explore the numbers behind CRISPR Therapeutics's P/B valuation.
The CRISPR Therapeutics Narrative: What Would Justify Today's Price?
For CRISPR Therapeutics, Simply Wall St Narratives pick up where the P/B puzzle leaves off by spelling out which paths for future growth, margins and earnings would need to hold for the share price to be worth materially more or less than it is today. Each Narrative ties a specific fair value estimate to a clear storyline about potential catalysts and key risks, so you can track over time which version of CRISPR Therapeutics' future is gaining traction on the Community page.
One of the top community narratives on CRISPR Therapeutics: 36% undervalued
"The current valuation implies that the market is not fully pricing in the potential of CASGEVY to reach multibillion dollar sales..."
Discover why this Narrative puts CRISPR Therapeutics at 36% undervalued.
One more CRISPR Therapeutics clue before you move on
Before acting on today’s book value story for CRISPR Therapeutics, it is worth seeing how professional analysts currently map out its revenue, margins and cash needs over the next few years. Explore where analysts expect CRISPR Therapeutics to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com