
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Delta Air Lines (DAL) Fairly Valued Following Redburn's Reaffirmed Buy Rating?
Delta Air Lines (DAL) is back in focus for investors after Rothschild & Co Redburn reaffirmed its positive stance on the carrier, as easing oil prices reshape the fuel cost backdrop.
Recent trading has been choppy for Delta Air Lines, with the share price at US$81.75 after a 1-day share price return that declined 2.59%, even as the 7-day share price return gained 4.98% and year-to-date share price performance is up 18.38%. Over a longer horizon, total shareholder return has been much stronger, with a 1-year total shareholder return of 43.20% and a 3-year total shareholder return of 130.53%. This suggests that momentum has cooled in recent months after a strong multi-year run as investors weigh easing fuel costs, the upcoming October 9 earnings release and renewed attention from events such as Delta’s appearance at Morgan Stanley’s Laguna conference.
Scan beyond Delta Air Lines and see how other carriers with global reach and easing fuel costs stack up when you use our curated list of list of solid balance sheet and fundamentals (23 results)
Delta Air Lines has cooled after a strong multi year run and now trades at a premium to industry P/E and PEG multiples. Does that premium still look justified when compared with its earnings power and risks?
Most Popular Narrative: 29% Overvalued
On the most widely followed valuation story, Delta Air Lines screens as expensive, with the share price at $81.75 versus a fair value of $63.21 according to PittTheYounger.
Atlanta's home airline still shines bright, and indeed brighter than most in a notorious low-margin, low-profit industry. In its Q2 trading update, Delta once again trounced analysts' expectations both top and bottom line, yet there's a snag: The legacy carrier comes from all-time high profitability. Hence, the risk distribution is skewed to the downside as long as there's no final and reliable re-opening of the Strait of Hormuz. That is why I stick to my valuation even in the face of shares trading some 38 per cent in excess of my calculations, because the latter is just that: excess. A current PE at some 14.5 and a forward PE at around 12 are simply too rich against this macro and geoeconomic backdrop, and Delta would have to increase its current profit margins considerably to justify these multiples, which is a well nigh impossible order.
See why 23 investors see Delta Air Lines as 29% overvalued.
Result: Fair Value of $63.21 (OVERVALUED)
Still, Delta Air Lines faces potential spoilers to that overvaluation call if fuel costs rise again or if global travel demand weakens more sharply than recent updates imply.
Find out about the key risks to this Delta Air Lines narrative.
Another View On Delta Air Lines Valuation
The user narrative pegs Delta Air Lines as 29% overvalued at $81.75, yet our DCF model points in the opposite direction. In that framework, the shares trade at a large discount to an estimated future cash flow value of $230.25, which screens as significantly undervalued. Which story aligns better with your approach for a long holding period?
Look into how the SWS DCF model arrives at its fair value.
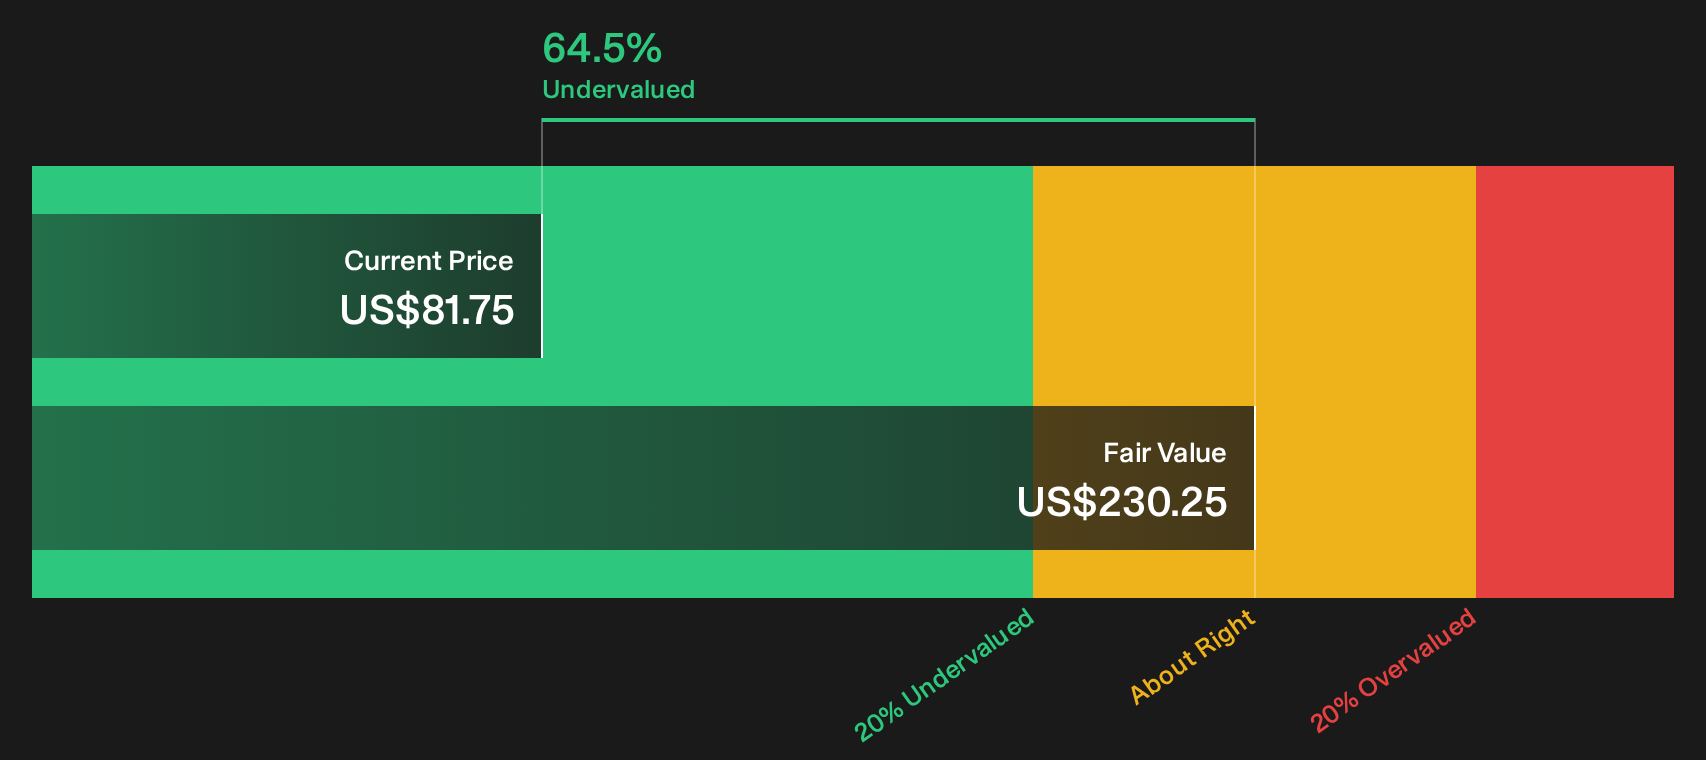
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Delta Air Lines for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Delta Air Lines is clearly split, so move quickly, review the underlying data and evaluate both sides of the argument for yourself with 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Delta Air Lines?
If Delta Air Lines has sharpened your focus on quality and valuation, use that momentum and widen your watchlist with a few carefully filtered ideas.
- Target resilient balance sheets and dependable fundamentals by scanning a curated list of solid balance sheet and fundamentals (23 results) that filters out weaker financial profiles.
- Hunt for potential mispricings by reviewing a focused 30 high quality undervalued stocks that highlights companies where price and fundamentals tell very different stories.
- Build a portfolio with staying power by checking a hand picked 31 resilient stocks with low risk scores that emphasizes steadier risk profiles over headline excitement.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com