
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Lattice Semiconductor (LSCC) Expensive After Its AI Tool And Secure FPGA Launches?
Lattice Semiconductor (LSCC) has released a series of product updates that may draw investor attention. New launches of its Lattice Prompt AI tool and Mach-N2 secure control FPGAs come alongside index inclusion.
Recent trading tells a mixed story. Lattice Semiconductor’s share price has climbed 54.69% year to date and delivered a 68.62% one year total shareholder return. However, the 90 day share price return declined 15.63%, suggesting strong long term momentum but some cooling after the latest product and index news.
Compare how Lattice Semiconductor stacks up against other chip players riding similar AI and infrastructure themes by reviewing the curated 85 AI infrastructure stocks that may be catching fresh momentum.
Lattice Semiconductor now trades well below the average analyst target, yet well above some intrinsic value estimates. With that gap widening after the recent rally, the question becomes: where does fair value really land for this stock?
Most Popular Narrative: 26% Undervalued
Lattice Semiconductor closed at $121.66, while the most followed narrative pegs fair value at $164.92, so the spread between price and modelled worth is wide and heavily tied to how durable AI and server demand prove to be.
The ongoing AI and edge computing boom is driving hyperscale data center spend and increasing Lattice's attach rate as a companion chip for AI accelerators, servers, and networking equipment, leading to higher ASPs and robust design wins; this should accelerate revenue growth and support gross margin expansion.
See why 23 investors see Lattice Semiconductor as 26% undervalued.
The narrative uses an 11.21% discount rate and a fair value of $164.92 per share, which is above both the analysts’ average target of about $164.54 and Simply Wall St’s own DCF output of $74.37. That gap reflects heavy weight on forecasts that call for revenue growth of roughly 45% per year, profit margins rising toward 26.5%, and earnings expanding very quickly compared with the broader US market.
On the other side of the ledger, the same storyline flags meaningful risks around competition in low and mid range FPGAs, exposure to China, industry cycles, and higher spending needs. Those pressure points sit alongside current net margins of 5.6%, which are below last year’s 6.4%, and a recent one off loss of $12.1m that clouds the latest 12 month earnings quality.
For an investor looking at Lattice Semiconductor today, the key question is how much of that growth and margin rebuild feels realistic when set against those risks. The higher fair value only holds if the business gets close to the $2.0b revenue and $525.1m earnings profile that analysts have mapped out and if the market is willing to pay a future P/E near 68.7x on those profits.
Result: Fair Value of $164.92 (UNDERVALUED)
Still, the bullish Lattice Semiconductor story can crack if China exposure faces tighter controls or if low and mid range FPGA rivals squeeze pricing and share.
Find out about the key risks to this Lattice Semiconductor narrative.
Another View: Lattice Semiconductor Looks Expensive On Sales
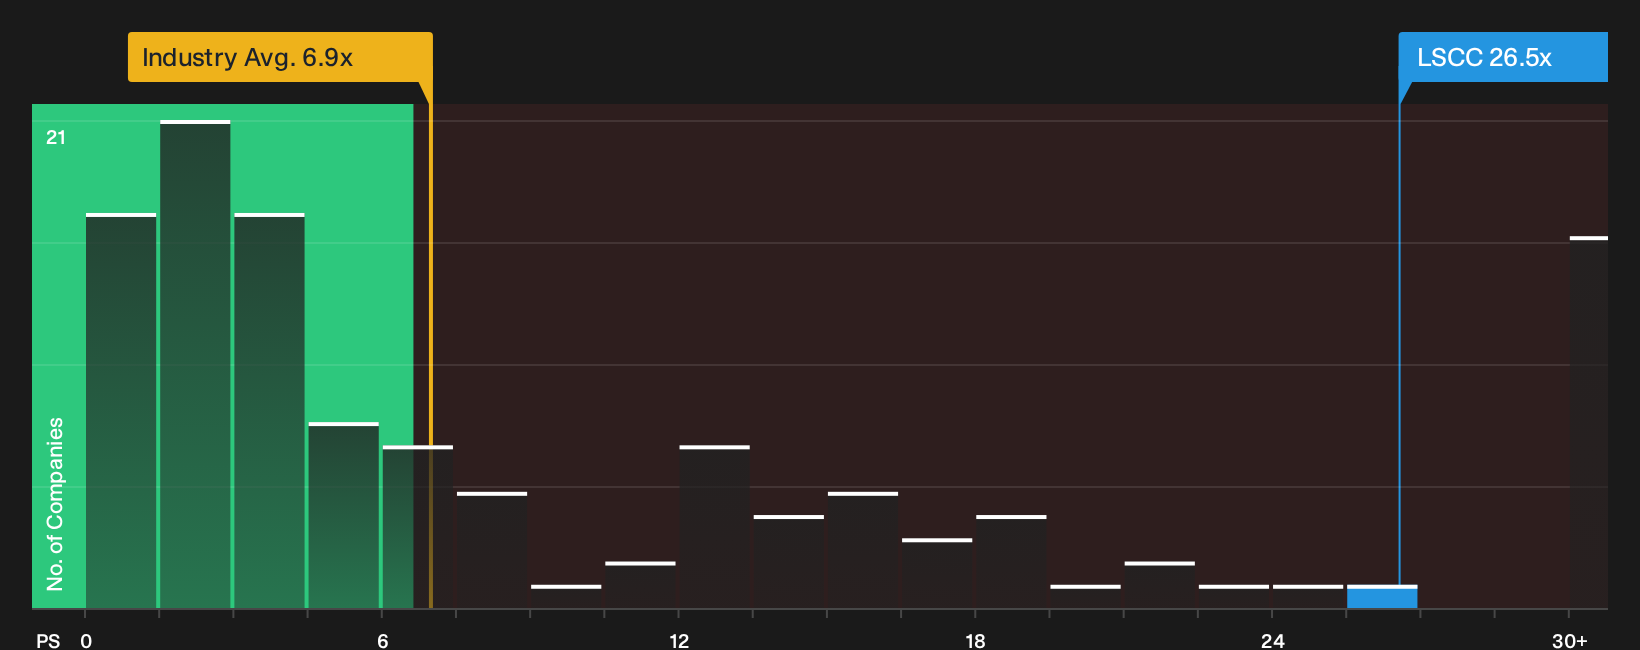
The fair value of $164.92 comes from a narrative that leans heavily on growth and margin rebuild. A simple P/S check paints a tougher picture. Lattice Semiconductor trades on 26.5x sales versus 6.9x for the US Semiconductor group and 6.3x for peers, while the fair ratio is 17.4x. That gap suggests investors today are paying a rich premium for the story. How comfortable do you feel underwriting that kind of multiple?
To see how this price tag stacks up against the underlying numbers in more detail, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Lattice Semiconductor can split opinion, so move quickly, review the full data set and weigh both upside and downside. To see that balance clearly, walk through the 2 key rewards and 1 important warning sign
Looking for more Lattice Semiconductor investment ideas?
If you want a fuller watchlist around Lattice Semiconductor, use the Simply Wall St Screener to quickly scan different angles and avoid missing potential opportunities.
- Target stability first by checking companies that show resilient balance sheets and durable fundamentals through the list of solid balance sheet and fundamentals (23 results).
- Hunt for quality at a discount by filtering for businesses that combine strong fundamentals with appealing valuations using the 30 high quality undervalued stocks.
- Spot future market favorites early by reviewing financially sound smaller stocks that could be overlooked through the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com